Connect with us

Methanol

ENGINE on The Week in Alt Fuels: Why isn’t methanol catching up (yet)

In contrast to LNG, methanol-capable vessel orders have hit a wall; major challenge could be bunkering infrastructure as dedicated methanol bunkering facilities remain scarce outside key regions.

Admin

Published

on

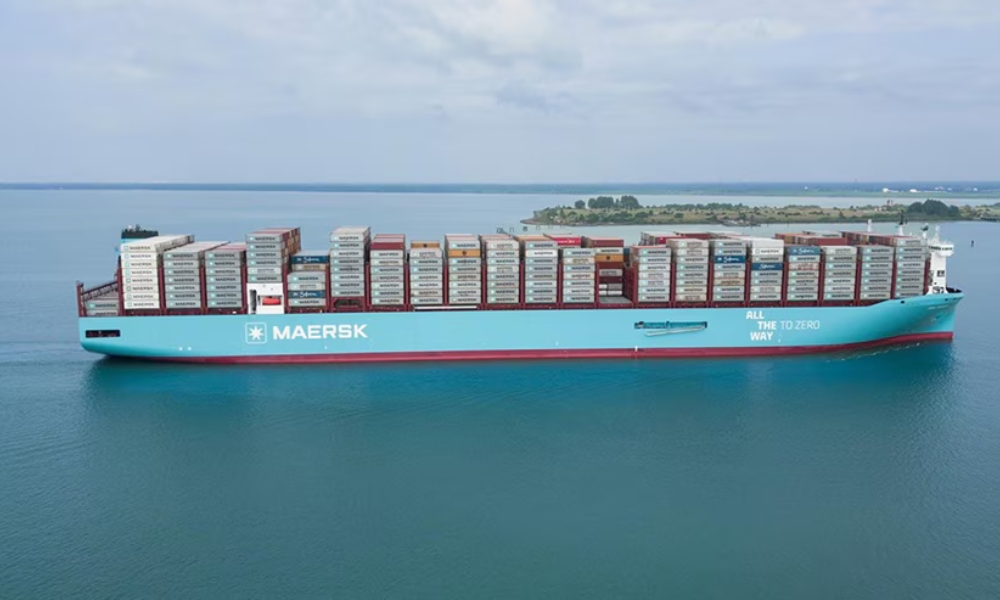
Maersk vessel

Methanol-capable vessel orders have stagnated, even with the IMO’s mid-term measures looming on the horizon.

DNV’s latest vessel order tally shows a clear divide. Investments in LNG-capable vessels are rising, while methanol-capable orders have stalled. In February, 33 out of 34 alternative-fuel vessel orders were LNG-capable, marking a sharp jump from just 12 orders in January, said Kristian Hammer, senior analyst at DNV.

One key factor behind rising investments in LNG-capable vessels could be flexibility. While LNG is a fossil fuel, it is combusted in engines that can also run on bio-LNG and e-LNG. On a chemical level, these can be identical products – they are all methane. This means that LNG-capable dual-fuel vessels won’t be tied to fossil LNG forever, making the vessels a future-proof investment for shipowners.

With 685 LNG-capable vessels already in operation and another 634 on order for deliveries towards 2033, shipowners seem to be betting on this adaptability.

In contrast, methanol-capable vessel orders have hit a wall. DNV data shows that not a single methanol-capable vessel was ordered in February, raising questions about the industry’s appetite for the fuel.

A major challenge could be bunkering infrastructure. Dedicated methanol bunkering facilities remain scarce outside key regions like the ARA and select ports in Asia.

Only nine dedicated methanol bunker vessels are in operation today. They serve 57 methanol-capable ships, with nearly all of them deployed in Asia. Just six more bunker vessels are on order for delivery by 2026, when the methanol-capable fleet is expected to grow by another 173 vessels. The lack of dedicated methanol bunker vessels limits refueling options, often restricting bunkering to terminal-to-ship or tanker-to-ship operations.

Another drawback could be global availability.

The Methanol Institute’s database shows that most of the operational bio-methanol production plants today are concentrated in the US and Asia. Transporting bio-methanol from these locations to major bunkering hubs in Europe, the Middle East, Africa or South America could be a costly affair and complicate logistics, which could translate into a hefty price tag for bunker buyers.

On contrast, liquefied biomethane (LBM) – or bio-LNG – can leverage LNG’s well-established bunkering networks. Gaseous biomethane can be supplied to desired locations through existing gas pipelines using an accounting technique called mass-balancing and then liquefied near the point of bunkering. This eliminates the high costs of physically transporting the fuel between regions and could make LBM a more cost-effective and scalable option for shipowners.

Even where methanol bunkering is possible, the high cost of its greener variant presents another hurdle. A fuel cost calculator developed by the Maersk Mc-Kinney Center for Zero Carbon Shipping (MMMCZCS) estimates the VLSFO-equivalent cost of bio-methanol at $1,485/mt in the EU. In comparison, the VLSFO-equivalent cost of LBM is cheaper at $1,161/mt in Rotterdam.

Even with the IMO’s mid-term measures looming on the horizon, shipowners appear reluctant to invest in methanol-capable vessels, possibly due to infrastructure limitations, supply constraints and high costs. On the other hand, shipowners planning long-term strategies today may find LNG-capable vessels appealing because of the versatility of LNG-compatible engines to use more sustainable LBM.

In other news this week, Singapore-registered bunker vessels will be allowed to carry and deliver stems with up to 30% (B30) biofuel from tomorrow. The MPA has urged “shipowners, ship managers, operators and masters” of Singapore-registered conventional bunker carriers to comply with this circular. “There is no requirement to seek MPA’s separate approval,” the circular said.

US-based renewable energy firm StormFisher Hydrogen will produce 50,000 mt/year of e-methane at its proposed North American facility. The facility will use renewable energy input from wind and solar energy to produce green hydrogen via electrolysis and biogenic CO2 for feedstocks to then produce e-methane.

Hong Kong-based ship management firm Anglo-Eastern has launched a training skid for ammonia and LNG bunkering near Mumbai, India. The bunker station skid is equipped with cryogenic fuelling technology and safety systems, allowing for real-life simulations of ammonia and LNG bunkering operations.

The US Department of Energy (DoE) has modified a prior order issued to JAX LNG, removing regulatory barriers for LNG as marine fuel. The DoE will no longer exercise its Natural Gas Act jurisdiction over ship-to-ship LNG bunkering in US ports, US waters and international waters.

By Konica Bhatt


Photo credit: A.P. Moller-Maersk
Source: ENGINE
Published: 10 March, 2025

Continue Reading

Decarbonisation

DNV: New research shows how regulation could reshape shipping

DNV summarizes findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness.
Admin

Published

on

By

DNV flag

Classification society DNV on Thursday (24 September) released a new article summarizing findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness: 

Shipping’s energy transition has entered a new phase. The technology options are increasingly well understood. LNG, methanol, biofuels, wind-assisted propulsion, and emerging ammonia solutions are no longer concepts but commercial realities. Yet despite this progress, shipowners face a more difficult challenge than ever: making investment decisions amid unprecedented regulatory uncertainty.

The 2026 edition of DNV’s Maritime Forecast to 2050 argues that uncertainty itself is now becoming one of the most important drivers of fleet strategy. 

“Decisions taken today on vessel design, retrofits, and fuel capability will determine competitiveness for decades, while the outcome of ongoing regulatory negotiations could significantly reshape the economics of shipping’s energy transition,” says Øyvind Sekkesæter, Senior Consultant at DNV and lead author of this year’s report. “Maritime Forecast to 2050 aims to assist that decision-making with our latest core insights and case study examples.”

Four regulatory scenarios could shape shipping very differently

This year’s Maritime Forecast takes a scenario-based approach, presenting four possible regulatory futures for shipping. These range from the full adoption of IMO’s initially approved Net-Zero Framework (NZF) to its rejection and prolonged political gridlock, while also exploring several intermediate outcomes, including a delayed or revised NZF and scenarios where regional regulations play a more prominent role in driving decarbonization. Rather than predicting which outcome is most likely, the scenarios illustrate how different regulatory futures could affect fuel demand, energy-efficiency uptake, investment signals, and fleet competitiveness.
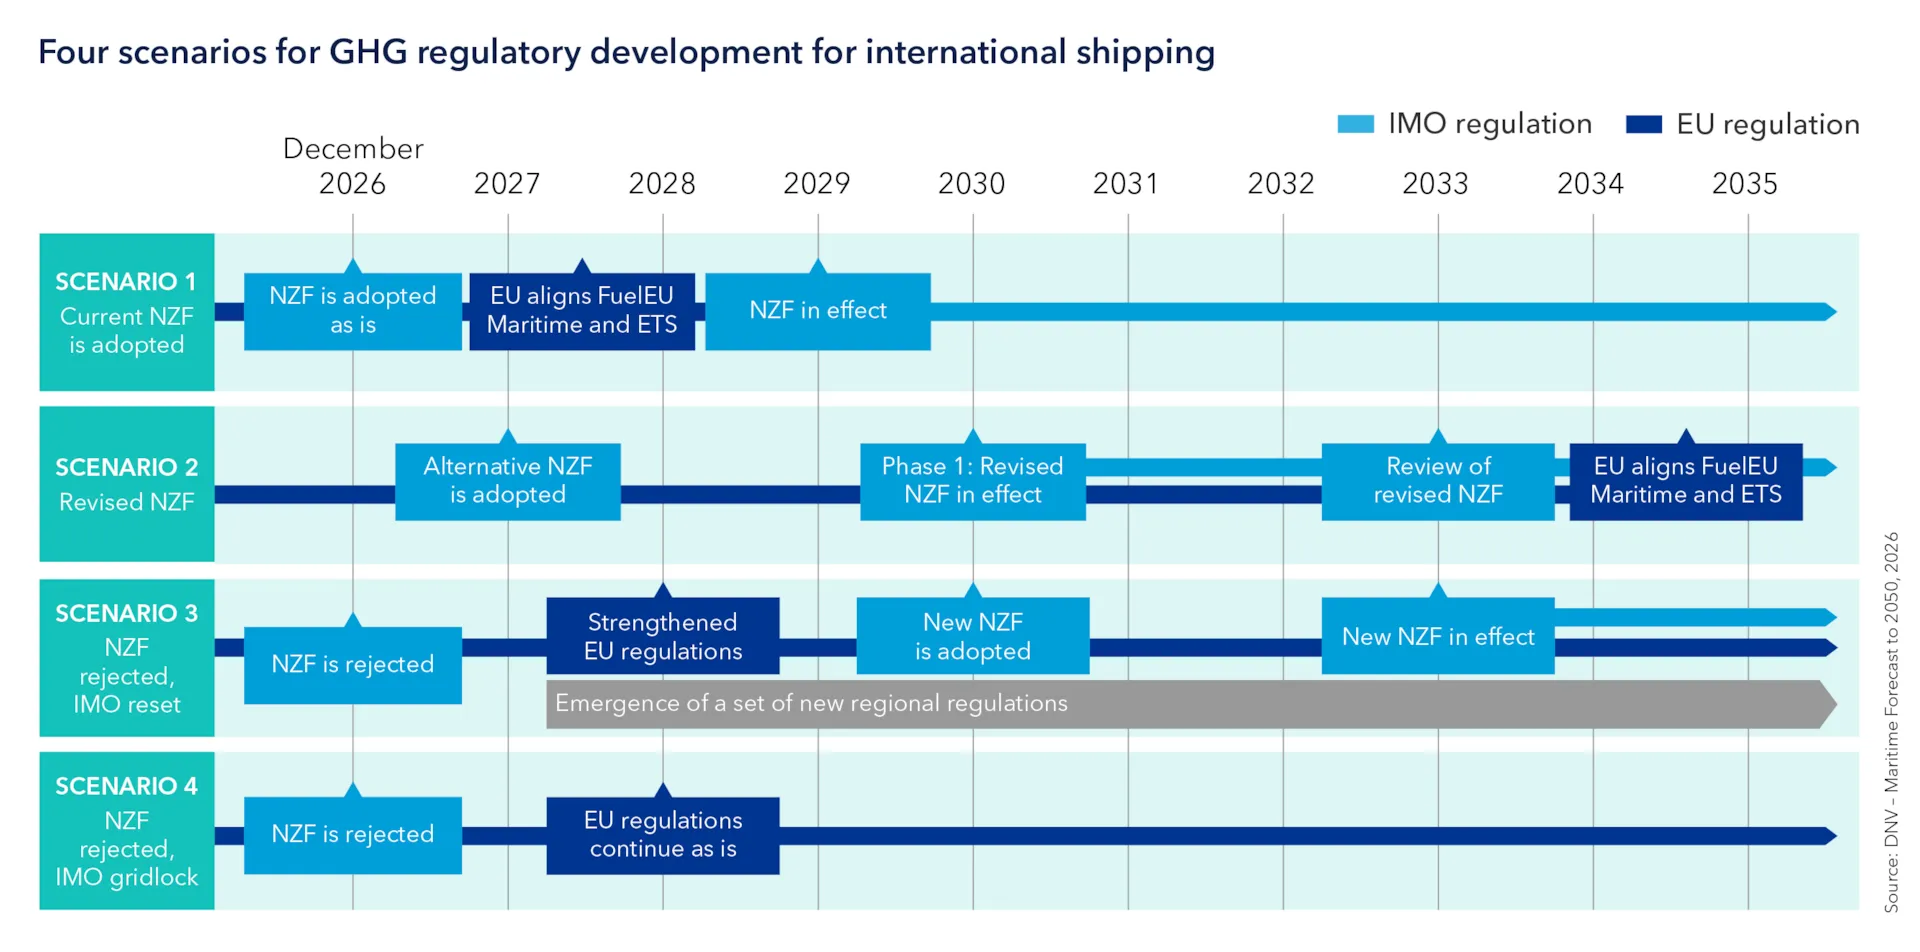
t1 ind 673 scenarios

Stronger global regulation accelerates demand for low-GHG fuels and increases the attractiveness of energy-efficiency measures, while the absence of such regulation slows market development. The result is a transition whose pace may vary significantly depending on future policy decisions.

“For shipowners, this means the challenge is no longer identifying a single fuel pathway that fits the operational profile of their fleet. Instead, it is preparing fleets that remain competitive across multiple possible futures,” Sekkesæter concludes.

Tapping the fleet’s efficiency potential

Fully realizing the fleet’s energy-saving potential requires improvements not only to newbuilds but also to existing ships through retrofits.

Installing energy-saving devices during scheduled dry-docking can be a highly cost-effective decarbonization strategy, as illustrated by the Maritime Forecast’s case study of a hypothetical 15-year-old 5,000 TEU containership (built in 2013).

This envisages USD 2.35 million being invested to retrofit the ship with hydrodynamic enhancements including a bow retrofit, propeller upgrade, and a propeller boss cap fin.

The vessel can achieve estimated fuel savings of around 16% under the modelling assumptions. Evaluating the investment under three price scenarios for low sulphur heavy fuel oil (LSHFO) results in payback periods from 1.4 years to 4.2 years.

Note: The full Maritime Impact article by DNV can be found here. 


Photo credit: DNV
Published: 25 September, 2026

Continue Reading

Alternative Fuels

Höegh Autoliners orders six more ammonia, methanol-ready Aurora class PCTCs

Höegh Autoliner inked a contract with China Merchants Group for six additional Aurora class PCTCs, which will be built by China Merchants Heavy Industry (Jiangsu) and delivered between 2029 and 2031.
Admin

Published

on

By

Höegh Autoliners orders six more ammonia, methanol-ready Aurora class PCTCs

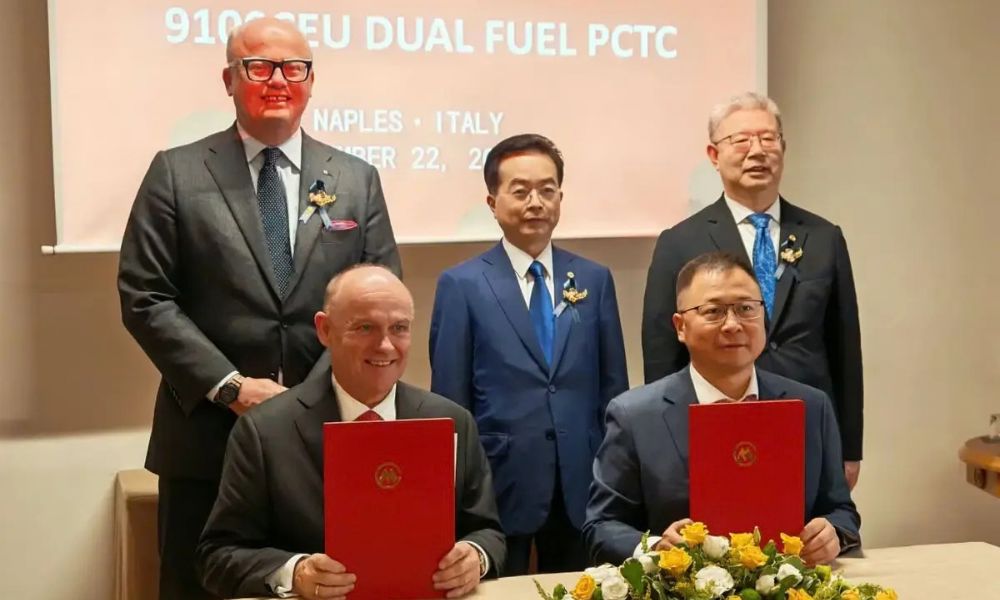
Höegh Autoliners on Tuesday (22 September) said it has formally signed a contract with China Merchants Group (CMG) for six additional Aurora class pure car and truck carriers (PCTCs). 

The contract was signed during a high-level meeting in Naples attended by senior representatives from both companies, including Miao Jianmin, Chairman of China Merchants Group. Chair of Höegh Autoliners, Leif O. Høegh, and Andreas Enger, CEO of Höegh Autoliners.

The six additional dual-fuel LNG and zero-carbon-ready vessels will be built by China Merchants Heavy Industry (Jiangsu) Co., Ltd. (CMHI) and delivered between 2029 and 2031. 

With 18 Aurora Class vessels in the programme, Höegh Autoliners is building the fleet needed for a zero- emission future and setting the pace for the transformation of deep-sea shipping.

The Aurora Class vessels can carry up to 9,100 cars and reduce carbon emissions per transported car by up to 58 per cent compared with conventional PCTCs. They have DNV’s ammonia-ready and methanol-ready notations and are designed to be converted to run on future zero-carbon fuels.

Leif O. Høegh, Chair of the Board of Directors of Höegh Autoliners, said: “For nearly 100 years, we have developed, adapted and led the way through major changes in shipping. It is in our DNA to keep moving and challenge what is possible. This signing continues that story. We are investing in the vessels that will define our fleet for decades and help move our industry towards zero emissions.”

Andreas Enger, CEO of Höegh Autoliners, said: “This is not just another vessel-building agreement. It is a statement about the future of deep-sea shipping and the role we intend to play in shaping it. The Aurora Class is at the heart of our fleet renewal and our path to a sustainable future. By expanding the programme to 18 vessels, we are securing efficient, flexible and future-ready capacity while setting the pace towards zero-emission operations.”

Miao Jianmin, Chairman of China Merchants Group, said: “Höegh Autoliners is a pioneer in international shipping and will celebrate its 100th anniversary next year. We would like to offer our congratulations in advance! Over the past century, Höegh Autoliners has achieved remarkable development and has grown into a leading company in the global RoRo shipping sector. We truly admire what you have accomplished.”


Photo credit: Höegh Autoliners
Published: 24 September, 2026

Continue Reading

Alternative Fuels

GCMD, Equinor to combine expertise on alternative bunker fuels, decarbonisation solutions

Equinor brings extensive experience to partnership as a vessel charterer and marine fuel supplier, including chartering dual-fuel LNG and methanol tankers, testing biofuels and supplying methanol.
Admin

Published

on

By

GCMD, Equinor to combine expertise on alternative bunker fuels, decarbonisation solutions

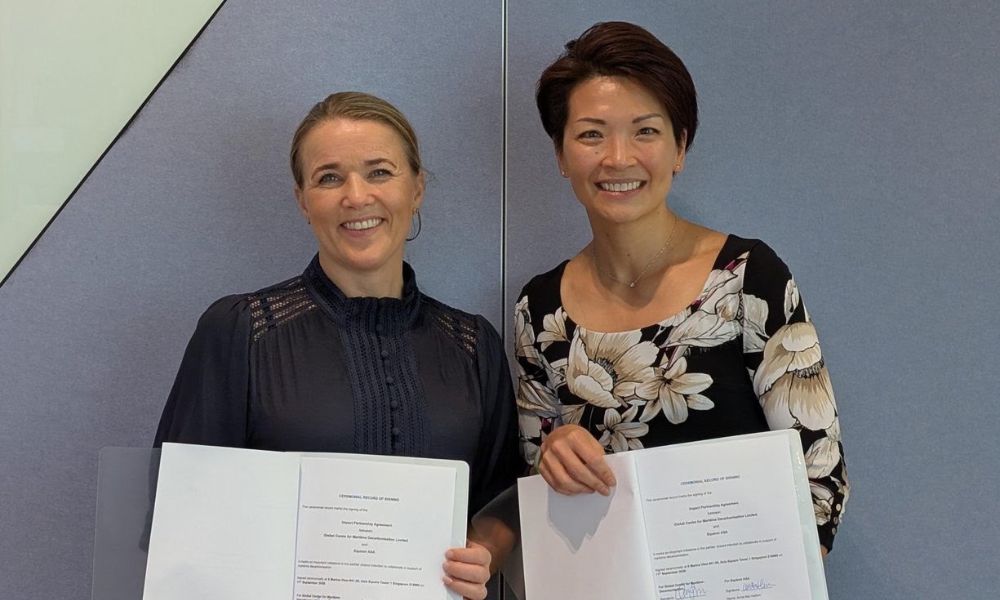
The Global Centre for Maritime Decarbonisation (GCMD) and Equinor on Tuesday (22 September) announced a five-year Impact partnership.

The partnership brings together GCMD’s capabilities in conducting real-world maritime pilots with Equinor’s experience as a charterer, energy provider and developer of low-carbon solutions.

Together, the organisations will leverage their complementary expertise to help address technical and operational gaps in scaling alternative marine fuels and supporting the development and uptake of other maritime decarbonisation solutions.

GCMD’s work on alternative fuels, including biofuels, ammonia and methanol, focuses on two critical aspects of deployment: operational safety and robust monitoring, reporting and verification (MRV). Its pilots and studies are generating operational data to support safe bunkering and handling of these fuels. 

At the same time, its assurance work seeks to strengthen confidence in quantity, quality and GHG emissions abatement.

“Equinor brings extensive experience as a vessel charterer and marine fuel supplier. This includes chartering dual-fuel LNG, LPG and methanol tankers, testing and using biofuels and supplying methanol to the maritime sector,” GCMD said.

Equinor is also piloting the use and supply of ammonia as a marine fuel, contributing to the development of associated safety, regulatory and bunkering arrangements.

Combining these perspectives can help address practical barriers to alternative fuels deployment while strengthening assurance across emerging marine fuel value chains.

Beyond alternative fuels, GCMD is working to accelerate the adoption of solutions that can reduce emissions from the existing fleet, including energy efficiency technologies (EETs) and onboard carbon capture and storage (OCCS).

GCMD’s work on EETs includes quantifying real-world fuel savings from technologies such as wind-assisted propulsion systems and developing financing mechanisms to scale their adoption. In OCCS, Project CAPTURED demonstrated an end-to-end value chain for onboard captured and liquefied CO₂, generating evidence that contributed to the recognition of captured CO2 under the EU ETS and in-principle support at the IMO for recognising carbon mineralisation as permanent storage.

Equinor brings decades of experience in offshore CO₂ storage, including its role in the development and operation of Northern Lights, the world’s first cross-border CO2 transport and storage facility, where liquefied CO₂ is transported by ship to an onshore receiving terminal before it is sent by pipeline for permanent geological storage beneath the North Sea.

Through the partnership, GCMD and Equinor will explore opportunities to combine their respective capabilities and experience to support the deployment and scaling of maritime decarbonisation solutions.


Photo credit: Global Centre for Maritime Decarbonisation
Published: 23 September, 2026

Continue Reading

Trending