Bunker Fuel
Integr8 Fuels: Why bunker markets could be lower than we thought
Marine fuel prices could prove lower than previously anticipated as easing refinery margins and improving bunker market fundamentals outweigh a still-uncertain crude oil outlook, says Integr8 Fuels.

By Steve Christy, Expert Contributor, Integr8 Fuels
29 July 2026
We have just seen one false dawn, is there another to come?
Last month, we wrote about how close we were to the expected lows in Brent and Rotterdam bunker prices, but not yet Singapore. Given what has happened since, a month is not only a long time in politics, but also a very long time in the bunker market.
There was a resumption of attacks in the Arabian Gulf region on 13 July, followed by targeted Houthi attacks on Saudi Arabia’s Red Sea oil infrastructure and shipping in the Bab el-Mandeb region, the gateway between the Red Sea and the Gulf of Aden. As a result, Brent futures fell to lows of around $70/bbl in late June and early July before surging to a high of $100/bbl on 23 July. Over the same period, Singapore VLSFO fell to $635/mt before climbing to $865/mt, a swing of $230/mt in just 16 days.
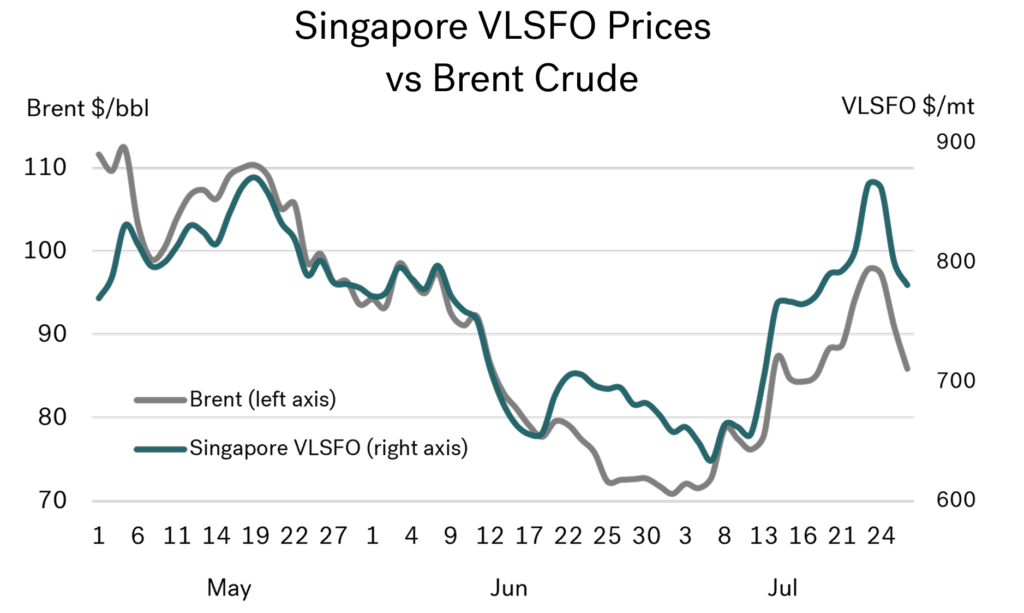
Prices at the start of this week fell sharply after a halt in Arabian Gulf attacks over the weekend, with front month Brent was down to intra-day lows of $84/bbl, and Singapore VLSFO $750/mt. However, at the time of writing there has been a ‘surprise’ attack by Iran, and retaliatory action by the US, with prices rising again. It looks like we could be at another false dawn.
The obvious questions are: will there be a return to peace negotiations, and are we close to the end of the war and free-flowing traffic through the strait of Hormuz (and also the Bab el-Mandeb)? The obvious answer is, we don’t know; there are only a few people that are likely to know the answer to this. All we can do is plan for every eventuality.
Low stocks, higher bunker prices, and a strong Singapore VLSFO premium: it’s a challenge
For those of us in the bunker market, the point we made last month about Singapore VLSFO trading at a strong premium to crude still holds, albeit slightly less pronounced. The loss of supplies through the Strait of Hormuz, together with the added uncertainty surrounding Saudi product exports from the Jizan and Rabigh refineries on the Red Sea, has sustained this premium.
These developments are likely to keep the Singapore VLSFO premium to crude at elevated levels until there is greater confidence that Middle East crude and product supplies are returning to more normal trading patterns. Amid all the price volatility, this Singapore VLSFO premium remains a key indicator to watch.
Backwardation in Brent futures illustrates market psychology
One month ago, backwardation in Brent futures (front month minus second month) had fallen from $7/bbl to virtually nothing, reflecting the market’s belief that an end to the war was little more than a negotiating step away. It wasn’t. The resumption of attacks, coupled with Houthi involvement in the Red Sea, sent prices sharply higher again, with backwardation in the Brent futures market returning to almost $6/bbl.
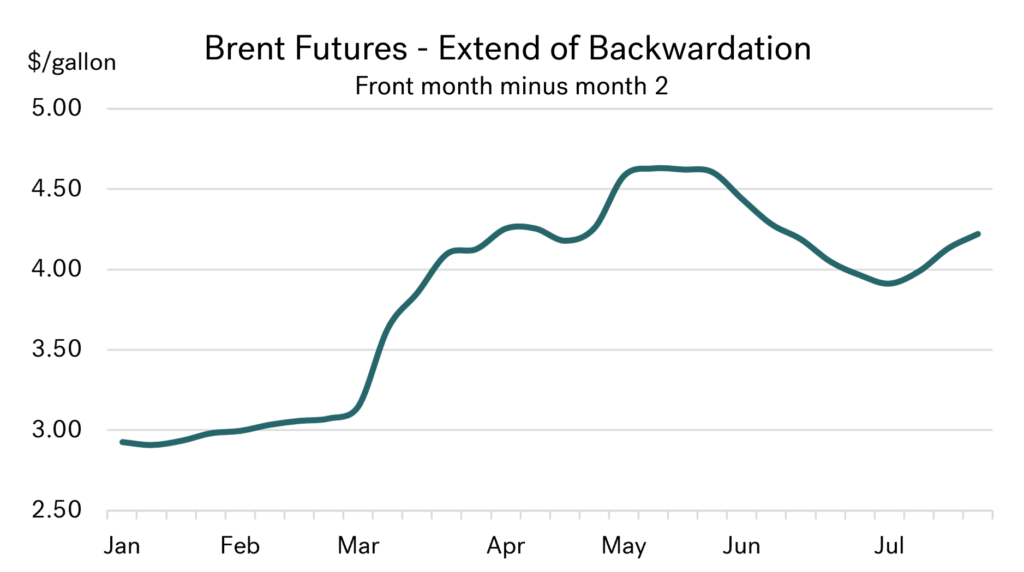
The halt in attacks over the past weekend has taken steam out of the market, with prices and backwardation falling sharply. Where we go from here depends if there is again a belief peace is on the horizon, or if this is another false dawn. The past month highlights how impossible it is to predict an ending to the war, and how fragile any expectations of peace can be.
We cannot ignore the price, but still must look to the future
It is impossible to write a report and not highlight the turmoil of the current market and what is happening. However, we still must look beyond this, to see where we could end up.
In an earlier report, we suggested the run-up to the US mid-term elections in November may be a backstop to the war. However, even this is not guaranteed. There are many dynamic elements to the economy and voter intentions, but one feature that will always crop up in the US is the gasoline price. This has risen from $3/gallon before the war to over $4/gallon for the past four months.
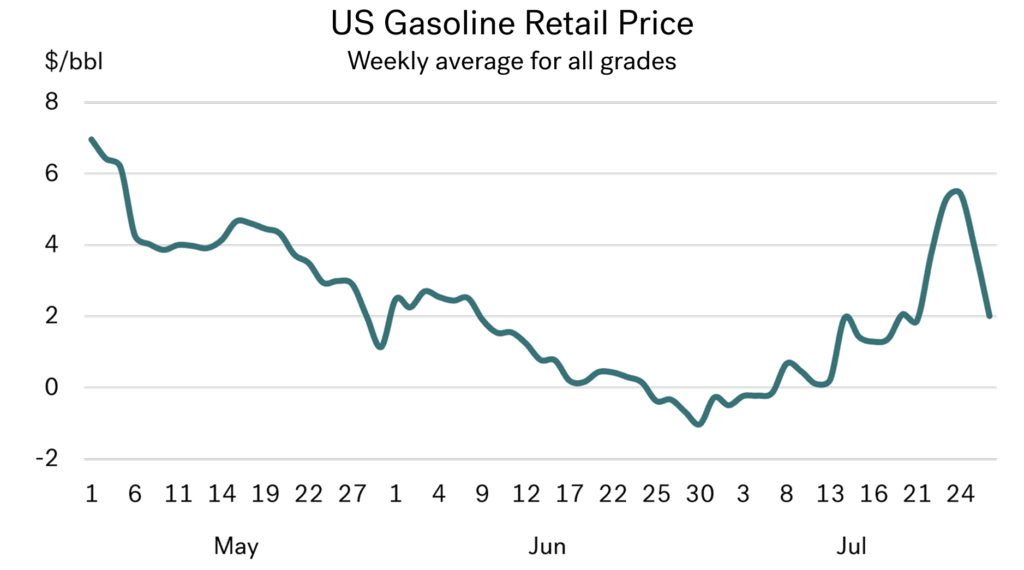
If it comes to it, will Republican voters want to see a resolution to the war and a return to $3 gasoline prices ahead of the elections?
We have a change of heart on how low bunker prices can go
We don’t know exact timings, but in any planning, we must look at what happens when the war does finally end and prices fall, whenever that may be. In past reports we have highlighted the view that Brent crude prices are unlikely to fall back to pre-war levels in the $60s, and Singapore VLSFO unlikely to go back in to the $400s. This may be the point at which these views change.
Previous thinking was based on a relatively short war, where there would be a large loss of oil supply and a massive stock-draw. In this case, tighter stock levels would be sufficient to keep prices higher than their pre-war levels once we returned to ‘normality’. This would mean Brent futures in the $70s (and not in the $60s), and Singapore VLSFO in the $500s, and not the $400s.
A number of mainstream analysts also held this view, although there were some that were lower and some higher.
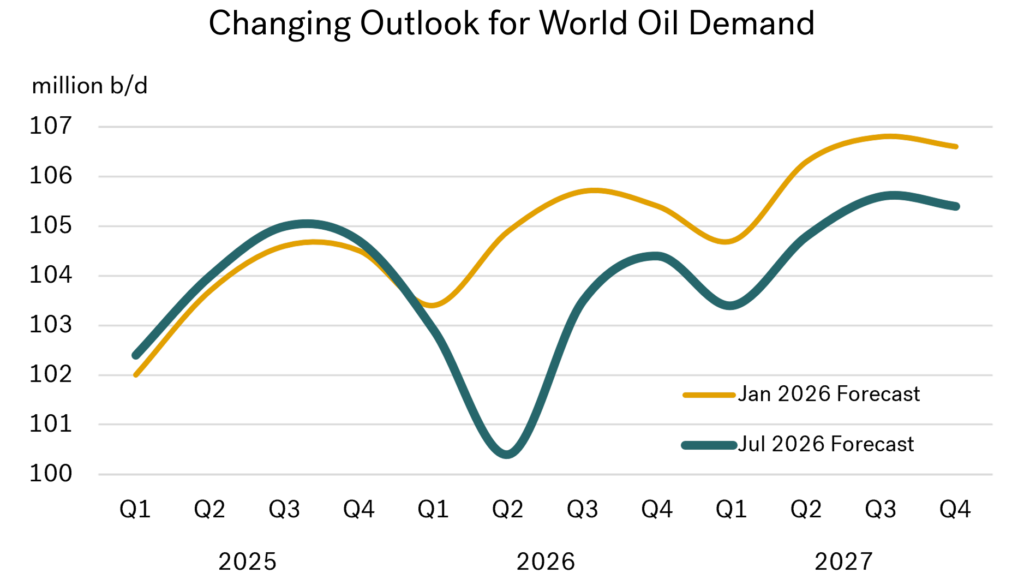
Given the war has already gone on for much longer than almost everyone expected, this thinking must change. Yes, global stocks have been drawn down at a rapid rate, but this is slowing. Higher pricing and inflationary blows have had a major impact on global oil demand, with current indications that total oil demand in the second quarter of this year was some 4 million b/d lower than year earlier levels.
The graph below shows this sharp drop in demand and even if the war comes to an end relatively soon, and demand gets back towards some normality, a structural loss of more than 1 million b/d in global oil demand is still expected to have taken place because of the extended period of conflict.
If the war goes on for even longer, structural losses in global oil demand are likely to be even greater.
Source: US EIA
It’s a hard road, but we can get there
This means that once the war does end, market psychology will be looking at a rapid increase in oil supplies going into a global market which is much lower in demand. This opens the way for prices to easily return to their pre-war levels of Brent in the $60s and Singapore VLSFO in the $400s.
Now we just need those at the centre of negotiations to get us there.
Photo credit and source: Integr8 Fuels
Published: 30 July, 2026
Methanol
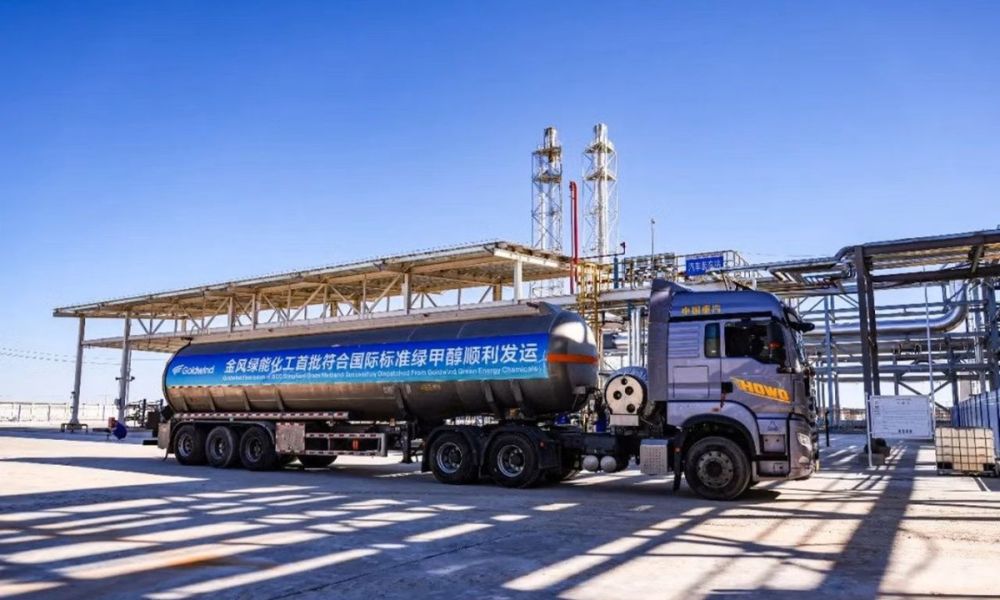
Goldwind green methanol facility completes trial production, ships first 500 mt
Goldwind has also secured long-term offtake agreements with A.P. Moller – Maersk and Hapag-Lloyd, connecting planned production with demand from shipping.
LNG Bunkering
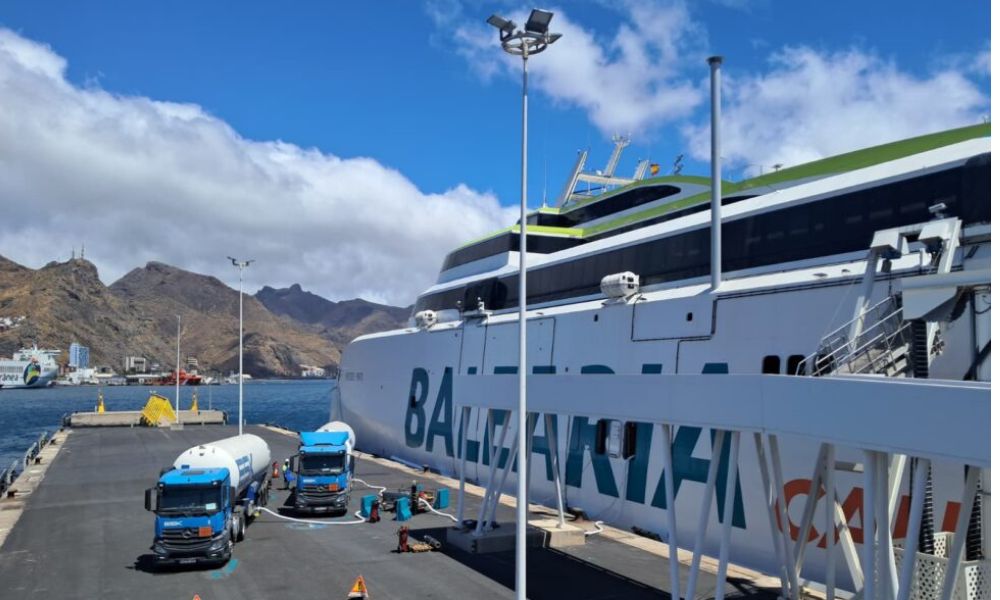
Tenerife achieves first truck-to-ship LNG bunkering operation
With the latest operation, the Port of Santa Cruz de Tenerife is now capable of truck-to-ship and multi truck-to-ship bunkering operations, in addition to the ship-to-ship method.
Ammonia
IMO technical seminar to focus on ammonia production, bunkering and safety
IMO announced its Future Fuels and Technology Project is organising a Technical Seminar on the use of ammonia as marine fuel on 17 September.

OUR INDUSTRY PARTNERS

APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists

APPEC 2026: Panellists navigate maritime decarbonisation and alternative marine fuel strategies

High Court of Singapore issues winding up order against Hengli Petrochemical International

Goldwind green methanol facility completes trial production, ships first 500 mt

LDA’s methanol-powered “Spirit of Toulouse” gets Norsepower rotor sail in Shanghai

Tenerife achieves first truck-to-ship LNG bunkering operation

IMO technical seminar to focus on ammonia production, bunkering and safety

Rajah & Tann: Bunker disputes are won in the first 48 hours

Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor

Singapore strengthens LNG bunkering framework with new SS 727 standard

Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean

Ahti Climate and DNV connect verified emissions data to FuelEU pooling platform

TFG Marine advances global MFM rollout with two US Gulf bunker barges

Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
-
 Bunker Claim2 weeks ago
Rajah & Tann: Bunker disputes are won in the first 48 hours
-
 Vessel Arrest2 weeks ago
Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor
-
 LNG Bunkering2 weeks ago
Singapore strengthens LNG bunkering framework with new SS 727 standard
-
 Alternative Fuels2 weeks ago
Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean
-
 FuelEU2 weeks ago
Ahti Climate and DNV connect verified emissions data to FuelEU pooling platform
-
 Mass Flowmeter2 weeks ago
TFG Marine advances global MFM rollout with two US Gulf bunker barges
-
 Alternative Fuels1 week ago
Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
-
 Incident5 days ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”