Connect with us

Interview

Interview: Cargill Ocean Transportation shares digital and decarbonisation roadmap

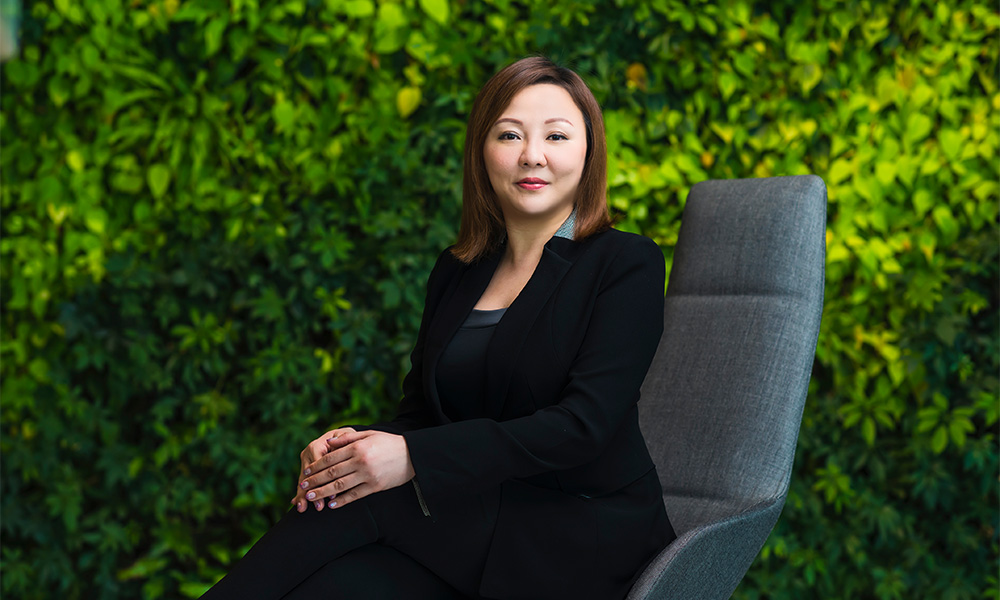
Ying Ying Lim, Vice President of Cargill Ocean Transportation APAC, shares how data, AI and partnerships are driving digitalisation and decarbonisation for Cargill.

Admin

Published

on

Interview: Cargill Ocean Transportation shares digital and decarbonisation roadmap

In this Manifold Times interview, Ying Ying Lim, Vice President of Cargill Ocean Transportation APAC, discusses how Cargill is using digitalisation—grounded in data, analytics and AI—to improve freight execution and strengthen bunker procurement decisions.

She also shares why a fuel- and technology-agnostic approach, including real-world trials such as green methanol bunkering in Singapore, and collaboration across the maritime value chain are key to scaling decarbonisation while maintaining operational performance.

MT: What is the state of Cargill’s digital transformation for its maritime segment?

Digitalization, data and AI are core enablers of how we run and evolve our ocean transportation business.

We have made deliberate investments to build strong digital foundations, starting with data and analytics that directly improve decision-making, operational efficiency and decarbonization outcomes. This includes our early involvement in ZeroNorth, which applies AI to optimize freight routing and reduce fuel consumption and emissions.

That foundation supports more efficient freight execution, better commercial decisions and a more consistent customer experience, complemented by partnerships with leading maritime technology providers such as Veson.

More recently, we developed a Data Cloud for Cargill Ocean Transportation as a shared data backbone across our shipping activities, and we have begun scaling the use of generative AI across selected processes. We see this as a long-term capability build that requires discipline and sustained commitment, but one that is essential to managing complexity and delivering value at scale.

MT: How has Cargill benefitted from digitalization of its shipping operations?

Digitalization has helped us improve efficiency and cost discipline across our shipping operations, with the level of impact varying depending on the initial situation and objectives of each process.

In freight execution, we use digital tools to support route optimization, vessel vetting, ship chartering, freight handling and market forecast. Depending on the process and starting point, we have been able to partially or fully automate activities, always with a clear focus on delivering a positive return on investment.

While parts of the dry cargo market still rely on semi‑automated processes and inconsistent standards, advances in generative AI are giving us greater flexibility. For example, AI can help structure and make usable unstandardized inputs such as emails and documents, reducing manual effort and dependence on traditional technology vendors. This allows us to lower costs, improve efficiency and instill resilience in our operations.

MT: Has Cargill incorporated digitalization into its bunkering and marine fuel procurement operations? Were there challenges to overcome and what were the solutions?

Cargill executes its marine fuel procurement through Seascale Energy, a Cargill and Hafnia joint venture. By leveraging combined purchasing power and market influence, Seascale brings greater transparency, reliability and efficiency to bunker procurement, supporting improved commercial outcomes.

Data and digital decision making tools play an important role in this process. As with many parts of the maritime value chain, bunker procurement has historically relied on fragmented data and manual processes. Digital tools help bring greater transparency and comparability to purchasing decisions, supporting more consistent outcomes while maintaining the flexibility needed to operate across different markets and suppliers.

One challenge is limited transparency around delivered quantity and fuel quality. This can make like-for-like comparisons more difficult and increase the risk of disputes. Cargill is one of the founding participants in the Bunkering Services Initiative, which commenced operations in the Amsterdam–Rotterdam–Antwerp (ARA) region. The initiative combines certified hardware, real-time data capture and independent assurance across bunker deliveries to improve transparency, traceability and accountability.

Another challenge is that bunker procurement has often been assessed primarily on price, even though outcomes can be materially affected by factors such as claims performance, counterparty reliability, quantity discrepancies and more. Through Seascale, we’re supporting the continued development and commercial rollout of Studio 30 50’s Fuelsure platform to evaluate procurement decisions based on total commercial outcomes, not just nominal cost.

MT: What is Cargill’s view on the use of electronic bunker delivery notes (e-BDN) in Singapore? Does the company have plans to introduce e-BDN operations for its vessels around the world? 

Singapore has become the first port globally to mandate electronic bunker delivery notes as the default for all bunker suppliers, setting an important precedent for the industry.

One of the key advantages of e‑BDNs is the use of a standardized and consistent format, which makes it easier for stakeholders to verify information and reduces the risk of discrepancies or errors in the bunkering process.

More broadly, the adoption of e‑BDNs is largely driven by regulation. Where electronic bunker delivery notes are mandated by governments or governing bodies, Cargill will support their implementation accordingly.

MT: Does Cargill have a preferred type of alternative marine fuel which it wants to use for its vessels?

At Cargill, we are deliberately fuel and technology agnostic as we navigate the energy transition. What matters most is using the solution that is best suited to the vessel, the trade and the operating environment at any given time.

We anticipate a multifuel future. Some vessels will continue to operate on conventional fuels, others will use drop-in biofuels, and over time we anticipate more advanced fuels to play a role as availability and infrastructure develop. At Seascale we are exploring LNG and Bio-LNG procurement, and for our own fleet we’re experimenting with green methanol and exploring the possibility of other green fuels, such as ethanol.

Today, the strongest business cases we see are around fuel efficiency and biofuels. At the same time, we are investing in optionality. The methanol vessels are designed to perform efficiently on conventional fuel now, while giving us the flexibility to transition to lower-carbon fuels as their supply chain becomes viable. This approach allows us to make progress today while remaining adaptable for the future.

MT: What is Cargill’s decarbonization strategy and how can Singapore as a multi-fuel bunkering hub help fulfil this ambition?

To complement our fuel and technology-agnostic approach, we continue to explore more ambitious ways to reduce carbon intensity over time. You have seen this through initiatives such as wind assisted propulsion and the introduction of multifuel vessels.

A recent example was Cargill’s first ever bunkering of green methanol in Singapore. This was an important technical experiment, carried out jointly with Singapore based partners and the Maritime Port Authority of Singapore, and it was a positive learning experience.

Technologies such as green methanol or wind assisted propulsion still come with uncertainty. However, as an industry leader, we believe it is important to test these innovations in real operating conditions, share what we learn, and help support the systems and standards needed for wider adoption.

By operating a fleet of multi-fuel and fuel-ready vessels, we are able to experiment with new fuels today and ensure we are ready to progress as these solutions become more viable. Singapore’s role as a multifuel bunkering hub is an important enabler of this approach.

MT: Does digitalization and decarbonization complement each other?

Absolutely! Digitalization can be used to support better fuel efficiency. If we have a clearer understanding of how a vessel performs under different conditions, we can optimize its operations to reduce fuel consumption.

The savings on a per vessel basis may not be dramatic, but these improvements can be applied across fleets of different ages and market segments. When scaled, they add up. For that reason, it is worth doing.

MT: What are your predictions around the demands of maritime shipping in 2030?

Looking ahead to 2030, it is helpful to distinguish between what is most likely to be deployed at scale and what remains more aspirational.

From a practical perspective, we expect biofuels and LNG to account for a significant share of fuel use, as these options are already available today and can be applied across a wide range of vessels and trades. Methanol and ethanol are also expected to play a growing role, but their uptake will depend on fuel availability, infrastructure development and effective regulation.

From an ambition standpoint, our focus at Cargill is on continuing to reduce the carbon intensity of ocean transport for our customers. Within Cargill Ocean Transportation, we have a 2030 ambition to reduce Scope 3 emissions by 30 percent per ton of product sold, compared to a 2017 baseline, measured through improvements in our Energy Efficiency Operational Indicator. As of 2024, we have reported progress of 12 percent toward that target.

Achieving further reductions by 2030 will depend not only on fuel choices, but also on efficiency improvements, vessel design, digital optimization and a regulatory environment that supports the scaling of lower-carbon solutions. Digitalization, and AI in particular, will be essential in managing the added complexity that decarbonization brings, from emissions reporting and regulation to multiple propulsion technologies.

Related: Cargill’s first green methanol dual-fuel dry bulk vessel to bunker in Singapore


Photo credit: Cargill
Published: 30 April 2026

Continue Reading

Interview

China’s bunker market reshaped by tax rebates, trade flows and refining changes, says economist

Dr Kang Wu discusses how China’s bunker fuel tax rebate, shifting refinery output, import flows and alternative fuel adoption are reshaping the country’s marine fuels market and its competitive position.
Admin

Published

on

By

Dr Kang Wu

China’s growing role in the marine fuels market is reshaping the competitive dynamics between Chinese bunkering hubs and established centres such as Singapore.

 In this interview with Manifold Times, Dr Kang Wu, Energy Economist specialising in China and Southeast Asia at Global Energy Research and Educational Training Pte. Ltd., discusses the impact of China’s bonded bunker fuel tax rebate, domestic refining and import trends, the adoption of LNG and methanol, and pricing differentials with Singapore, while also examining China’s surplus of UCOME:

MT: How has China’s 2020 VAT rebate policy for bonded bunker fuel, especially for low-sulphur fuel oil, affected the competitiveness of Chinese ports like Zhoushan in comparison to traditional hubs like Singapore?

The impact has been significant, mainly because the rebate extends beyond the VAT. Effective February 2020, the Chinese government introduced a rebate policy for the 13% VAT on China’s fuel oil exports (including bunker fuels) to bonded areas. More importantly, the rebate also covers the fuel oil consumption tax, which amounts to 1,218 yuan per metric tonne (mt), or roughly $27/bbl. This policy has fundamentally transformed the economics of China’s fuel oil exports to bonded areas. However, as discussed below, China still needs to import large volumes of bunker fuel because domestic supply remains insufficient to meet demand

MT: With China’s independent refiners (teapots) now producing more compliant low-sulphur fuel oil, what share of China’s bonded bunker demand is now met domestically vs. imported from places like  Malaysia or Russia?

Although independent (“teapot”) refiners cannot export bunker fuels directly as they do not have export quotas, their increased production helps quota-holding national oil companies (NOCs) as well as Zhejiang Petroleum & Chemical Co., Ltd. expand their exports. However, it is worth noting that China’s overall fuel oil production has been declining in recent years because refiners increasingly use deep conversion processes to maximise the production of lighter products and petrochemical feedstocks. In 2025, China exported a record 376,000 b/d of fuel oil, the vast majority of which was shipped to bonded areas. At the same time, China imported 396,000 b/d of fuel oil, primarily from Russia, Malaysia and Singapore, down from the record 514,000 b/d imported in 2024. These imports and exports together form the foundation of China’s bonded-area fuel oil market.

MT: Given China’s push for LNG bunkering and its IMO 2030/2050 decarbonisation targets, how quickly are Chinese ports and shipowners adopting LNG or methanol bunker infrastructure compared to conventional VLSFO?

Indeed, China has made a major push to promote LNG and green methanol as marine bunker fuels, and progress has been steady. However, given the relatively low starting base, their rising impact on VLSFO consumption is expected to be gradual.

MT: How do fluctuations in China’s industrial production and coal imports (via dry bulk carriers) directly correlate with bonded bunker fuel demand at major Chinese ports?

Bonded bunker fuel demand at major Chinese ports is indeed influenced by China’s overall import and export activities. Although China’s coal imports have declined since reaching a record high of 543 million mt in 2024, the country’s total merchandise trade volume has continued to grow year by year. At the same time, China’s GDP growth has slowed compared with a decade ago. In addition, structural changes in trade patterns and shipping routes (such as a decline of exports to the US and a surge of exports to other countries) have also affected bunker fuel demand. A more detailed analysis is needed to determine the precise relationship between trade activity and bonded bunker fuel demand.

MT: What is the typical price spread between Chinese bonded bunker fuel and Singapore’s delivered bunker prices, and how do factors like China’s export quotas or refinery maintenance create arbitrage opportunities?

Following the introduction of the tax rebate policy discussed above, Chinese ports have gained a pricing advantage in the bunker fuel market, as more competitively priced bunker fuel produced domestically has become available. As a result, China’s delivered bunker fuel prices have typically traded at a discount of $15–30/mt to those in Singapore. However, prices fluctuate, and China’s bonded bunker fuel prices are not always lower than Singapore’s for three main reasons. First, China still needs to import large volumes of fuel oil, including VLSFO, into its bonded areas. Consequently, prices in these markets remain closely linked to Singapore’s delivered bunker prices. Second, the volume and timing of export quota allocations to the NOCs play an important role in determining the availability of domestically produced bunker fuel in bonded areas. At times, limited quota availability can tighten supply, resulting in shortages at China’s bonded ports. Third, during periods of geopolitical or market disruption, such as the Iran conflict since February 2026, market fundamentals can change rapidly, leading to heightened price volatility.  The bottom line is that, regardless of the absolute price spread between China and Singapore, fluctuations in the spread and China’s need to import bunker fuels continue to create arbitrage opportunities for traders.

MT: Anti-dumping duties and policies introduced by the European Commission and western regulators have resulted in overcapacity of UCOME in China; given the material cannot obtain ISCC EU certification to be blended as bio-bunker fuel (i.e. EU ETS, carbon credits), what will be your advice to Chinese holders of excess UCOME?

Like many other renewable energy products (such as solar panels) and electric vehicles, China’s UCOME industry has expanded rapidly and now faces growing trade barriers in Western markets because of its strong export growth. While there are no easy solutions for producers with excess capacity, several strategies could help.  First, producers should continue improving efficiency and reducing costs to remain competitive despite the import duties and other trade measures imposed by the EU and some other developed economies. Second, they should diversify export markets beyond the EU by targeting emerging opportunities in advanced economies such as Singapore. In particular, Singapore could leverage China’s surplus UCOME supply to accelerate the development of its sustainable aviation fuel (SAF) and bio-bunkering industries. Finally, China’s UCOME industry could encourage the Chinese government to expand domestic blending mandates, including greater use of SAF and bio-bunkering fuels, to stimulate domestic demand and help absorb excess production.

Dr Wu will be leading a two-day executive briefing, China Oil Market Dynamics, held on 26 to 27 October in Singapore. The intensive briefing will provide a comprehensive outlook on China’s oil market through 2035, covering the key market, policy, economic and structural forces shaping its future. More information on the event and registration can be found here.


Photo credit: Kang Wu
Published: 28 August, 2026

Continue Reading

Bunker Fuel

NW Corporation expands Malaysia bunkering fleet with acquisition of “BELLAA 1”

The company’s immediate growth strategy remains focused on Port Klang, where it continues to strengthen its market presence and provide comprehensive bunkering solutions for its customers.
Admin

Published

on

By

NW Corporation expands Malaysia bunkering fleet with acquisition of “BELLAA 1”

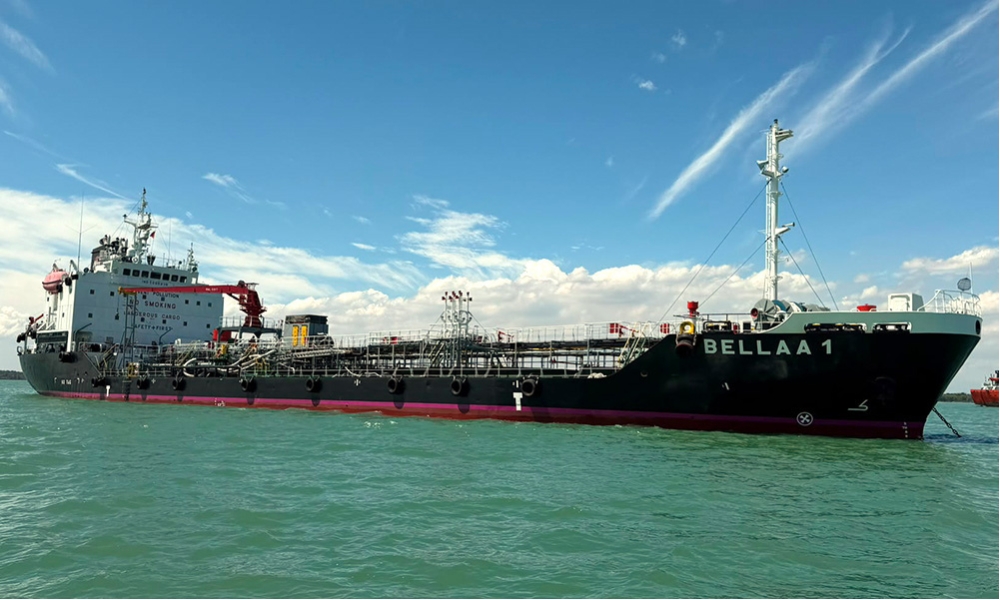
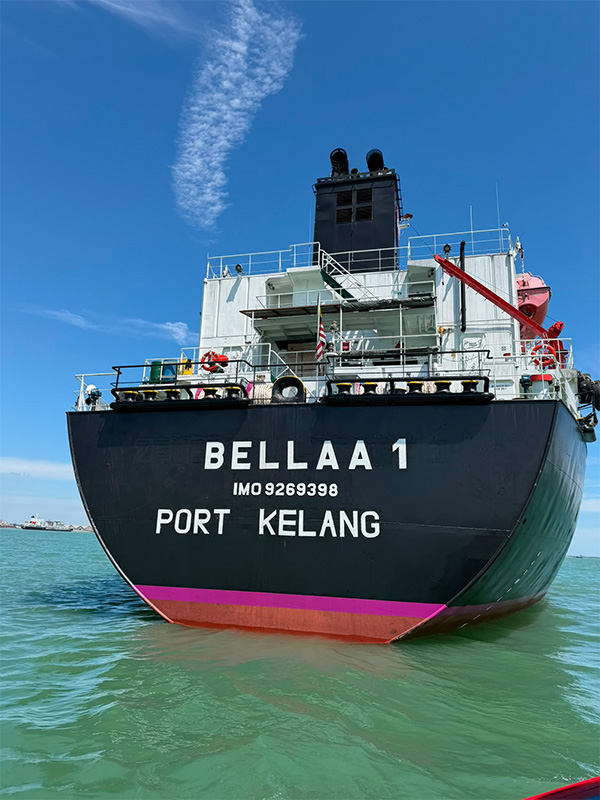
Singapore-based commodities and oil cargo trading firm NW Corporation Pte Ltd (NWC) has expanded its Malaysia bunkering operations through the acquisition of Bellaa 1 (IMO 9269398), increasing its monthly bunker supply capability to approximately 30,000-35,000 mt.

Bellaa 1 is a Malaysia-flagged bunker tanker with a loadable cargo capacity of approximately 5,000-5,500 mt of Low Sulphur Fuel Oil (LSFO),” Jason Tan, Co-founder and Head of Commercial of NWC, told Manifold Times on Tuesday (14 July).

“The addition of Bellaa 1 represents another important milestone in our fleet expansion strategy. It strengthens our operational capability, improves supply flexibility and enables us to better support the increasing demand for LSFO in Port Klang.”

Following the acquisition, the bunker tanker underwent an intermediate survey, was renamed in Singapore and is scheduled to commence commercial bunkering operations from August 2026.

According to Mr Tan, the acquisition will expand NWC’s LSFO supply capability, improve operational flexibility, increase vessel availability, enhance service reliability and support continued growth in bunker sales at Port Klang.

“NWC commenced bunkering operations at Port Klang in April 2024 with a single bunker barge and an initial monthly supply volume of approximately 10,000 mt,” said Mr Tan.

“The introduction of Bellaa 1 will increase our monthly bunker supply volume from approximately 20,000 mt to around 30,000-35,000 mt, driven by continued growth in bunker demand at Port Klang.”
Bellaa 1 back MT

Since entering the Port Klang market in 2024, NWC has steadily expanded its bunkering operations in tandem with growing customer demand. The latest fleet addition reflects the company’s continued investment in strengthening its supply capability and operational reliability.

Moving forward, Mr Tan pointed out NWC’s immediate growth strategy remains focused on Port Klang, where the company continues to strengthen its market presence and provide comprehensive bunkering solutions for its customers.

“Our immediate priority remains Port Klang, where we continue to see strong opportunities for growth. We will keep investing in fleet capability, operational efficiency and customer service while strengthening our trading activities and bunker supply network,” he stated.

“With a growing fleet, experienced operational team and strong partnerships with major bunker traders and suppliers, we are well positioned to expand our market share and reinforce our position as a trusted bunker supplier in the region.”

About NW Corporation

NW Corporation Pte Ltd is a Singapore-headquartered commodities and energy trading company engaged in oil cargo trading, bunkering, marine logistics and energy infrastructure investments across Asia. The company has been expanding its bunkering footprint in Port Klang as part of its long-term regional growth strategy.

Related: Singapore: NW Corporation welcomes “Fortune Glory” after three-week drydocking ops
Related: NW Corporation strengthens Port Klang operations with newly acquired bunker tankers


Photo credit: NW Corporation Pte Ltd
Published: 12 August, 2026

Continue Reading

Interview

Exclusive: Caroline Yang takes helm on future of IBIA Asia

The newly appointed Chair of IBIA’s Regional Board – Asia, shares her plans to strengthen bunkering standards while promoting transparency and industry collaboration across key Asian maritime hubs.
Admin

Published

on

By

Exclusive: Caroline Yang takes helm on future of IBIA Asia

Caroline Yang, CEO of Hong Lam Marine Pte Ltd, outlines her plans for IBIA Asia in her first interview with Manifold Times since becoming Chair of the Regional Board – Asia:

MT: Why is IBIA important to the bunkering market in Asia?

IBIA Asia is amongst five regional boards operating under the umbrella of London-based IBIA Global. Its presence in Asia is vital because the region, excluding the Middle East, accounts for more than 50% of global bunkering volume.

While Singapore continues to maintain its strong lead as the world’s busiest bunkering port with almost 56 million mt of marine fuel delivered in 2025, several ports in China are showing to be strong bunkering ports as well; these developments take place on the back of a forecast for China to be amongst the leading suppliers of green fuels such as methanol.

Based on this alone, IBIA Asia has to play an important role in raising and addressing issues of suppliers and shipowners and the other parties in the regional bunkering eco-system.

MT: What is the overall state of bunkering standards at major Asian ports and how can IBIA elevate this?

Singapore is the clear leader in standards, acting as a “flag bearer” with established protocols including SS 600 for bunkering, SS 648 for bunker mass flow metering, SS 524 for quality management of bunker supply chain, TR 56 for LNG bunkering, and TR 80 for meter verification using master MFM.

While other Asian ports are adopting mass flow meters – a positive step – IBIA Asia’s role is to disseminate these best practices while maintaining deep respect for local operational realities and regulatory environments.

MT: As Chair of the Regional Board – Asia, what are your plans to make this happen? Are there any topics you will be focusing on?

The IBIA Asia regional board of 10 members from comes from a diverse group of suppliers, shipowners, bunker buyers, fuels testers and bunker tanker owners. Backed by a strong secretariat, we are committed to move the needle for bunkering in Asia.

Our initial strategy is outreach-driven, progressing beyond a Singapore-centric approach. For starters, the board will be concentrating on Hong Kong, Zhoushan, and Shanghai, with potential expansion to Japan and South Korea.

The core objective is to promote the quality, transparency, and integrity of bunkers lifted in Asia. This includes building on existing MOUs such as the collaboration with Hong Kong Shipowners Association (HKSOA) to explore alternative bunker fuels, and participation in regional maritime week programmes.

MT: Do you expect to encounter any challenges? What do you think are the solutions?

Challenges, without a doubt; these include macro-level standards and topical quality issues, such as those highlighted in a recent FOBAS report.

We are aware most solutions will not have instant results, but produce short-term, mid-term and long-term responses.

The solution lies in structured communication and feedback loops involving industry, regulators, and experts. Success requires an altruistic approach where stakeholders prioritise the health of the bunkering ecosystem to achieve win-win outcomes, even at the compromise of individual sectors.

MT: Is participation of local/regional IBIA members included within your plan? How will they be involved?

Member participation is the foundation of an association’s strength. The plan involves active outreach – meeting members where they operate and integrating them into meetings to ensure the board’s positions reflect representative industry views. We must push out credible, strong messages to encourage active engagement. If there is anyone in the maritime bunkering in these areas and reading this interview, reach out to us so we can start our conversations!

The Secretariat and some board members have scheduled to visit and attend bunkering events in Hong Kong and China. In November 2026, IBIA will participate in the Hong Kong Maritime Week by organising a one-day conference. We hope to be also participating in the Shanghai Pudong Maritime Conference and the 9th International Petroleum and Natural Gas Enterprises Conference (IPEC 2026), also known as the “Zhoushan Bunker Oil conference”, in late October.

MT: How will previous experience gained at SSA, ICS, MPA, SMF, and Hong Lam Marine contribute to your role at IBIA?

As CEO of Hong Lam Marine, our bunker tankers supply about 10% of bunkering volume in Singapore, so we are an involved and relevant stakeholder. My experiences in the above-mentioned organisations have taught me how to crystallise and articulate important issues, engage effectively with diverse stakeholders, and leverage on pre-existing professional connections to engage more effectively for IBIA Asia.

Related: IBIA announces Caroline Yang as new Regional Board Chair for Asia
Related: IBIA and Hong Kong Shipowners Association to collaborate on alternative bunker fuels
Related: FOBAS report warns of growing operational risks from ISO-compliant bunker fuels


Photo credit: Manifold Times
Published: 6 August 2026

Continue Reading

Trending