Methanol
GENA Solutions: Total renewable and low-carbon methanol project pipeline rises from 59.6 to 61 Mt by 2031
Information shared by the Methanol Institute meant to assist the maritime industry in the adoption of methanol as a mainstream marine fuel heading into IMO 2030/2050.

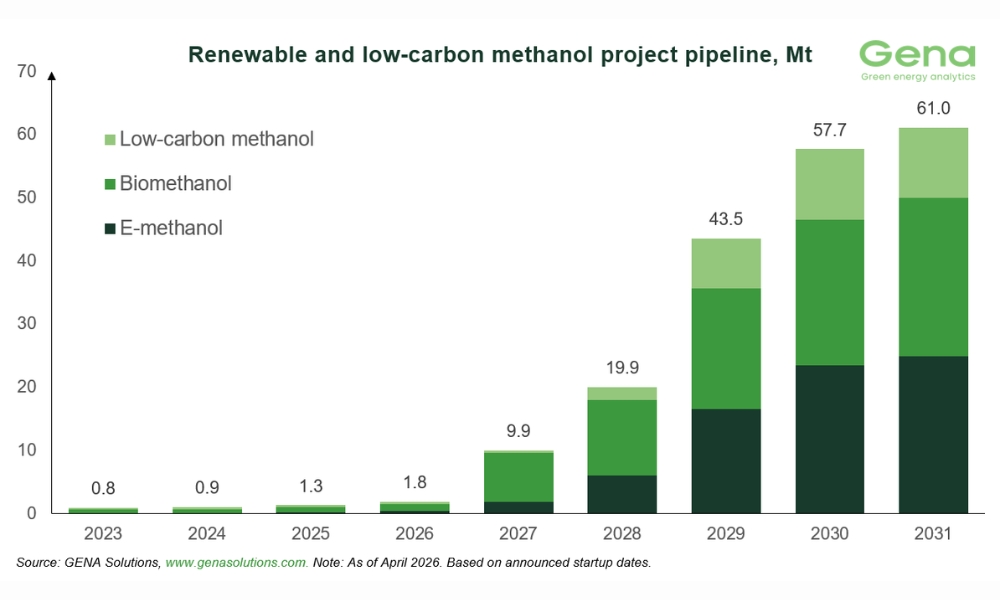
The Methanol Institute recently shared with Manifold Times the renewable and low-carbon methanol project pipeline April 2026 release produced by GENA Solutions Oy.
Information from the release is meant to provide the bunkering publication’s readers with insight on renewable methanol availability, and to assist the maritime industry in the adoption of methanol as a mainstream marine fuel heading into IMO 2030/2050.
Key highlights from GENA’s April 2026 Methanol release are as follows:
- Six renewable methanol projects in China, with a total capacity of 1.9 Mt, held groundbreaking ceremonies over the past month. However, our analysis shows that three of them are not ready to start construction soon.
- Eight new projects were added to Project Navigator, while eight frozen projects were excluded. Due to the larger average capacity of the new projects, the project pipeline increased by 1.4 Mt month on month.
- As of the end of April 2026, Project Navigator tracks 281 renewable and low-carbon methanol projects, representing 61 Mt of capacity by 2031, including 24.9 Mt of e-methanol, 25 Mt of biomethanol, and 11.2 Mt of low-carbon methanol.
- China and Europe are the most active centers globally for renewable methanol industry development, together accounting for about 82% of the project pipeline. China accounts for about 30 Mt, while Europe accounts for 11 Mt.
- In the medium-term perspective, renewable methanol capacity could grow from 0.9 Mt in 2025 to about 1.5 Mt in 2026 and 2.2–2.4 Mt in 2027.
- In the longer-term perspective, considering project development progress and possible market development scenarios, GENA estimates that global renewable methanol capacity could range from 5 Mt to 12 Mt by 2030.
Note: The full article can be viewed here.
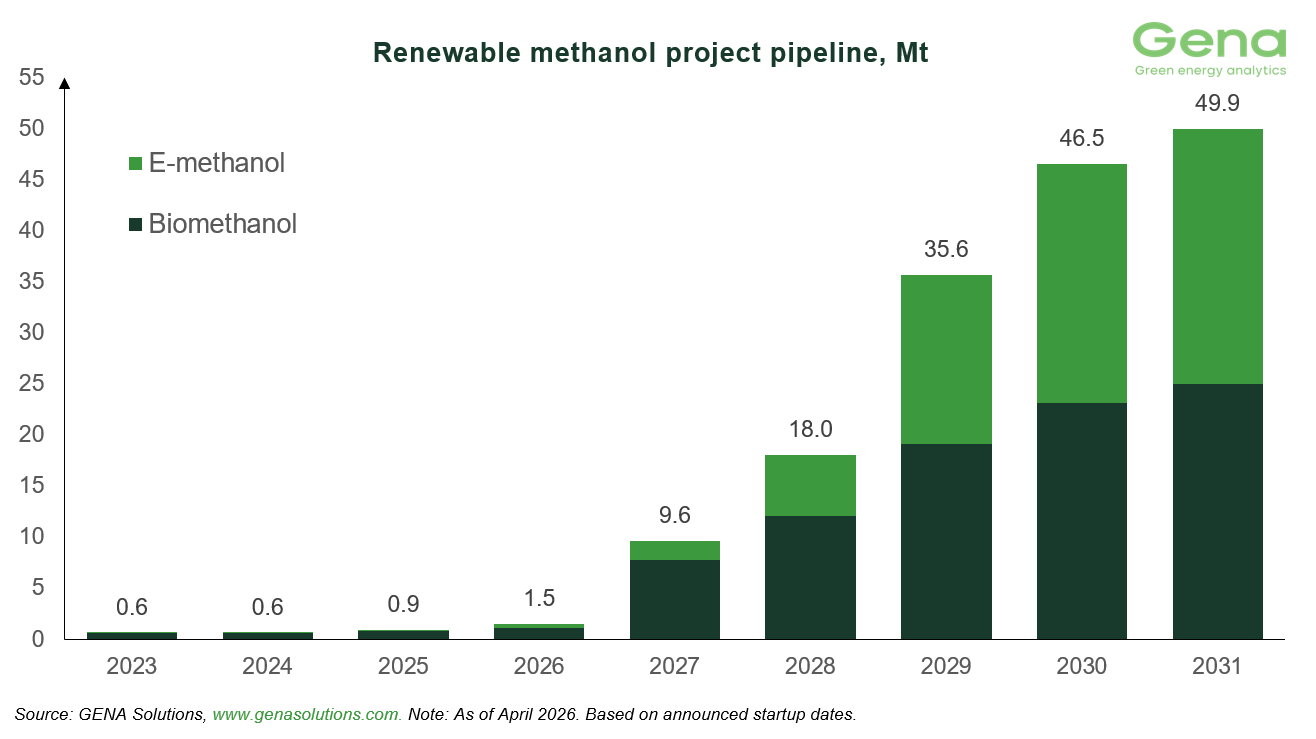
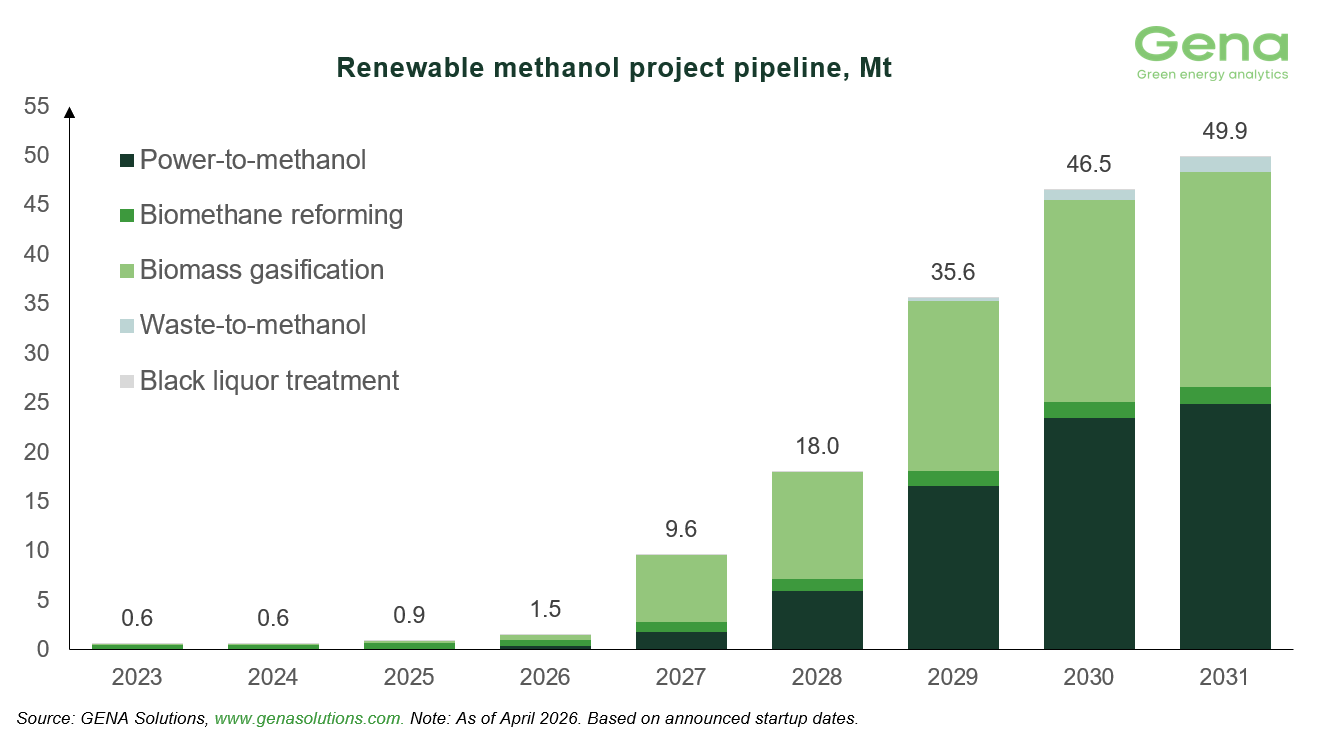
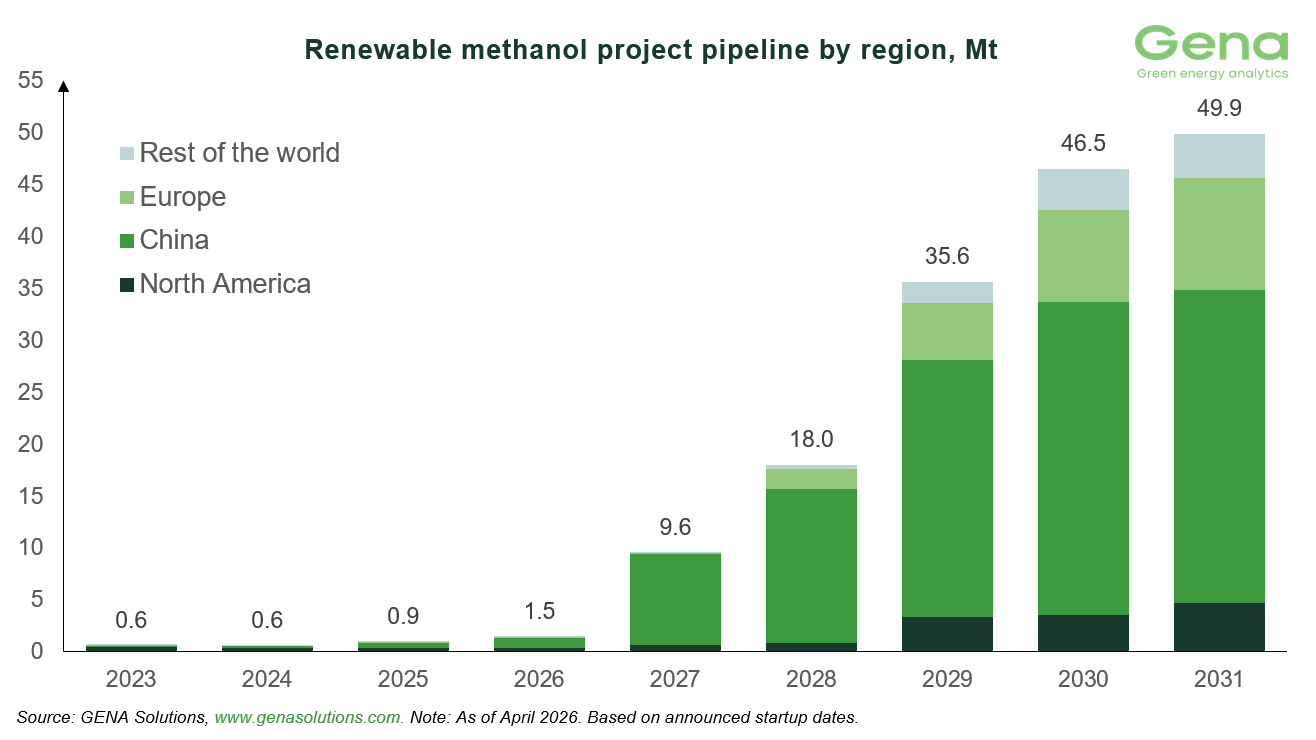
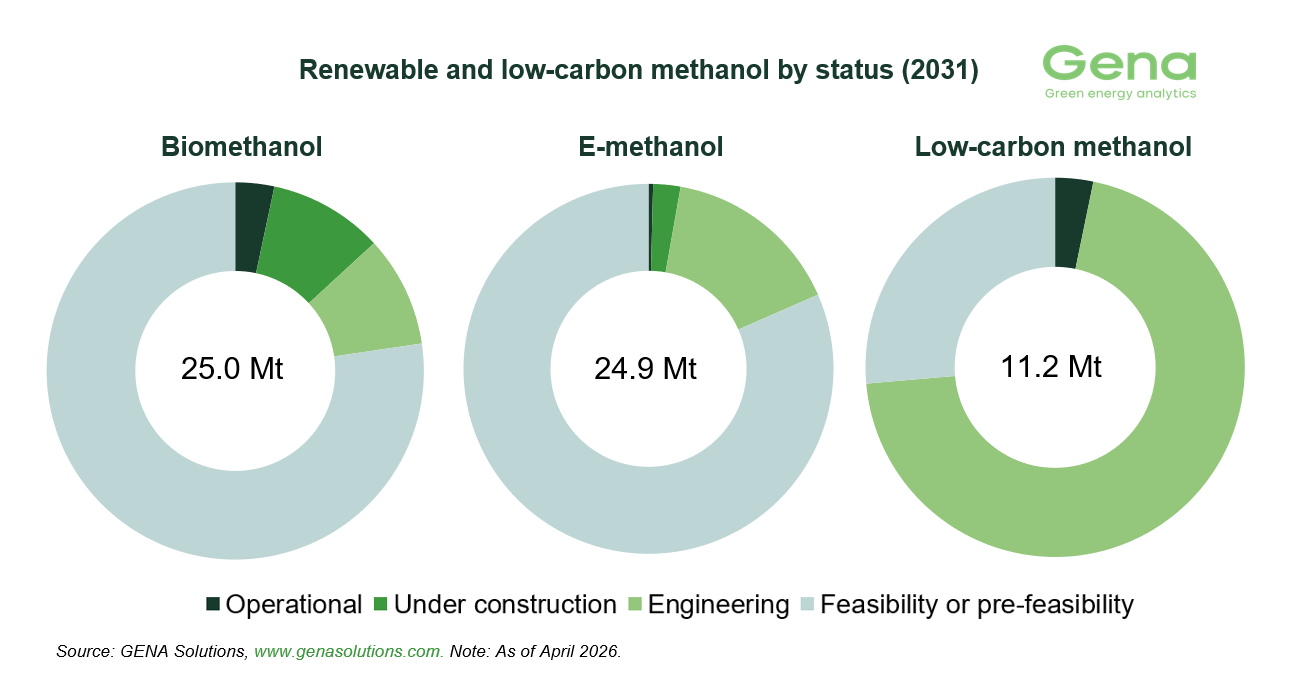
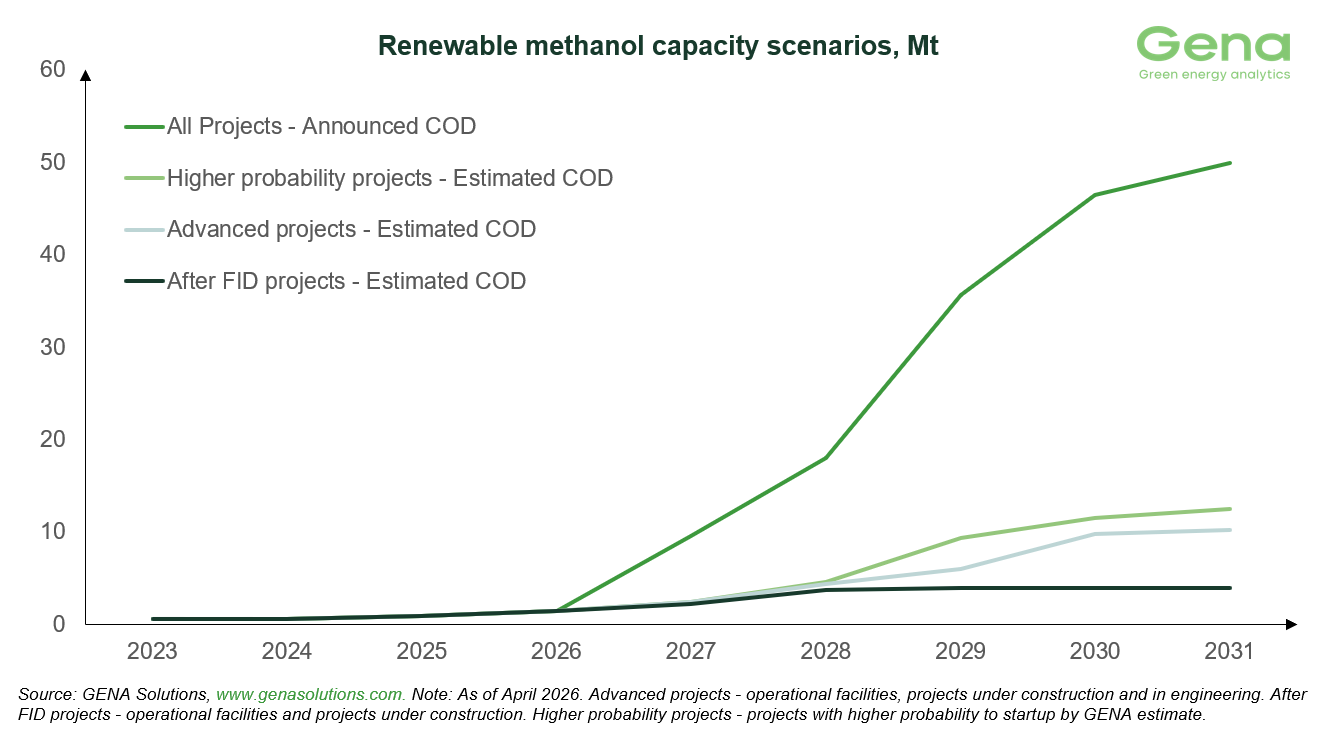
Photo credit: GENA Solutions
Published: 4 May, 2026
Alternative Fuels
DNV: How ethanol is expanding shipping’s fuel choices
DNV examines why interest in ethanol is growing, drawing on insights from cargo owners, engine manufacturers, and other industry stakeholders.
Alternative Fuels
GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050
New fuels could reach around 60% of fleet energy consumption under a sufficiently strong carbon price signal, modelled at USD 700/tCO2e by 2050.
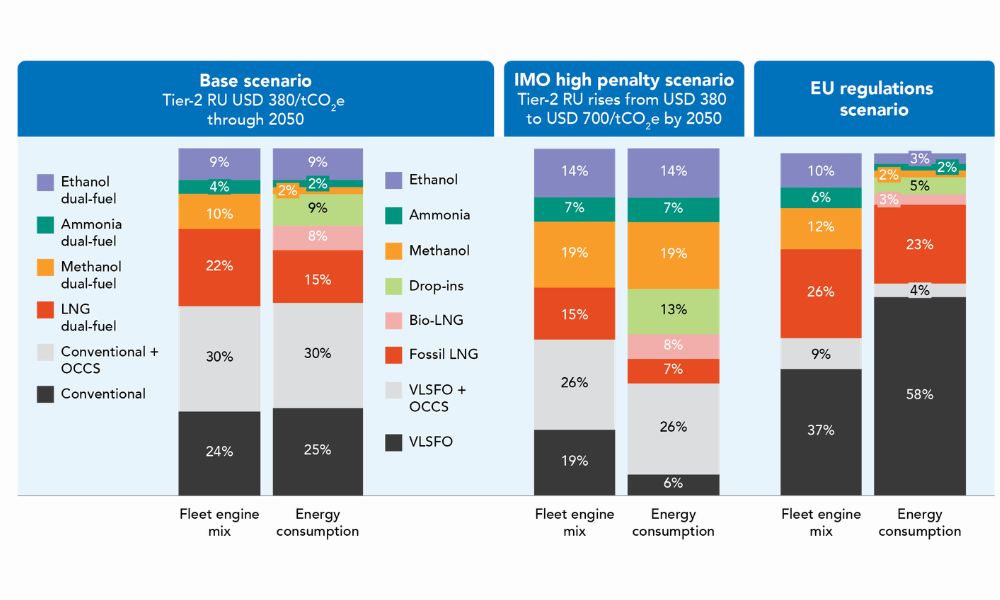
With vessels operating for 25 to 30 years and only around 4% of the fleet renewed annually, newbuild decisions made over the coming decade will establish much of the engine capacity available in 2050, Global Centre for Maritime Decarbonisation said on Thursday (17 September).
Yet having the capacity to consume a new fuel does not guarantee its uptake. Dual-fuel engines allow shipowners to switch between conventional fuels and the selected new fuel as economics and regulations evolve; continued fuel competitiveness is therefore critical to what vessels ultimately consume.
These are among the findings of Navigating the maritime fuel transition: How fuel economics, regulations, and fleet decisions shape the future bunkering landscape, based on a model jointly developed by the GCMD and Boston Consulting Group (BCG).
The model illustrates this dynamic in its base scenario. With the Tier-2 penalty under the IMO Net-Zero Framework held at USD 380/tCO2e through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity in 2050, but methanol represents just 2% of fleet energy consumption. With conventional fuels remaining more economical under this regulatory regime, methanol dual-fuel vessels continue to operate on fuels cheaper than methanol (Figure 1).
A global carbon price of USD 700/tCO2e materially changes the transition
The base scenario demonstrates how fuel economics can limit uptake even when vessels have the capacity to use new fuels. This picture changes if the IMO Tier-2 penalty rises to USD 700/tCO2e by 2050, at which point new fuels, including dropins, reach approximately 61% of fleet energy consumption (Figure 1).
By contrast, EU regulations alone will not drive a marked global shift, as they cover only around 20% of international shipping’s energy demand.
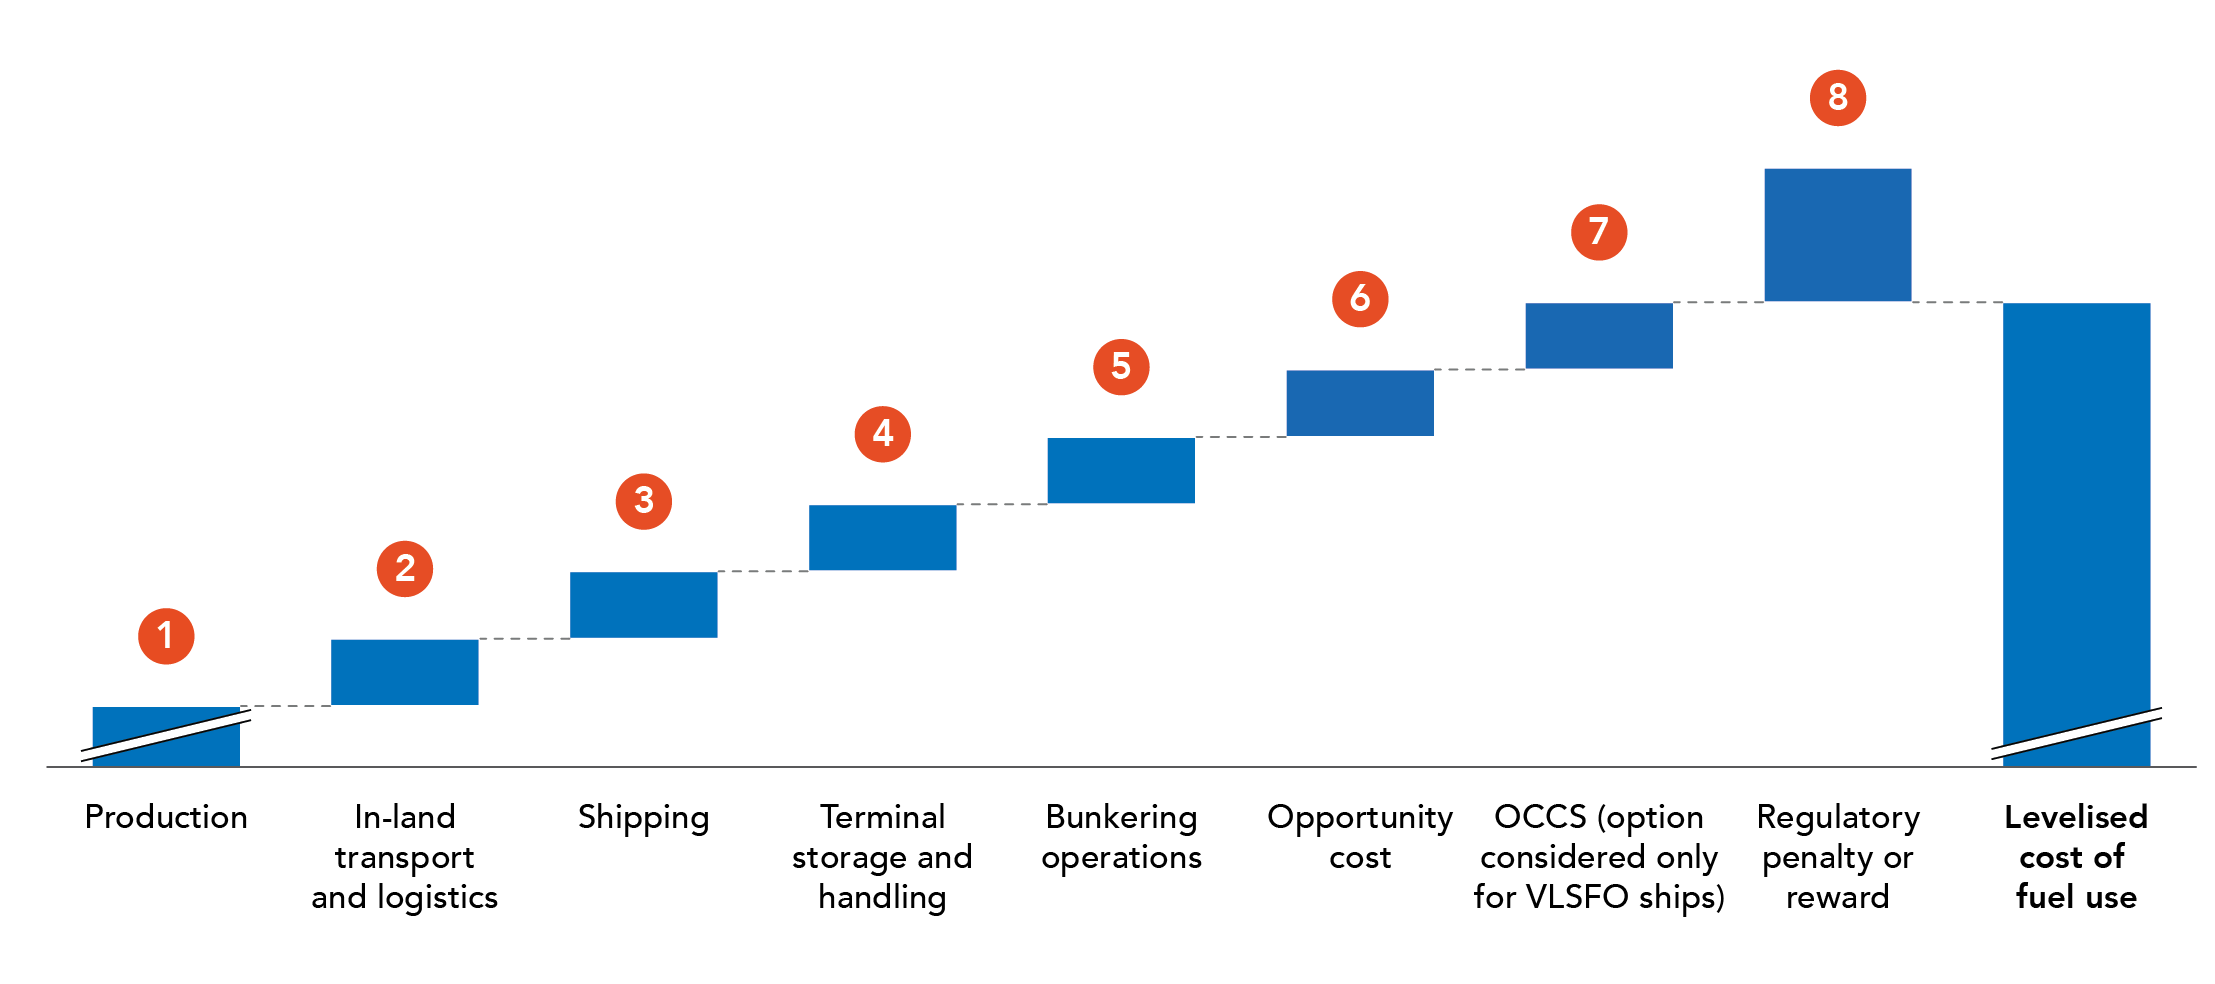
Overall cost of using e-methanol and e-ammonia is near parity
While a stronger global carbon price can accelerate the shift towards new fuels, the model does not point to a clear cost winner between e-methanol and e-ammonia.
E-ammonia’s production cost advantage is largely offset by higher logistics costs arising from its toxicity, including specialised crew training, larger exclusion zones, and more complex bunkering. As a result, the overall cost (Figure 2) of using e-ammonia and e-methanol is near parity through to 2050.
Professor Lynn Loo, CEO of GCMD, said: “Many vessels ordered over the coming decade will still be operating in 2050. Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear.
“Our modelling puts into perspective just how difficult closing the cost gap between new and conventional fuels will be. The carbon price required to close this gap is substantial. And achieving it will be particularly challenging in today’s geopolitical environment. Understanding the signposts that could change these economics will be critical to the decisions the industry makes today.”
Anand Veeraraghavan, Managing Director & Senior Partner at BCG, said: “The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness.
“Rather than offer a single prediction, our approach with GCMD maps how sensitive each fuel pathway’s competitive position is to a handful of critical variables — policy scenarios, key cost drivers, and potential restrictions. Our hope is that this gives shipowners, fuel suppliers, port operators, and infrastructure investors a practical tool to stress-test their own fuel strategies as conditions change.”
Photo credit: Global Centre for Maritime Decarbonisation
Published: 18 September, 2026
Methanol
SGMF releases first ISO-compliant Life Cycle Assessment of methanol as a marine fuel
Study evaluates 15 methanol production pathways and finds that methanol produced using renewable energy sources can deliver substantial emissions reductions.

OUR INDUSTRY PARTNERS

Petrochina International blends over 30,000 mt of marine biofuel since March

Singapore: Final general meetings scheduled for Dromond Shipping, related firms

NYK wraps up first STS ammonia bunkering operation in Japan

Azane secures ammonia bunker fuel supply from Yara

Moeve launches construction of green hydrogen project to support marine fuels

DNV: How ethanol is expanding shipping’s fuel choices

World Fuel founder Michael J. Kasbar to step down as Executive Chairman

Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE

Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea

Kongsberg Maritime to buy Finnish marine propulsion designer Steerprop

High Court of Singapore issues winding up order against Hengli Petrochemical International

China: Guangzhou completes first bio-methanol STS bunkering operation
-
 Incident2 weeks ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Winding up6 days ago
Singapore: Marine fuel testing firm CCIC Singapore faces winding up application
-
 Technology2 weeks ago
Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE
-
 Ammonia1 week ago
Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea
-
 Business2 weeks ago
Kongsberg Maritime to buy Finnish marine propulsion designer Steerprop
-
 Winding up1 week ago
High Court of Singapore issues winding up order against Hengli Petrochemical International
-
 Alternative Fuels2 weeks ago
China: Guangzhou completes first bio-methanol STS bunkering operation
-

 Engine1 week ago
Polaris Shipping orders WinGD engines capable of running on methanol, ethanol