Interview
GCGF: Why ethanol deserves a seat at the alternative bunker fuels table
While green marine fuels have had strong industry backing, ethanol’s benefits haven’t been highlighted enough for maritime use. Chris Chatterton makes his case on why that should change.

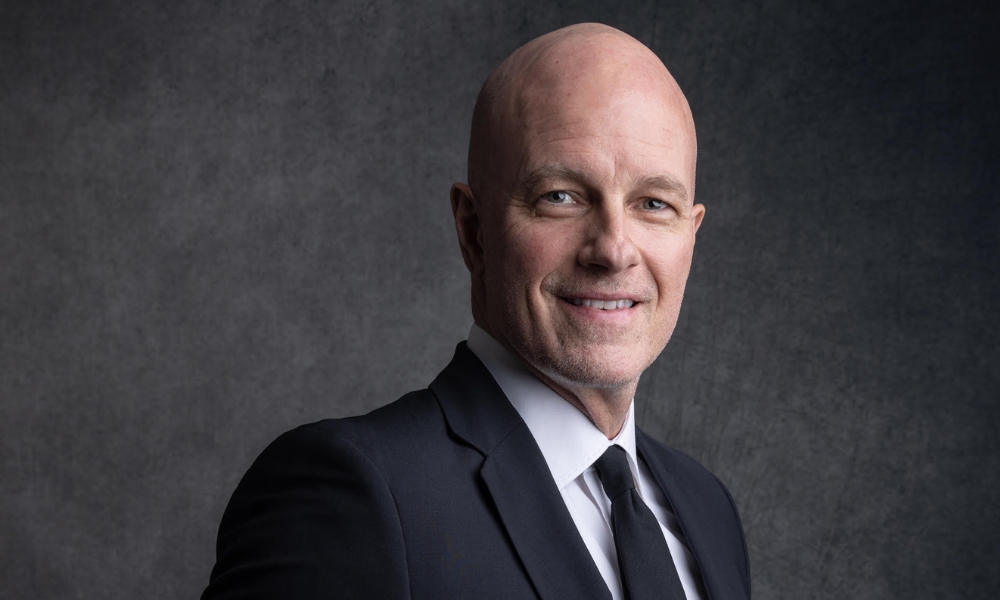
Chris Chatterton, Maritime Advisor of Global Centre for Green Fuels (GCGF), believes ethanol should have a seat at the alternative bunker fuel table and he shares with Singapore-based bunkering publication Manifold Times why it deserves to be part of the conversation:
MT: Tell us a little about GCGF, when it started and its mission.
The Global Centre for Green Fuels, or GCGF, is a non-profit global think tank headquartered in Singapore. We were established in 2024 to accelerate the adoption of sustainable fuels across maritime, aviation, and land transport. Our work focuses on enabling real-world deployment of low-carbon solutions through data-driven policy, technical validation, and strategic industry collaboration. We help stakeholders – from regulators to shipowners – navigate decarbonisation challenges with practical, scalable fuel strategies.
MT: As its maritime advisor, why do you think ethanol should be considered as an additional maritime fuel?
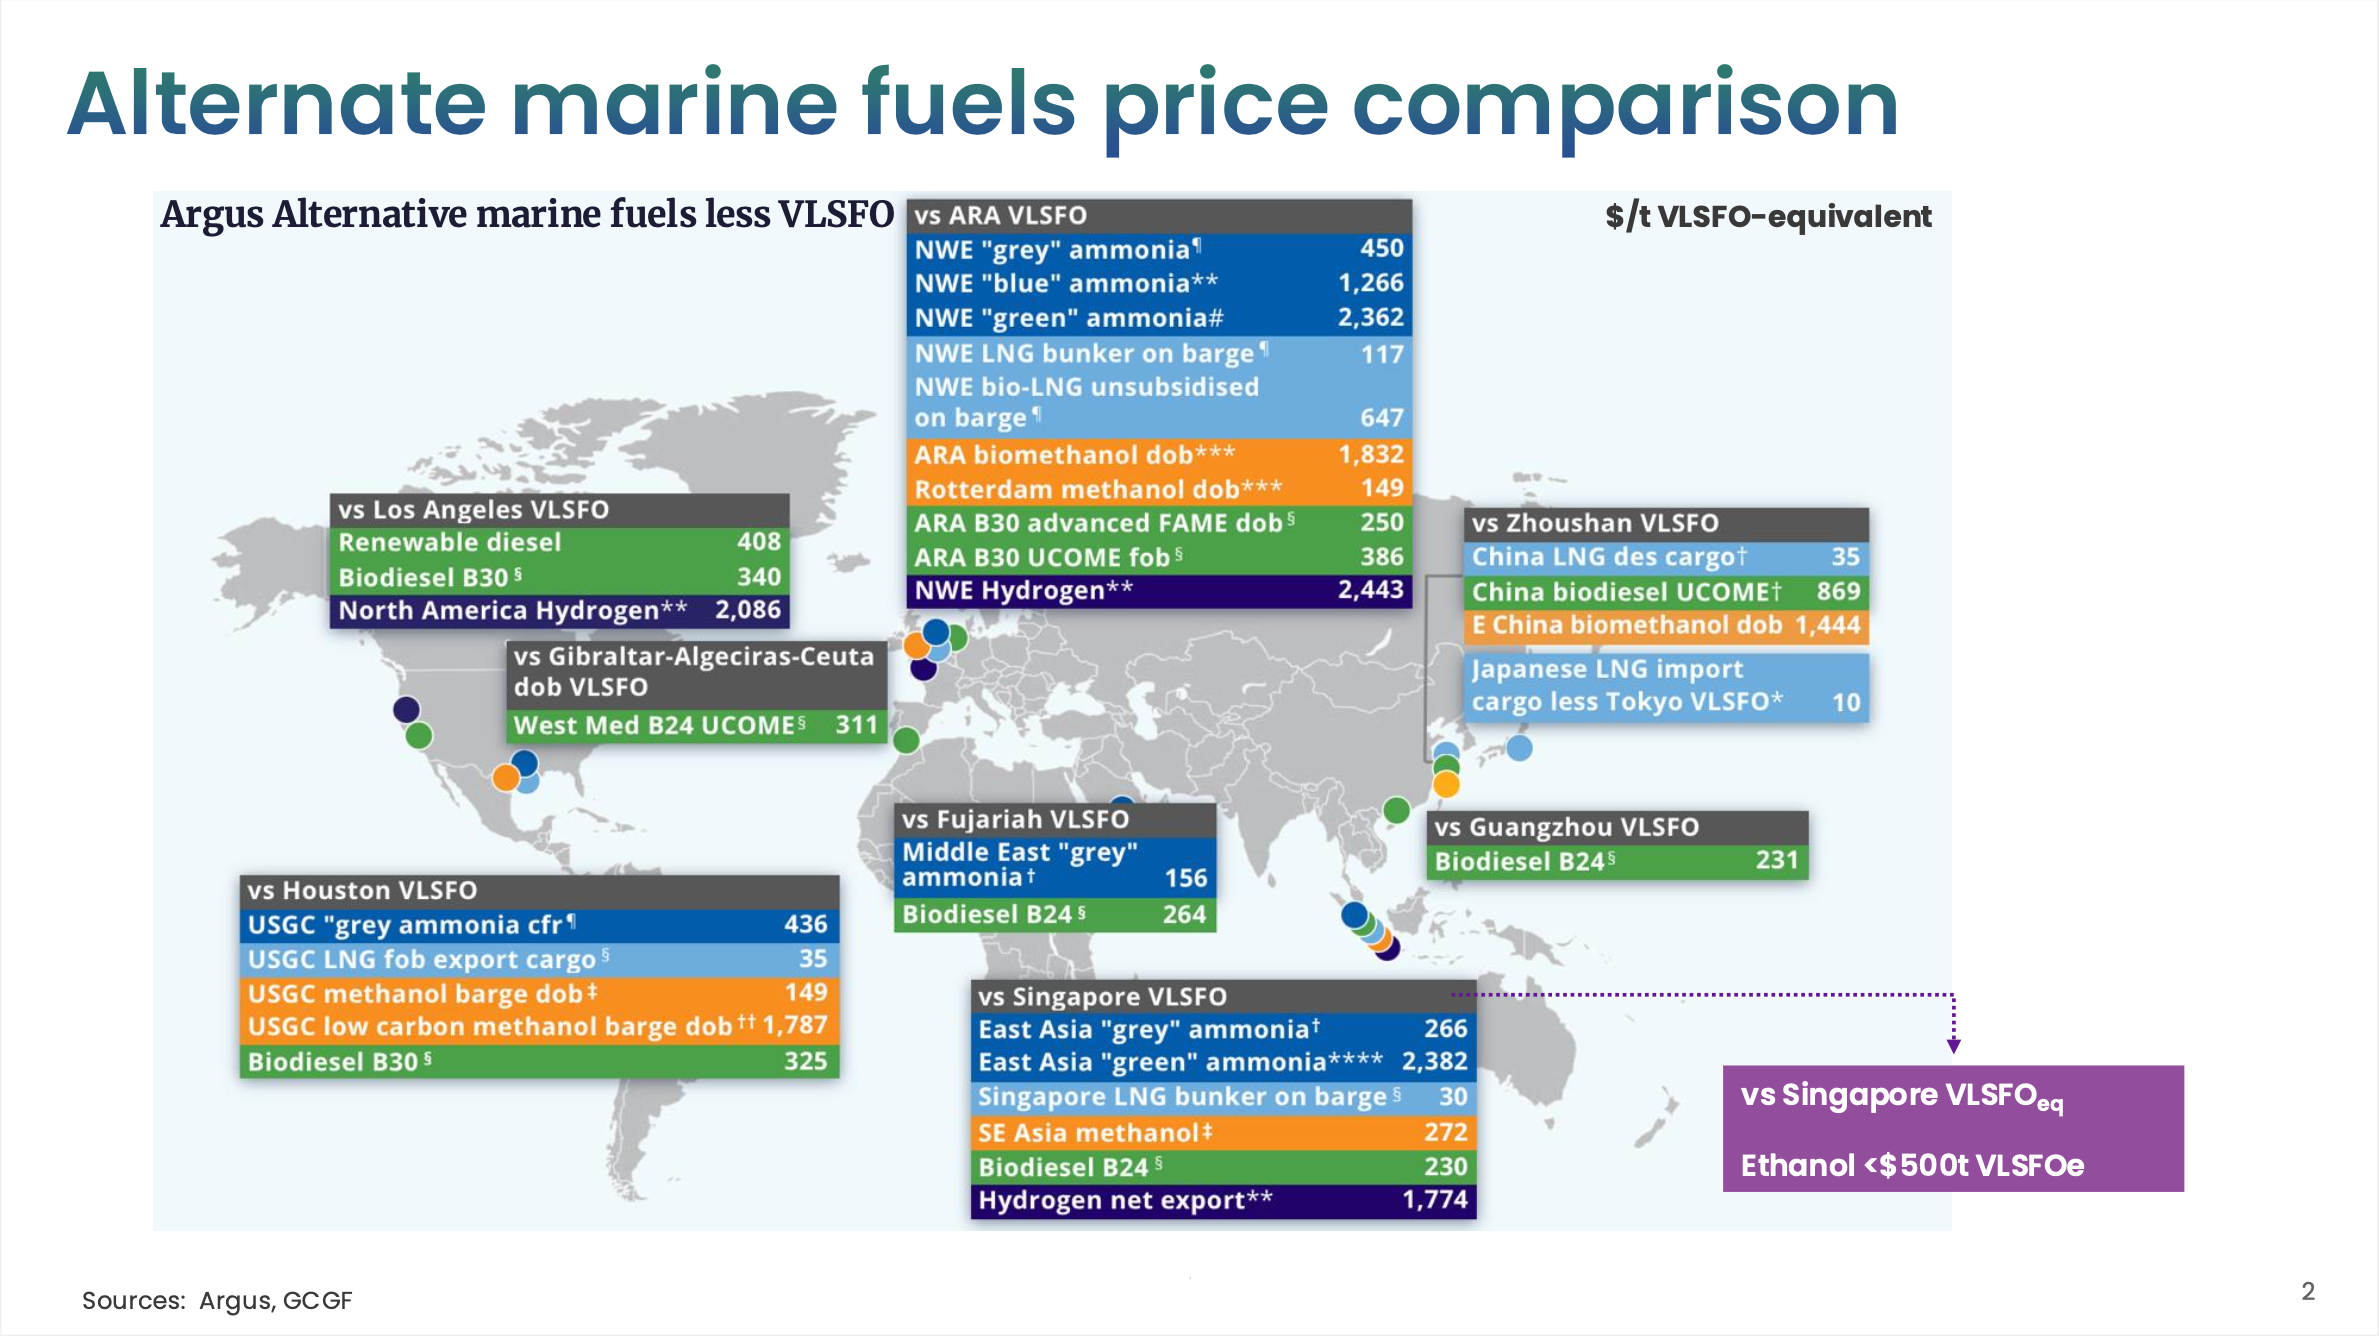
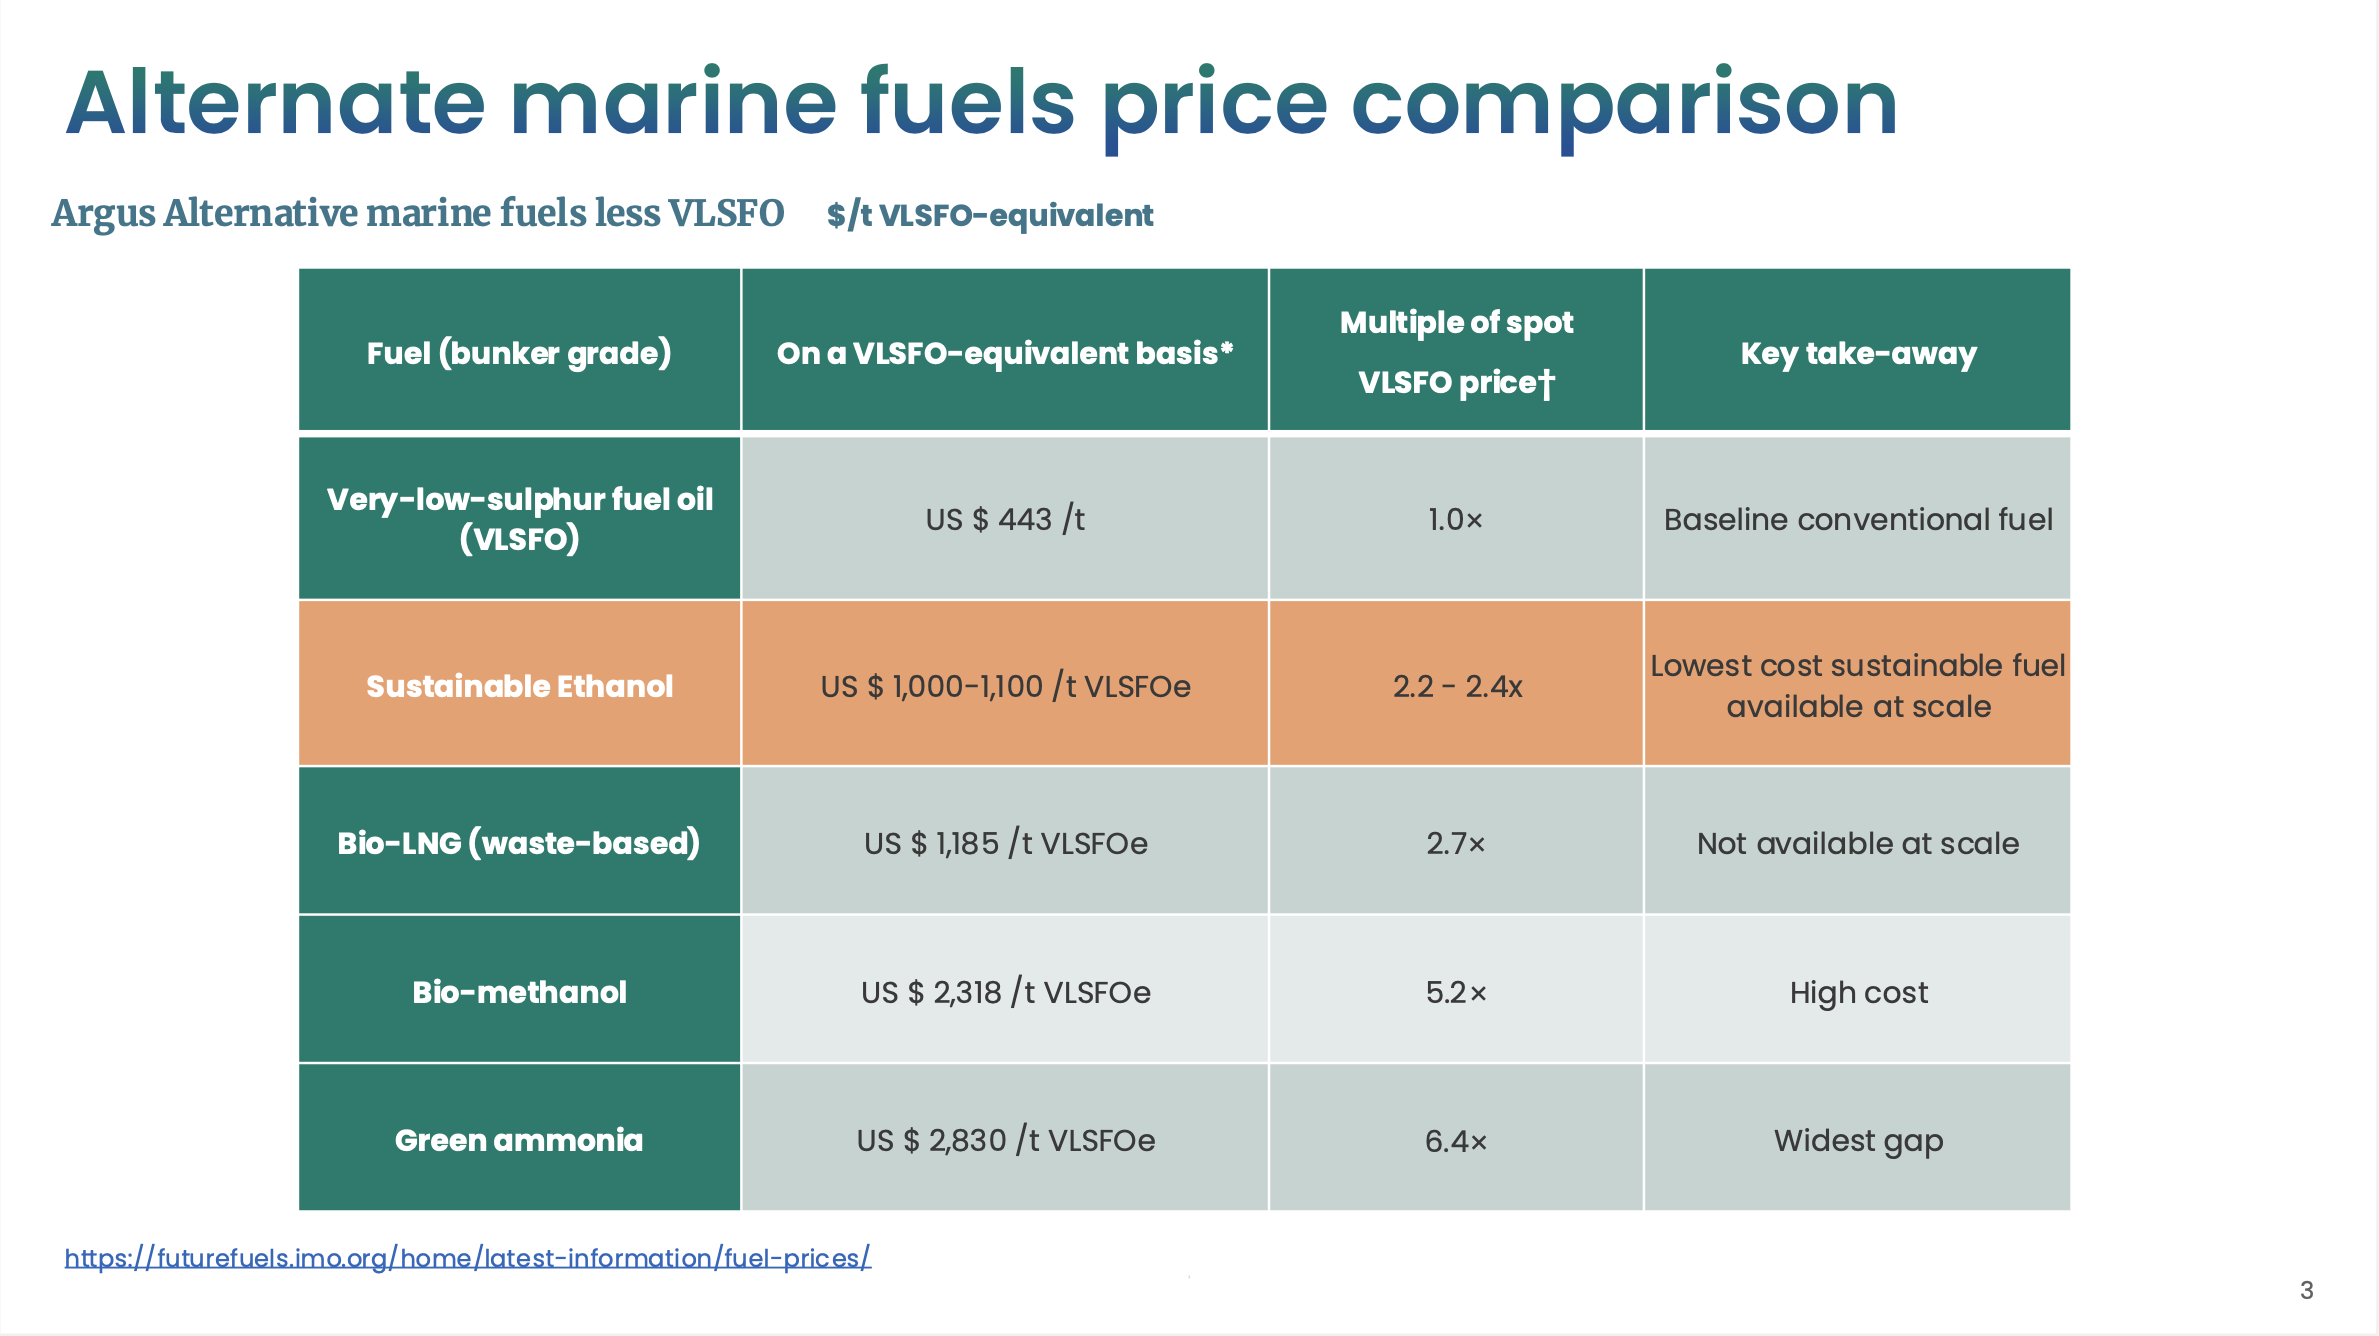
Ethanol presents a pragmatic pathway to decarbonise shipping. It’s widely available globally, competitively priced, and can be used with existing methanol dual-fuel engine platforms – often with minor re-calibration. Importantly, ethanol offers very low lifecycle emissions, whether derived from crops, waste or lignocellulosic biomass. Ethanol’s clean combustion profile also helps reduce local air pollutants like SOx and PM (particulate matter). Given the urgency of the IMO’s 2030 and 2050 decarbonisation targets, ethanol stands out as an immediate, scalable, and practical solution.
MT: What’s the current status of the push on ethanol following the document submission, highlighting the use of ethanol as a marine fuel, from Brazil and IBIA at IMO MEPC 83?
That submission was a critical milestone. It called for three main actions: a) inclusion of ethanol in the GESAMP LCA Working Group for lifecycle assessment, b) a request for ISO to develop a marine fuel standard for ethanol, and c) updates to the IGF Code to reflect ethanol-specific safety and operational differences from methanol. The submission was well received and is now being processed through relevant sub-committees like CCC and MSC. GCGF is supporting this by coordinating technical input and promoting pilot demonstrations and engine testing.
MT: With lots of focus on LNG, methanol, ammonia and hydrogen as part of the future marine fuel mix, why do you think there hasn’t been much talk on ethanol and what do you think needs to be done to ensure it is part of the alternative fuel pool?
The ethanol story in shipping is just now being told. Other fuels have had strong industry backing and early movers, whereas ethanol’s benefits – such as its wide availability and infrastructure compatibility – haven’t been highlighted enough for maritime use. What’s needed is greater awareness, technical standardisation, and real-world demonstrations. Ethanol can be bunkered through the same terminals and handled with very similar safety protocols as methanol. Singapore, being a global maritime hub, can play a pivotal role in advancing ethanol’s case through bunkering, pilots and green corridors.
What are the challenges to achieve widespread adoption of ethanol as a marine fuel in terms of production, fuel availability, safety, and long-term viability and how can they be overcome?
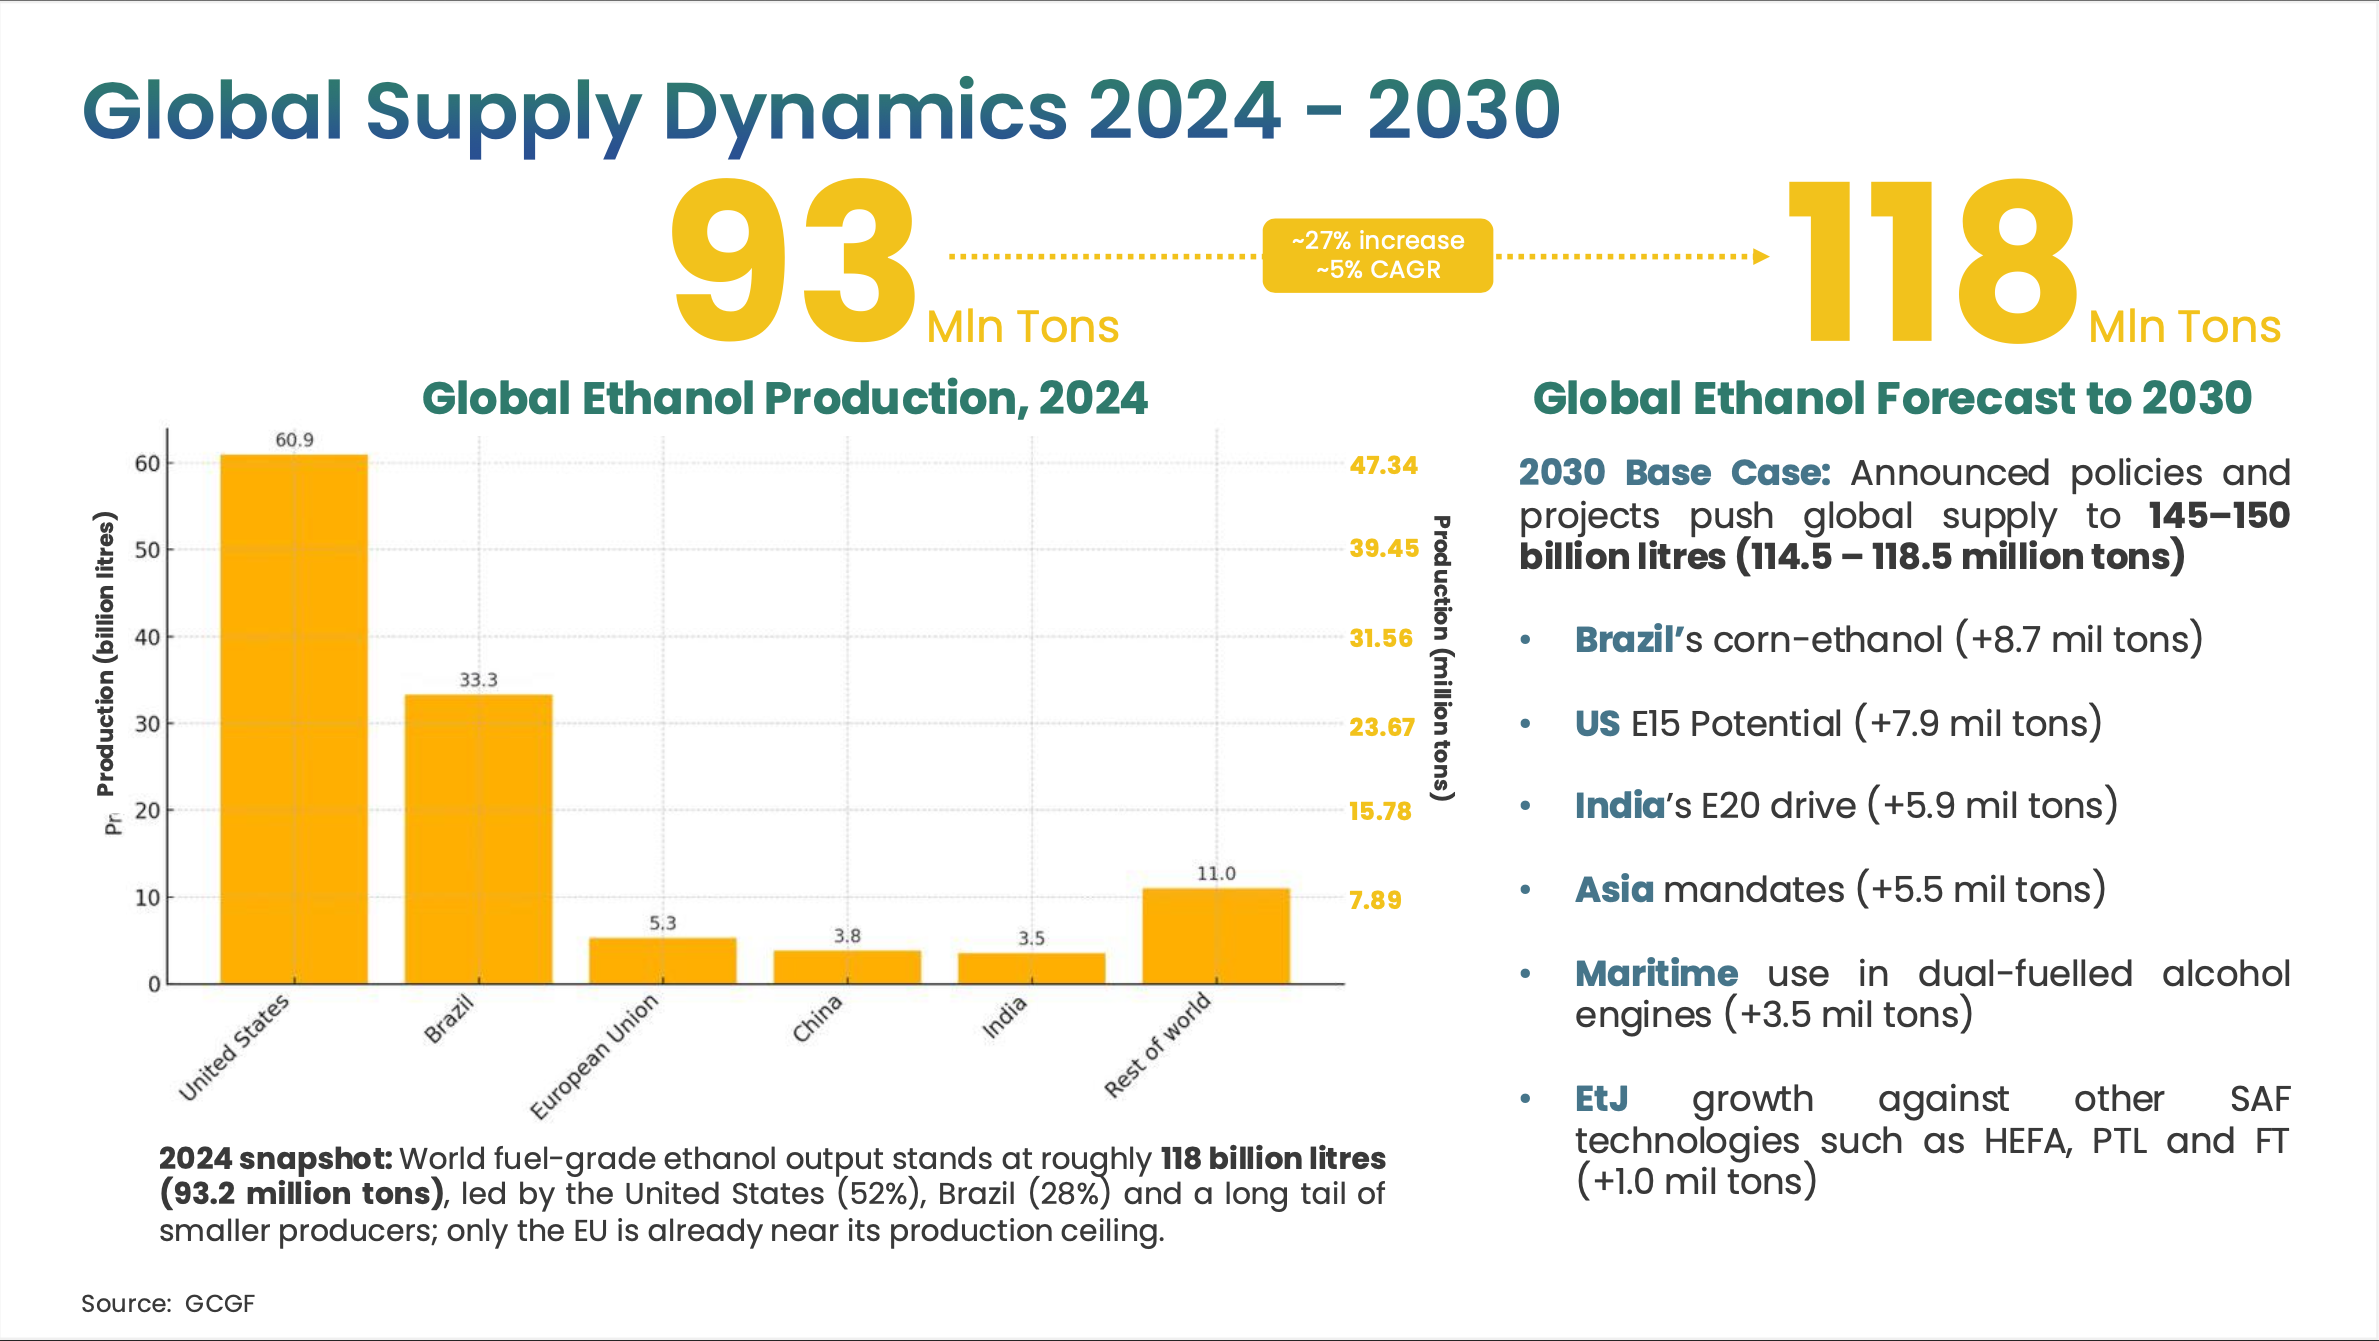
Global ethanol supply is already robust – almost 100M mtpa currently – mainly from the U.S., Brazil, Europe, and a growing number of producers in Asia. That’s enough to support near-term maritime demand. Safety-wise, ethanol is classified as a low-flashpoint fuel, similar to methanol, and requires careful handling – something the industry is already accustomed to. Long-term viability depends on sustainability certification, cost competitiveness, and standardisation – all areas GCGF is working to address. The potential is there – it just needs the right regulatory and commercial framework.
MT: As the IMO’s IGF Code already includes methyl/ethyl alcohols as marine fuel, are there specific advantages in using ethanol vs methanol? What are the specific risks of ethanol, compared with methanol?
While it’s true that ethanol has a low flashpoint similar to methanol and as addressed in the IMO IGF Code, it’s important to note that methanol’s flash point, already in use as a marine fuel, is slightly lower. So low flashpoint alone isn’t a disqualifier, it’s a characteristic that must be managed through proper standards and safety protocols. Importantly, ethanol has a significantly lower toxicity risk than methanol, making it safer for crew handling, spill and salvage scenarios.
Ethanol has lower energy density than fuel oil, but higher than methanol, which makes it slightly more efficient too. Therefore, what is needed is a robust, ethanol specific ISO standard that accounts for its unique properties such as water miscibility, energy content, and ignition characteristics. Importantly, ethanol also carries significantly lower toxicity risks than methanol, making it safer for crew handling and spill scenarios.
Interim IMO guidelines already acknowledge ethanol alongside methanol, and class societies have started aligning with these. But we still require marine-specific test protocols, safe handling/safety training, and OEM validation to close the gap and highlight the slight differences between methanol and ethanol as ship fuels. This is a key agenda item for us at GCGF in 2025–2026.
MT: Do engines and tanks on ships need to be modified to use ethanol? How easy or difficult is it to adopt ethanol as a marine fuel?
It’s surprisingly straightforward. Modern dual-fuel engines designed for methanol and electronically controlled – like the Wärtsilä W25, W32, the Everllence (MAN) LGI series and several WindGD models – can be re-calibrated to ethanol with minimal hardware changes. It’s mainly a software calibration and minimal adjustments in the fuel supply system. Several leading OEMs have confirmed this compatibility, and we’re now working with engine OEMs to initiate formal testing and trials. The real opportunity lies in making ships “alcohol-ready,” giving owners flexibility between methanol and ethanol based on cost, supply, and route-specific decarbonisation goals.
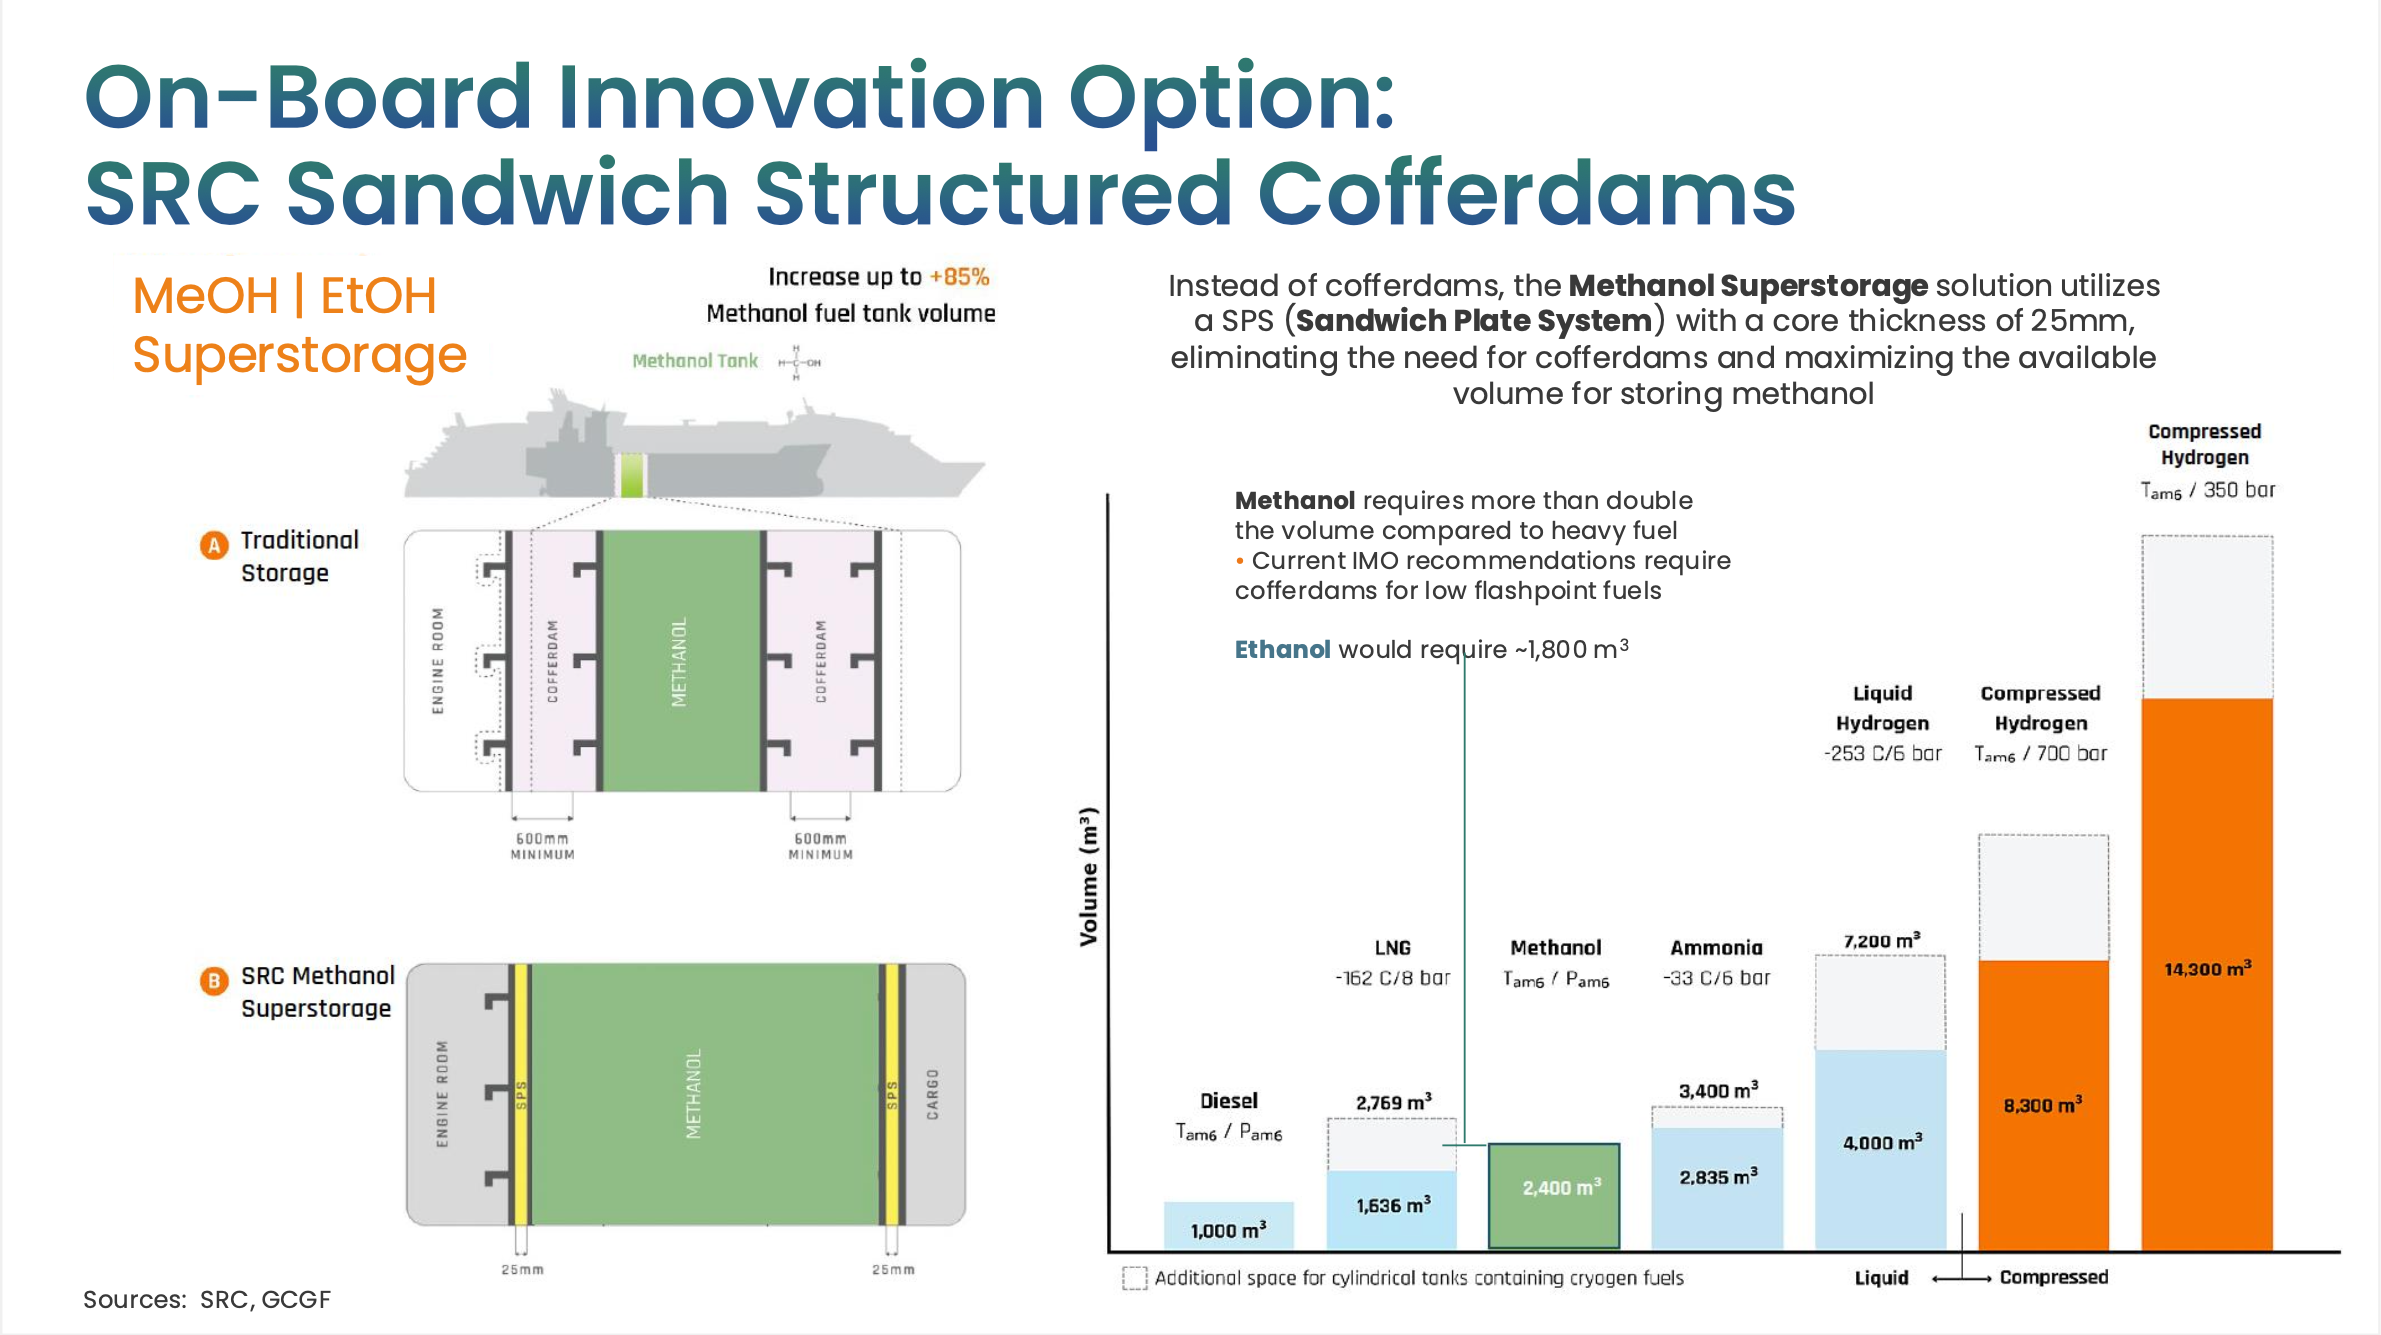
Additionally, technology is driving the ability to equalise energy storage on board with the inclusion of Sandwich Structured Cofferdams, enabling lower energy density fuels such as methyl/ethyl alcohols to be bunkered on a Fuel Oil energy-equivalent basis.
MT: With growing interest in cleaner fuels, what are the sustainable advantages of the production of ethanol?
Ethanol supports both climate and energy security goals. Today’s production combines regenerative and precision agriculture with advanced biorefining technologies, resulting in exceptionally low carbon intensity ethanol, on par with or better than many synthetic fuels. It’s also a liquid fuel, meaning it can readily leverage existing bunkering and storage infrastructure. On a macro level, ethanol production supports rural economies, energy security by reducing fossil fuel dependence, and creates a unified supply chain for land, sea, and air transport – as we’re already seeing in places like Brazil, India, and potentially Japan.
Photo credit: Global Centre for Green Fuels
Published: 8 August, 2025
Business
Malaysia: Maharani Energy Gateway introduces MEG OSC (One Stop Centre) to support investors’ growth at Freeport
MEG OSC serves as a dedicated facilitation centre, providing investors with advisory and coordination services throughout the investment lifecycle within Maharani Freeport.
Interview
China’s bunker market reshaped by tax rebates, trade flows and refining changes, says economist
Dr Kang Wu discusses how China’s bunker fuel tax rebate, shifting refinery output, import flows and alternative fuel adoption are reshaping the country’s marine fuels market and its competitive position.
Bunker Fuel
NW Corporation expands Malaysia bunkering fleet with acquisition of “BELLAA 1”
The company’s immediate growth strategy remains focused on Port Klang, where it continues to strengthen its market presence and provide comprehensive bunkering solutions for its customers.
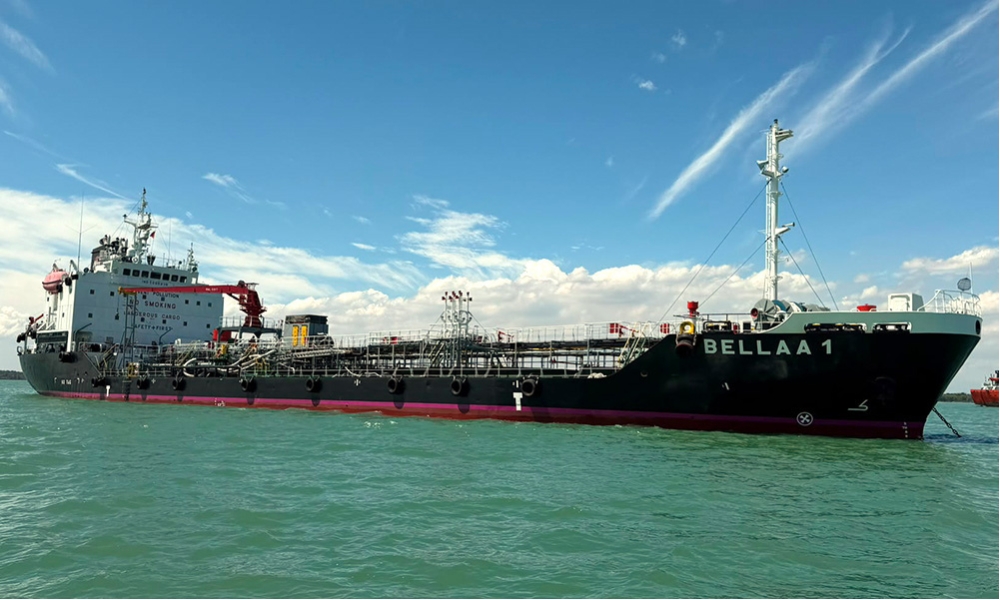
Singapore-based commodities and oil cargo trading firm NW Corporation Pte Ltd (NWC) has expanded its Malaysia bunkering operations through the acquisition of Bellaa 1 (IMO 9269398), increasing its monthly bunker supply capability to approximately 30,000-35,000 mt.
“Bellaa 1 is a Malaysia-flagged bunker tanker with a loadable cargo capacity of approximately 5,000-5,500 mt of Low Sulphur Fuel Oil (LSFO),” Jason Tan, Co-founder and Head of Commercial of NWC, told Manifold Times on Tuesday (14 July).
“The addition of Bellaa 1 represents another important milestone in our fleet expansion strategy. It strengthens our operational capability, improves supply flexibility and enables us to better support the increasing demand for LSFO in Port Klang.”
Following the acquisition, the bunker tanker underwent an intermediate survey, was renamed in Singapore and is scheduled to commence commercial bunkering operations from August 2026.
According to Mr Tan, the acquisition will expand NWC’s LSFO supply capability, improve operational flexibility, increase vessel availability, enhance service reliability and support continued growth in bunker sales at Port Klang.
“NWC commenced bunkering operations at Port Klang in April 2024 with a single bunker barge and an initial monthly supply volume of approximately 10,000 mt,” said Mr Tan.
“The introduction of Bellaa 1 will increase our monthly bunker supply volume from approximately 20,000 mt to around 30,000-35,000 mt, driven by continued growth in bunker demand at Port Klang.”
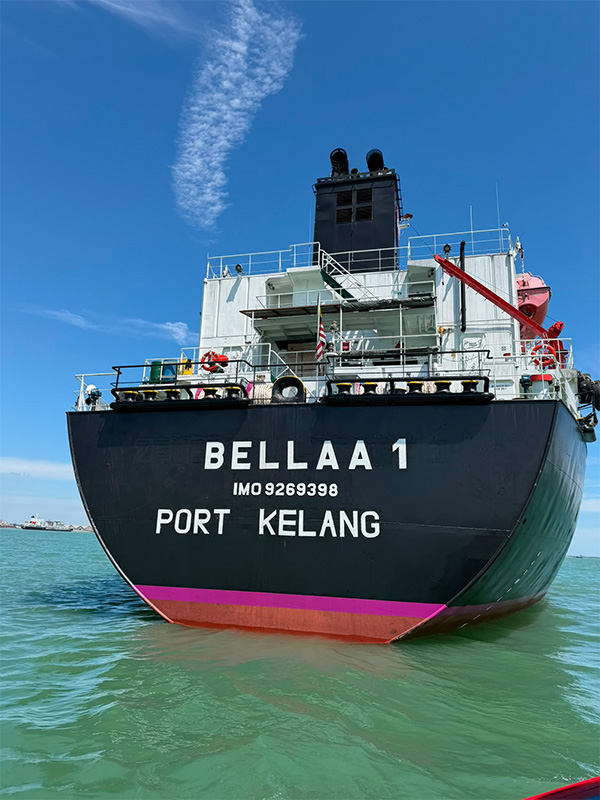
Since entering the Port Klang market in 2024, NWC has steadily expanded its bunkering operations in tandem with growing customer demand. The latest fleet addition reflects the company’s continued investment in strengthening its supply capability and operational reliability.
Moving forward, Mr Tan pointed out NWC’s immediate growth strategy remains focused on Port Klang, where the company continues to strengthen its market presence and provide comprehensive bunkering solutions for its customers.
“Our immediate priority remains Port Klang, where we continue to see strong opportunities for growth. We will keep investing in fleet capability, operational efficiency and customer service while strengthening our trading activities and bunker supply network,” he stated.
“With a growing fleet, experienced operational team and strong partnerships with major bunker traders and suppliers, we are well positioned to expand our market share and reinforce our position as a trusted bunker supplier in the region.”
About NW Corporation
NW Corporation Pte Ltd is a Singapore-headquartered commodities and energy trading company engaged in oil cargo trading, bunkering, marine logistics and energy infrastructure investments across Asia. The company has been expanding its bunkering footprint in Port Klang as part of its long-term regional growth strategy.
Related: Singapore: NW Corporation welcomes “Fortune Glory” after three-week drydocking ops
Related: NW Corporation strengthens Port Klang operations with newly acquired bunker tankers
Photo credit: NW Corporation Pte Ltd
Published: 12 August, 2026

OUR INDUSTRY PARTNERS

MPA: 25 crew rescued after abandoning “MSC HERMES III” east of Vietnam

GCMD, Equinor to combine expertise on alternative bunker fuels, decarbonisation solutions

Wah Kwong NatPower, AREL partner on maritime electrification in Hong Kong

IMO technical seminar examines ammonia bunkering and infrastructure

Spring Marine to expand use of Sulnox Eco with four-year supply agreement

PortXchange: Rotterdam bunker volume shift offers warning as Spain adopts fuel law

ENGINE: East of Suez Fuel Availability Outlook (22 Sep 2026)

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”

Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE

Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea

High Court of Singapore issues winding up order against Hengli Petrochemical International

Polaris Shipping orders WinGD engines capable of running on methanol, ethanol

APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists
-
 Winding up1 week ago
Singapore: Marine fuel testing firm CCIC Singapore faces winding up application
-
 Incident2 weeks ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Technology2 weeks ago
Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE
-
 Ammonia2 weeks ago
Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea
-
 Winding up1 week ago
High Court of Singapore issues winding up order against Hengli Petrochemical International
-
 Engine2 weeks ago
Polaris Shipping orders WinGD engines capable of running on methanol, ethanol
-
 Technology1 week ago
APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists
-
 Financial Result2 weeks ago
Singapore-based Uni-Fuels H1 2026 net income jumps 1,415% to USD 1.4 million