Connect with us

Decarbonisation

Aderco: Sustainable shipping without the spin

Esteve Servajean says maritime industry commitment must extend to delivering greater data transparency and measurable action to prevent decarb projects from becoming mere exercises in optics.

Admin

Published

on

Esteve Servajean, Head of Marine, Aderco

To meet the IMO’s emissions reduction targets, maritime industry commitment must extend to delivering greater data transparency and measurable action to prevent decarb projects from becoming mere exercises in optics, writes Esteve Servajean, Head of Marine at fuel treatment technology specialist Aderco:

While the maritime sector often expresses its commitment to the International Maritime Organization’s (IMO’s) Net Zero ambitions and 2030/2050 targets, rhetoric and reality also frequently diverge. In many respects, our sector is a laggard among global industries where emissions are concerned and needs to take a hard, honest look at itself  – or risk falling even further behind by clinging to outdated concepts, strategies and technologies.

Conventionally, ship ‘efficiency’ has been measured in fuel cost per tonne-mile. However, although many have yet to grasp the fact,  this metric is becoming obsolete. Today, the true efficiency of a ship is measured in multiple parameters, which encompass fuel cost and emissions from the stack but also include lifecycle emissions (plus upstream fuel production and vessel disposal), real-time carbon transparency, and the social and regulatory requirements for navigating relationships with ports, financial institutions and cargo owners.

At Aderco, we see this transformation daily. Five years ago, operators primarily spoke to us about fuel savings; today, they demand proven emissions reduction solutions, compatibility with future fuels and verifiable contributions to ESG performance. Companies still measuring efficiency on a single axis are already falling behind.

The future is multi-fuel

Let’s dispel another outdated misperception causing more harm than good: the belief that a single, specific alt-fuel will deliver Net Zero for maritime within the next two decades. The future is multi-fuel, and shipowners must accept and plan for that, ensuring a high degree of flexibility when assessing their options.

Accepting this proposition, it is still fair to ask what the point is of investing in a specific fuel if the ship may operate in regions where the portside infrastructure for that fuel is lacking. The truth is, the availability of green methanol, bio-LNG and ammonia at scale is years behind schedule, even at the major ports that drive global trade. For this reason, shipowners should lean towards investments into dual-fuel configurations where commercially viable and avoid long-term supply contracts tied to a single fuel.

It is not all about fuel selection; operational optimisation remains the most actionable lever today, from engine condition management and real-time fuel consumption monitoring to efficient voyage planning. Even simpler measures, including the application of high-performance anti-fouling coatings, wind-assisted propulsion systems and underwater turbines, are now part of the conversation. Various practical and complementary solutions can be implemented immediately without waiting for new fuel infrastructure to catch up.

The industry must therefore resist the temptation to standardise too early. Instead, it should build flexible, adaptive strategies that can evolve as the landscape changes. Most importantly, while some uncertainty regarding future fuels is natural, it must never become an excuse for inaction.

Regulatory fragmentation

On the regulatory side, FuelEU Maritime, the Carbon Intensity Indicator (CII) and the IMO’s revised greenhouse gas reduction strategy have created a framework shipowners cannot ignore. However, while shipowners are pragmatic investors, they need a clear regulatory framework and a long-term vision before they commit capital with confidence.

At present, regulatory fragmentation is a serious obstacle. The IMO sets global ambitions, but the EU is advancing on its own timeline and with its own instruments. This is forcing shipowners operating under multiple jurisdictions to navigate numerous, sometimes contradictory regulatory frameworks simultaneously.

The skills and data gap is also severely underestimated. Achieving 2030 and 2050 milestones will require not just new hardware, but new competencies in fleet management, data analytics and carbon accounting. The maritime sector is only starting to take this human capital challenge seriously.

Equally important is investment in data infrastructure. Reliable energy consumption, emissions and performance data is a crucial competitive asset, regardless of the alt-fuel selected. Unavoidably, the answer must make economic sense.

Get off the sidelines

To resolve regulatory fragmentation, only IMO can implement a carbon levy framework on a global basis. A credible, maritime-specific carbon credit scoring system could unlock capital, reward early adopters and create genuine behavioural incentives across the supply chain.

To be credible, though, this system must be built on real, verifiable data, not theoretical models, and must connect meaningfully to financial instruments to have actual market impact. We have seen too much greenwashing in other sectors, with initiatives often prioritising optics over actual emissions reductions. Maritime must therefore acknowledge its historically poor emissions data quality, get off the sidelines and take urgent action to fix it.

Fortunately, European green finance is proving a major accelerator. Instruments such as green bonds, sustainability-linked loans and the Poseidon Principles have moved into the mainstream and are now influencing key boardroom decisions. While stranded asset risk is real, so is the danger of losing competitive ground. The best approach is to focus on what can be actioned today, build flexibility into investment choices and stay closely aligned with regulatory and customer expectations. Any successful drive towards Net Zero relies on a fine balancing act between regulation and market forces.

The companies that help define credible standards will be far better positioned than those that react to them later. However, and it cannot be overemphasised, the bar for ‘credible’ must be high, incorporating transparency, independent verification and a direct link to measurable emissions outcome. Without that, we risk creating another layer of complexity with no clear impact.


Photo credit: Aderco
Published: 10 June, 2026

Continue Reading

Alternative Fuels

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

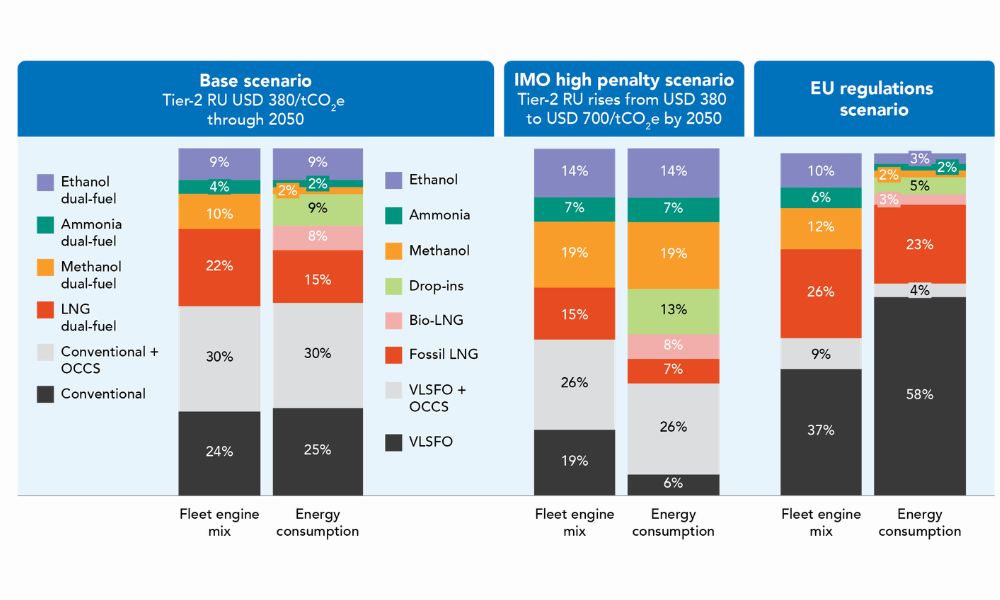
New fuels could reach around 60% of fleet energy consumption under a sufficiently strong carbon price signal, modelled at USD 700/tCO2e by 2050.
Admin

Published

on

By

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

With vessels operating for 25 to 30 years and only around 4% of the fleet renewed annually, newbuild decisions made over the coming decade will establish much of the engine capacity available in 2050, Global Centre for Maritime Decarbonisation said on Thursday (17 September). 

Yet having the capacity to consume a new fuel does not guarantee its uptake. Dual-fuel engines allow shipowners to switch between conventional fuels and the selected new fuel as economics and regulations evolve; continued fuel competitiveness is therefore critical to what vessels ultimately consume.

These are among the findings of Navigating the maritime fuel transition: How fuel economics, regulations, and fleet decisions shape the future bunkering landscape, based on a model jointly developed by the GCMD and Boston Consulting Group (BCG).

The model illustrates this dynamic in its base scenario. With the Tier-2 penalty under the IMO Net-Zero Framework held at USD 380/tCO2e through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity in 2050, but methanol represents just 2% of fleet energy consumption. With conventional fuels remaining more economical under this regulatory regime, methanol dual-fuel vessels continue to operate on fuels cheaper than methanol (Figure 1).

A global carbon price of USD 700/tCO2e materially changes the transition

The base scenario demonstrates how fuel economics can limit uptake even when vessels have the capacity to use new fuels. This picture changes if the IMO Tier-2 penalty rises to USD 700/tCO2e by 2050, at which point new fuels, including dropins, reach approximately 61% of fleet energy consumption (Figure 1).

By contrast, EU regulations alone will not drive a marked global shift, as they cover only around 20% of international shipping’s energy demand.

Overall cost of using e-methanol and e-ammonia is near parity

While a stronger global carbon price can accelerate the shift towards new fuels, the model does not point to a clear cost winner between e-methanol and e-ammonia.

E-ammonia’s production cost advantage is largely offset by higher logistics costs arising from its toxicity, including specialised crew training, larger exclusion zones, and more complex bunkering. As a result, the overall cost (Figure 2) of using e-ammonia and e-methanol is near parity through to 2050.
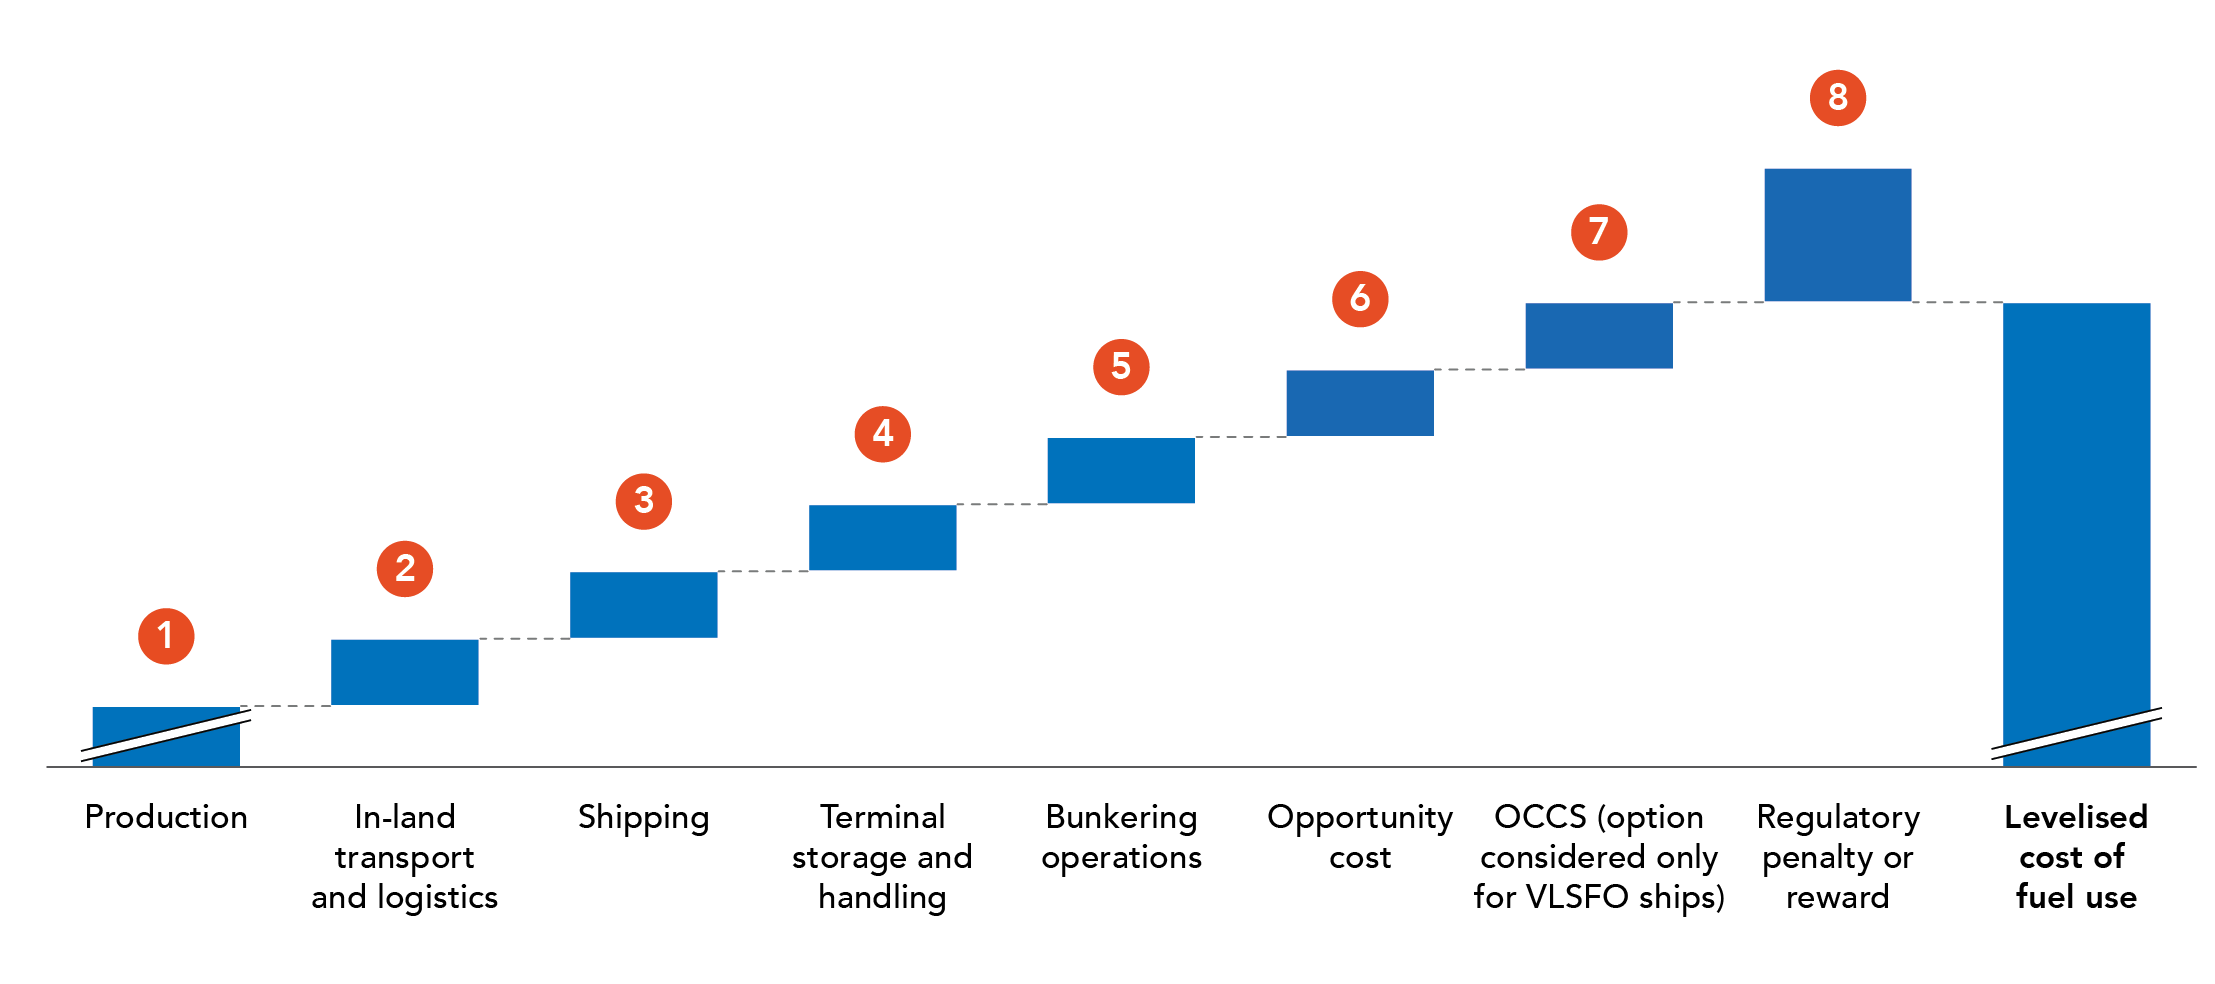
Fig 2 Constituents of levelised cost of fuel use

Professor Lynn Loo, CEO of GCMD, said: “Many vessels ordered over the coming decade will still be operating in 2050. Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear. 

“Our modelling puts into perspective just how difficult closing the cost gap between new and conventional fuels will be. The carbon price required to close this gap is substantial. And achieving it will be particularly challenging in today’s geopolitical environment. Understanding the signposts that could change these economics will be critical to the decisions the industry makes today.”

Anand Veeraraghavan, Managing Director & Senior Partner at BCG, said: “The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness. 

“Rather than offer a single prediction, our approach with GCMD maps how sensitive each fuel pathway’s competitive position is to a handful of critical variables — policy scenarios, key cost drivers, and potential restrictions. Our hope is that this gives shipowners, fuel suppliers, port operators, and infrastructure investors a practical tool to stress-test their own fuel strategies as conditions change.”


Photo credit: Global Centre for Maritime Decarbonisation
Published: 18 September, 2026

Continue Reading

Newbuilding

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

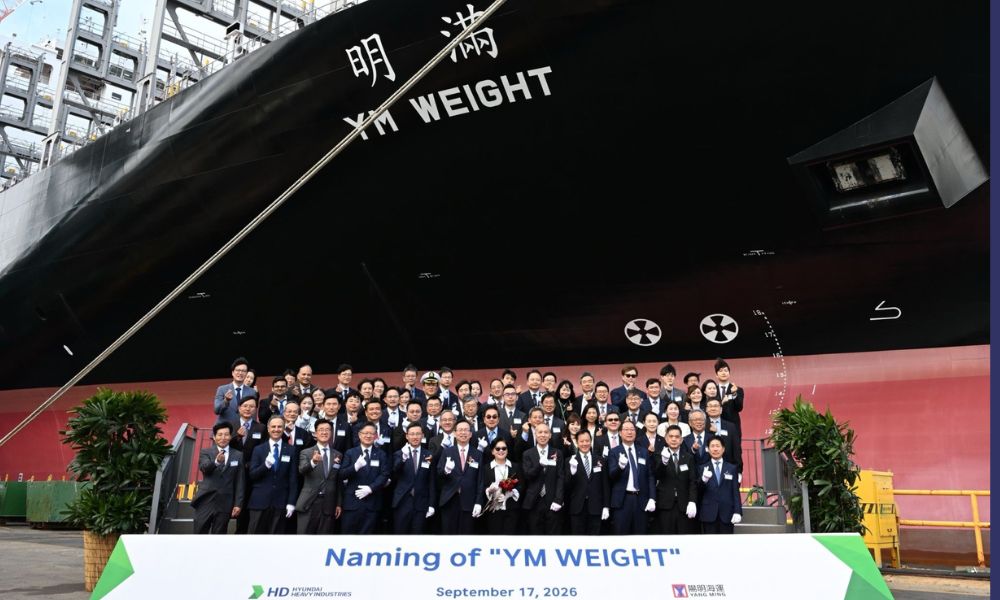
Yang Ming held a naming ceremony at the HD HHI shipyard in Ulsan, South Korea, for “YM Weight”, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI.
Admin

Published

on

By

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

Taiwanese shipping firm Yang Ming Marine Transport Corporation (Yang Ming) on Thursday (17 September) held a naming ceremony at the HD Hyundai Heavy Industries (HD HHI) shipyard in Ulsan, South Korea, for YM Weight, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI. 

Mrs. Chiu-Lien Lin, the spouse of Administrative Deputy Minister of Transportation and Communications Mr. Kuo-Shian Lin, was invited as the Godmother to officially name the vessel and perform the ceremonial cord-cutting, wishing the ship smooth sailing and full loading on all future voyages. 

This series of vessels built by HD HHI has a length overall (LOA) of 364.97 meters, a breadth of 51 meters, and a capacity of approximately 15,600 TEU. 

The vessels are equipped with high-pressure dual-fuel main engines that run on both LNG and low-sulphur fuel oil, along with integrated navigational information, equipment monitoring, broadband maritime satellite systems, and multiple energy-saving systems to enhance operational efficiency and navigational safety. 

YM Weight, the fourth vessel in the series, is jointly classed by CR and the American Bureau of Shipping (ABS), bringing international classification expertise and capabilities to safeguard the safety and technical compliance of next-generation LNG dual-fuel vessels. 

Furthermore, following proactive underwater noise measurements, the vessel has achieved two industry firsts by receiving the Underwater Noise (UWN) notation from ABS and the Underwater Radiated Noise (URN) notation from CR. The dual recognitions underscore Yang Ming’s commitment to mitigate operational impact on marine life and sustainable development. 

In addition to expanding its next-generation fleet and strengthening its core shipping business, Yang Ming has continued to strengthen professional training for seafarers operating alternative-fuel vessels. 

Yang Ming’s senior Captain Ming-Yeong Pan will serve as the delivery captain of ‘YM Weight’. Captain Pan is the first seafarer in Taiwan to receive the Advanced Training Certificate under the International Code of Safety for Ships Using Gases or Other Low-flashpoint Fuels (IGF Code), Certificate No. 0001, issued by the Maritime and Port Bureau, MOTC. 

To date, 148 Yang Ming officers have completed advanced IGF Code training and will progressively undertake onboard training aboard LNG-fueled vessels and practical alternative-fuel bunkering training. 


Photo credit: Yang Ming Marine Transport
Published: 18 September, 2026

Continue Reading

Ammonia

DNV: Existing ammonia shipping and safety expertise key to scaling new supply chains

As ammonia trade grows, decades of shipping and safety experience will be vital to scaling new supply chains , says Martin Cartwright, Global Business Director of Gas Carriers & FSRUs at DNV.
Admin

Published

on

By

DNV: Existing ammonia shipping and safety expertise key to scaling new supply chains

Martin Cartwright, Global Business Director of Gas Carriers & FSRUs at DNV highlighted that existing shipping experience in transporting ammonia as a cargo could provide a foundation for the development of larger-scale ammonia energy supply chains, but maintaining safety standards across new vessels, ports and terminals will be critical:

Few maritime sectors are watching the energy transition as closely as the gas carrier market. While decarbonization remains a powerful driver, recent geopolitical developments have also reinforced the importance of energy security and supply diversification. In that environment, ammonia is resurfacing as a means of transporting low-carbon energy between regions and connecting future production centres with energy-importing markets. 

Across East Asia, demand for blue and green ammonia is steadily taking shape as governments and industry seek pathways to decarbonization while seeking more diverse and resilient energy supplies. Countries such as Japan, South Korea, Singapore and Taiwan are exploring how ammonia, long established as a feedstock for fertilizer and other industrial products, can contribute to future energy needs, while producers in India, the Middle East, the USA and elsewhere are developing projects aimed at serving this demand. Similar policy and industrial drivers are emerging in Europe, although the dynamics differ between regions. The result is the gradual emergence of new trade routes and a global value chain built around ammonia production, transportation, and consumption, driving demand for the vessels needed to connect supply with demand.

India’s role in this story is becoming increasingly important. The country is progressing major green ammonia initiatives and positioning itself as a future export hub, supported by partnerships with prospective import markets in East Asia. Recent plans to develop green corridors supporting large-scale ammonia production for export to Japan and South Korea illustrate how rapidly these supply chains are evolving.

Of course, the development of this market has not been entirely straightforward.

Over the past year, several announced ammonia projects have been delayed, scaled back or cancelled altogether. Geopolitical uncertainty, changing economic conditions, and evolving policy frameworks have all influenced investment decisions. DNV analysis shows that projected ammonia production capacity has recently declined substantially compared with earlier expectations, reflecting a more cautious market outlook than many anticipated just a few years ago.

 Yet these developments should be viewed as a recalibration rather than a reversal. While some projects have been delayed or scaled back, governments continue to develop import strategies, infrastructure investment is advancing, and producers remain committed to serving future export markets. The long-term demand drivers remain intact.

 As production and demand centres become geographically separated, maritime transportation becomes essential to linking the two. DNV analysis suggests seaborne trade of ammonia as an energy carrier could reach around 120 million tonnes annually by 2050, approaching the scale of today’s LPG trade. If realized, this would create one of the most significant new maritime commodity trades in decades.

The timing and ultimate scale of that growth along with selecting the right vessel capacity remains challenging, but the direction of travel is increasingly clear. 

However, vessels are only one part of the equation.

As ammonia trade volumes grow, transportation capacity will need to be matched by investment throughout the value chain, including export terminals, import infrastructure, storage facilities and supporting logistics networks. The success of the ammonia market will depend on the industry’s ability to expand this ecosystem in step with growing demand.

The good news is that shipping is starting from a position of strength. Ammonia has been transported safely as a cargo for decades, supported by established regulations, operating procedures, and industry expertise.

Scaling volumes requires the application of existing knowledge and experience across a larger network of vessels, ports, terminals, and supply-chain partners. As new trade routes emerge between production hubs such as India and demand centres in East Asia, maintaining consistent safety standards and operational excellence will remain essential.

Safety will continue to be a central consideration as this market develops. Ammonia’s toxicity requires specialized handling procedures, appropriate vessel design, gas detection systems, crew competence and robust emergency-response arrangements. These measures are already well understood within the gas sector and provide a strong foundation for future growth. The priority now is ensuring that this expertise scales alongside the market itself.

Encouragingly, progress is already being made. Across Asia, the industry is moving beyond feasibility studies towards practical implementation. New vessel projects, bunkering trials, port developments and supply-chain partnerships are helping build the experience that will be required for larger-scale deployment in the future.

The growing demand for low-carbon ammonia in East Asia is helping establish entirely new energy trade flows, encouraging investment in production hubs such as India and creating demand for the ships and infrastructure needed to connect them.

The pace of development may vary, and setbacks are inevitable in any large-scale energy transition. But the broader trend remains clear. As ammonia increasingly assumes a role as a globally traded energy commodity, demand for ammonia transportation will continue to grow.

For the maritime industry, the opportunity is significant. The challenge now is ensuring that shipping capacity, terminals, storage infrastructure, and operational experience scale in step with growing demand.


Photo credit: DNV
Published: 18 September, 2026

Continue Reading

Trending