Connect with us

Biofuel

ENGINE on Biofuel Bunker Snapshot: Conventional prices push B30 prices higher

Rotterdam’s B30-VLSFO and B30-LSMGO sharply higher on the week; Antwerp’s bio-bunker sales increase 89% on quarter; Nippon Biofuel selected for Japan-backed Jatropha biofuel project.

Admin

Published

on

ENGINE on Biofuel Bunker Snapshot: Conventional prices push B30 prices higher

Once a week, bunker intelligence platform ENGINE will publish a snapshot of biofuel bunker prices in Europe, Fujairah and Singapore. The following is the latest snapshot:

  • Rotterdam’s B30-VLSFO and B30-LSMGO sharply higher on the week
  • Antwerp’s bio-bunker sales increase 89% on quarter
  • Nippon Biofuel selected for Japan-backed Jatropha biofuel project

ARA and Europe

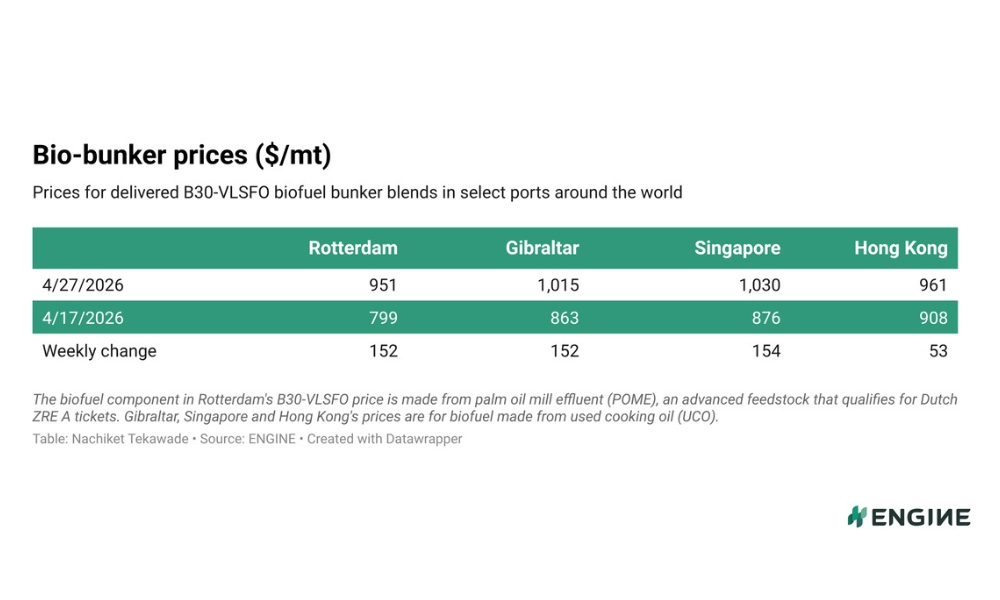
Rotterdam’s B30-VLSFO (POMEME) grade has surged around $152/mt through the past week, since Friday 17 April.

This rise was mainly supported by the surge in conventional VLSFO price. VLSFO price in Rotterdam has gained by around $119/mt in the same duration.

Meanwhile, Prima Markets assessed POMEME feedstock price gained by just $9/mt in the past week.  

A $163/mt gain in Rotterdam’s conventional LSMGO price has also pushed up the port’s B30-LSMGO blend price by around $185/mt in the past week.

Separately, sales of bio-bunkers at the Port of Antwerp-Bruges in first quarter 2026 have rebounded strongly by around 89% to 21,000 mt, from a low of 11,000 mt reached in Q4 2025.

Despite the rise, Antwerp’s biofuel sales significantly trail Rotterdam’s bio-bunker sales which were at 112,000 mt in the first quarter, despite a 33% drop.

Meanwhile, Gibraltar’s B30-VLSFO (UCOME) price gained by around $152/mt during the past week. Its price premium over the port’s conventional VLSFO grade has gained by $50/mt in the same period.

Securing biofuel deliveries in the ARA and in the Gibraltar, strait requires around 7-10 days of lead time, a trader said.

Asia

Singapore’s B30-VLSFO (UCOME) price has gained by around $154/mt through the last week since 17 April.

The port’s conventional VLSFO price has also increased around $121/mt during the same period.

The blend’s price premium over the conventional price has increased by around $33/mt in the past week to $267/mt. The premium has widened around $100/mt in the last month.

Most suppliers have now restarted biofuel supplies after pausing them early in the Middle East conflict to take advantage of the high VLSFO premiums.

Hong Kong’s B30-VLSFO price has increased by just $53/mt in the past week.

Consequently, Hong Kong’s blend is now offered at a $69/mt discount to Singapore, compared to a $32/mt premium seen on 17 April.

In other biofuel news this week:

Seagate Corporation, a subsidiary of Kawasaki Kisen Kaisha (K Line), said it has launched a tugboat fitted with an onboard biofuel blending system at the Kanagawa Dockyard in Japan.

Nippon biofuel has been selected for a Japanese government-backed project to build and demonstrate a production and supply model for jatropha-based marine biofuel from Africa to Asia. Under the project, Nippon Biofuels targets to 400,000 mt/year of biofuel by 2032 from jatropha cultivated in Mozambique and Ghana.

By Nachiket Tekawade


Photo credit and source: ENGINE
Published: 28 April, 2026

Continue Reading

Engine

Polaris Shipping orders WinGD engines capable of running on methanol, ethanol

Ability to operate on either fuel gives Polaris Shipping greater flexibility to respond to changes in fuel availability, pricing and regulatory requirements over the vessels’ operating lives.

Admin

Published

on

By

Polaris Shipping orders WinGD engines capable of running on methanol, ethanol

Swiss marine power company WinGD on Thursday (10 September) said it has won a contract that will give Polaris Shipping true fuel flexibility for its future Newcastlemax fleet with an order of four X72DF-M-1.0 engines that can operate on methanol and ethanol. 

The ability to operate on either fuel gives Polaris Shipping greater flexibility to respond to changes in fuel availability, pricing and regulatory requirements over the vessels’ operating lives and is a key benefit of WinGD’s alcohol-fuel engine platform.

The WinGD engines will power four 210,000 DWT Ore carriers being built for Polaris Shipping at Qingdao Beihai Shipbuilding Heavy Industry Co in China, with delivery scheduled for 2031. 

Dr. Carmelo Cartalemi, Head of Strategic Marketing, WinGD, said “Shipowners are looking for flexible solutions to help them meet their decarbonisation goals without compromising on reliability, safety or financial stability. 

“Our alcohol-fuel engine platform enables ships to operate on either ethanol or methanol, giving shipowners and managers the option to select the fuel that best fits their operational and commercial requirements. With fuel markets and regulations continuing to evolve, that flexibility can be a valuable asset over the lifetime of a vessel.”

The X72DF-M1.0 can run on methanol and ethanol. This provides flexibility between the two fuels, while maintaining compliance with the regulatory requirements applicable to both fuels.

WinGD will also provide dedicated service and lifecycle support for the new alcohol fuels, helping shipowners and operators build familiarity with the technology, optimise operation and maintenance, and adopt methanol and ethanol propulsion in a safe and economically sustainable way

Polaris Shipping, said: “Fuel availability and economics will continue to evolve over the lifetime of these vessels. Selecting an engine platform that gives us access to both methanol and ethanol means we can provide to our charter a greater choice in how the ships are operated in the future, rather than having to predict today which fuel will be most competitive in the years ahead. 

“We’re investing for the long-term, and this engine choice gives us the confidence to do that.”

The order adds to WinGD orderbook of alternative fuel engine technology, which now spans LNG, methanol, ethanol and ammonia. Beihai Shipyard is also working with WinGD on the installation of its ammonia-fuelled engine for CMB TECH’s newbuild 210,000 dwt dry bulk carriers. 


Photo credit: WinGD
Published: 11 September, 2026

Continue Reading

Technology

Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE

‘We are now working with industry on the next phase, trialling capabilities to further strengthen the integrity and quality of bunker data shared between stakeholders and MPA,’ says David Foo.

Admin

Published

on

By

MPA’s Deputy Chief Executive (Ops & Tech), Mr David Foo

Editor’s Note [11 September 2026]: Photo has been updated. 

Secure systems, trusted data and reliable digital services are becoming as important to maritime operations as physical infrastructure, said Mr David Foo, Deputy Chief Executive (Operations & Technology), Maritime and Port Authority of Singapore (MPA), on Thursday (10 September). 

In his opening keynote speech at APPEC 2026 Shipping And Bunker Conference, Foo said OCEANS-X, Digital Bunkering and the Maritime Digital Twin are enabling trusted data sharing, better operational planning and the testing of new digital solutions.

Foo said since 2025, digital bunkering has strengthened the efficiency and transparency of bunker operations. 

“We are now working with industry on the next phase, trialling capabilities to further strengthen the integrity and quality of bunker data shared between stakeholders and MPA.” he said.

He also said MPA is taking a forward-looking approach to the energy transition.

“Over the coming decades, we are likely to see the most diverse marine fuel mix in shipping’s history. There may not be a single fuel of the future.”

“Our role as a global bunkering hub is therefore not to determine which fuel will prevail. Our role is to ensure that whichever fuels the industry adopts, Singapore is ready – with the infrastructure, standards and operational capabilities to support them.”

Foo said MPA is making concrete progress across the major alternative fuel pathways with the issuance of methanol bunkering licences and the commencement of methanol bunkering operations. 

“For ammonia, we are developing the regulatory and operational frameworks needed to support future commercial deployment. We are also facilitating greater use of sustainable biofuels,” he said.

At the same time, MPA continues to expand its LNG bunkering ecosystem, with additional licences issued this year. 

“This will broaden supply options as more LNG-fuelled vessels enter the global fleet. We have also just updated our LNG standards, while maintaining the high standards of safety and reliability that underpin Singapore’s reputation as a trusted bunkering hub,” Foo added.

Related: MPA Chief Executive: Port of Singapore begins digital bunkering initiative today
Related: Singapore: Golden Island, GET, and PetroChina to receive methanol bunkering licences
Related: Singapore: Equatorial Marine Fuel among eight selected for new LNG bunkering licences
Related: Singapore strengthens LNG bunkering framework with new SS 727 standard


Photo credit: Swapnil Bapat on Unsplash
Published: 10 September, 2026

Continue Reading

EU ETS

KPI OceanConnect on EUAs: September is the deadline, but strategy is the bigger story

With 100% EU ETS exposure for 2026 emissions, an alternative fuels strategy can no longer be treated separately from carbon management, says Jesper Sørensen.
Admin

Published

on

By

Jesper Sørensen, Global Head of Alternative Fuels and Carbon Markets at KPI OceanConnect

Jesper Sørensen, Global Head of Alternative Fuels and Carbon Markets of KPI OceanConnect, on Wednesday (8 September) wrote that while the 30 September deadline to surrender EUAs is approaching, managing exposure to EU ETS is about more than how and when allowances are purchased.

He said fuel choice and alternative fuels strategy should also form part of companies’ broader carbon-management approach: 

EUAs: EU ETS surrender deadline highlights rising maritime carbon costs, as higher compliance obligations and EUA exposure increase the strategic importance of biofuels, fuel procurement and integrated carbon management ahead of full shipping inclusion in the EU ETS from 2026.

As the 30 September EU ETS surrender deadline approaches, the immediate message for shipowners, operators and charterers is straightforward: make sure your verified emissions position is understood, your exposure is calculated, and your allowance needs are settled in good time.

But this year’s deadline should also be seen as something more than an annual compliance event. It is a reminder that carbon costs are becoming an increasingly important part of vessel operating economics, and that the most effective response is not only to buy EUAs but also to think more strategically about how fuel choices influence overall compliance exposure.

This matters because the cost of the same level of emissions is rising even before we consider market volatility in EUA prices. The reason is the phase-in of the maritime EU ETS. For 2024 emissions, shipping companies were required to surrender allowances for 40% of in-scope CO₂ emissions. For 2025 emissions, that rises to 70%. From 2026 emissions onwards, the obligation moves to 100%.

In other words, even if the EUA price were to remain unchanged, the compliance bill for the same emissions profile becomes materially larger. That is an important shift. It means carbon exposure is no longer something to address only at the end of the reporting cycle. It increasingly needs to be considered when making fuel procurement and voyage-planning decisions.

The EUA market itself reinforces that point. Price volatility remains a feature of the market, and that makes planned procurement more important than ever. The objective is not to predict the perfect entry point. It is to understand the exposure, settle the near-term obligation in a timely manner, and develop a strategy to reduce future risk. But managing EUA exposure is increasingly about more than how and when allowances are purchased.

Over recent months, the economics of biofuels, particularly B100, have become increasingly compelling in several trading scenarios. When assessed only on a headline fuel price basis, the picture can appear mixed. But when viewed through the lens of total compliance cost, the economics can look materially different.

Qualifying sustainable biofuels can help reduce EU ETS exposure by reducing the number of allowances that need to be surrendered, while also improving compliance under FuelEU Maritime. In other words, a well-structured biofuel strategy can support compliance across both regulatory regimes simultaneously.

It does not follow that biofuel is automatically the most efficient solution for every vessel, voyage or trading pattern. In many cases, purchasing EUAs will remain the right answer. In others, alternative fuels can reduce exposure across multiple regulatory frameworks and materially change the overall economics.

That is why the September surrender deadline should be viewed as both a compliance event and a useful point to look forward.

With 100% EU ETS exposure for 2026 emissions, an alternative fuels strategy can no longer be treated separately from carbon management. Fuel procurement, EUA procurement, and FuelEU compliance increasingly need to be considered together before the bunker decision is made, rather than after emissions have already occurred.


Photo credit: KPI OceanConnect
Published: 10 September, 2026

Continue Reading

Trending