Port & Regulatory
Gard: Overview of IMO interim emission measures
Neil Henderson Senior Executive, Gard’s Industry Liaison, provides an overview of the interim measures agreed at MEPC 83 and outlines some of the reactions from the industry.

Maritime protection and indemnity (P&I) club Gard recently published an insight by Neil Henderson Senior Executive, Gard’s Industry Liaison, providing an overview of the interim measures agreed at MEPC 83 and outlined some of the reactions from the industry:
On 11 April 2025 the IMO announced that agreement had been reached by the member states at MEPC 83 on interim measures as part of the IMO’s 2023 greenhouse gas (GHG) strategy to achieve net-zero by or around 2050.
The proposed new chapter 5 to MARPOL Annex VI provides that the GHG intensity of all energy used by vessels – referred to as the GHG Fuel Intensity (GFI) – is to be progressively reduced.
The measures will start from 1 January 2028 and apply to vessels of 5,000 gt or above.. There are two reduction trajectories: the more modest ‘Base’ target and the more ambitious ‘Direct Compliance’ target. These measures are intended to align with the IMO’s ‘base’ and ‘striving for’ GHG reduction targets
If the vessel meets the more ambitious Direct Compliance target, the shipowner will receive surplus units (SUs). These can either be banked or transferred to other shipowners. By contrast, if the vessel fails to meet the required targets, the shipowner will have to purchase remedial units (RUs) at differing cost-levels, depending upon the degree of non-compliance.
The revenues from the RUs will be transferred to the IMO Net-Zero Fund, which will be managed by the IMO. This is intended, in part, to incentivise the use of zero and near-zero (ZNZ) fuels. The financial level of reward will be determined by 1 March 2027.
The MEPC will reconvene in October to adopt the proposal. This requires a two-thirds majority of the 108 Member State parties to MARPOL Annex VI, a total of 73 states. The majority voting in April saw 63 in favour, 16 opposed, and 24 abstentions; so, work will have to be done before October to secure the necessary additional support.
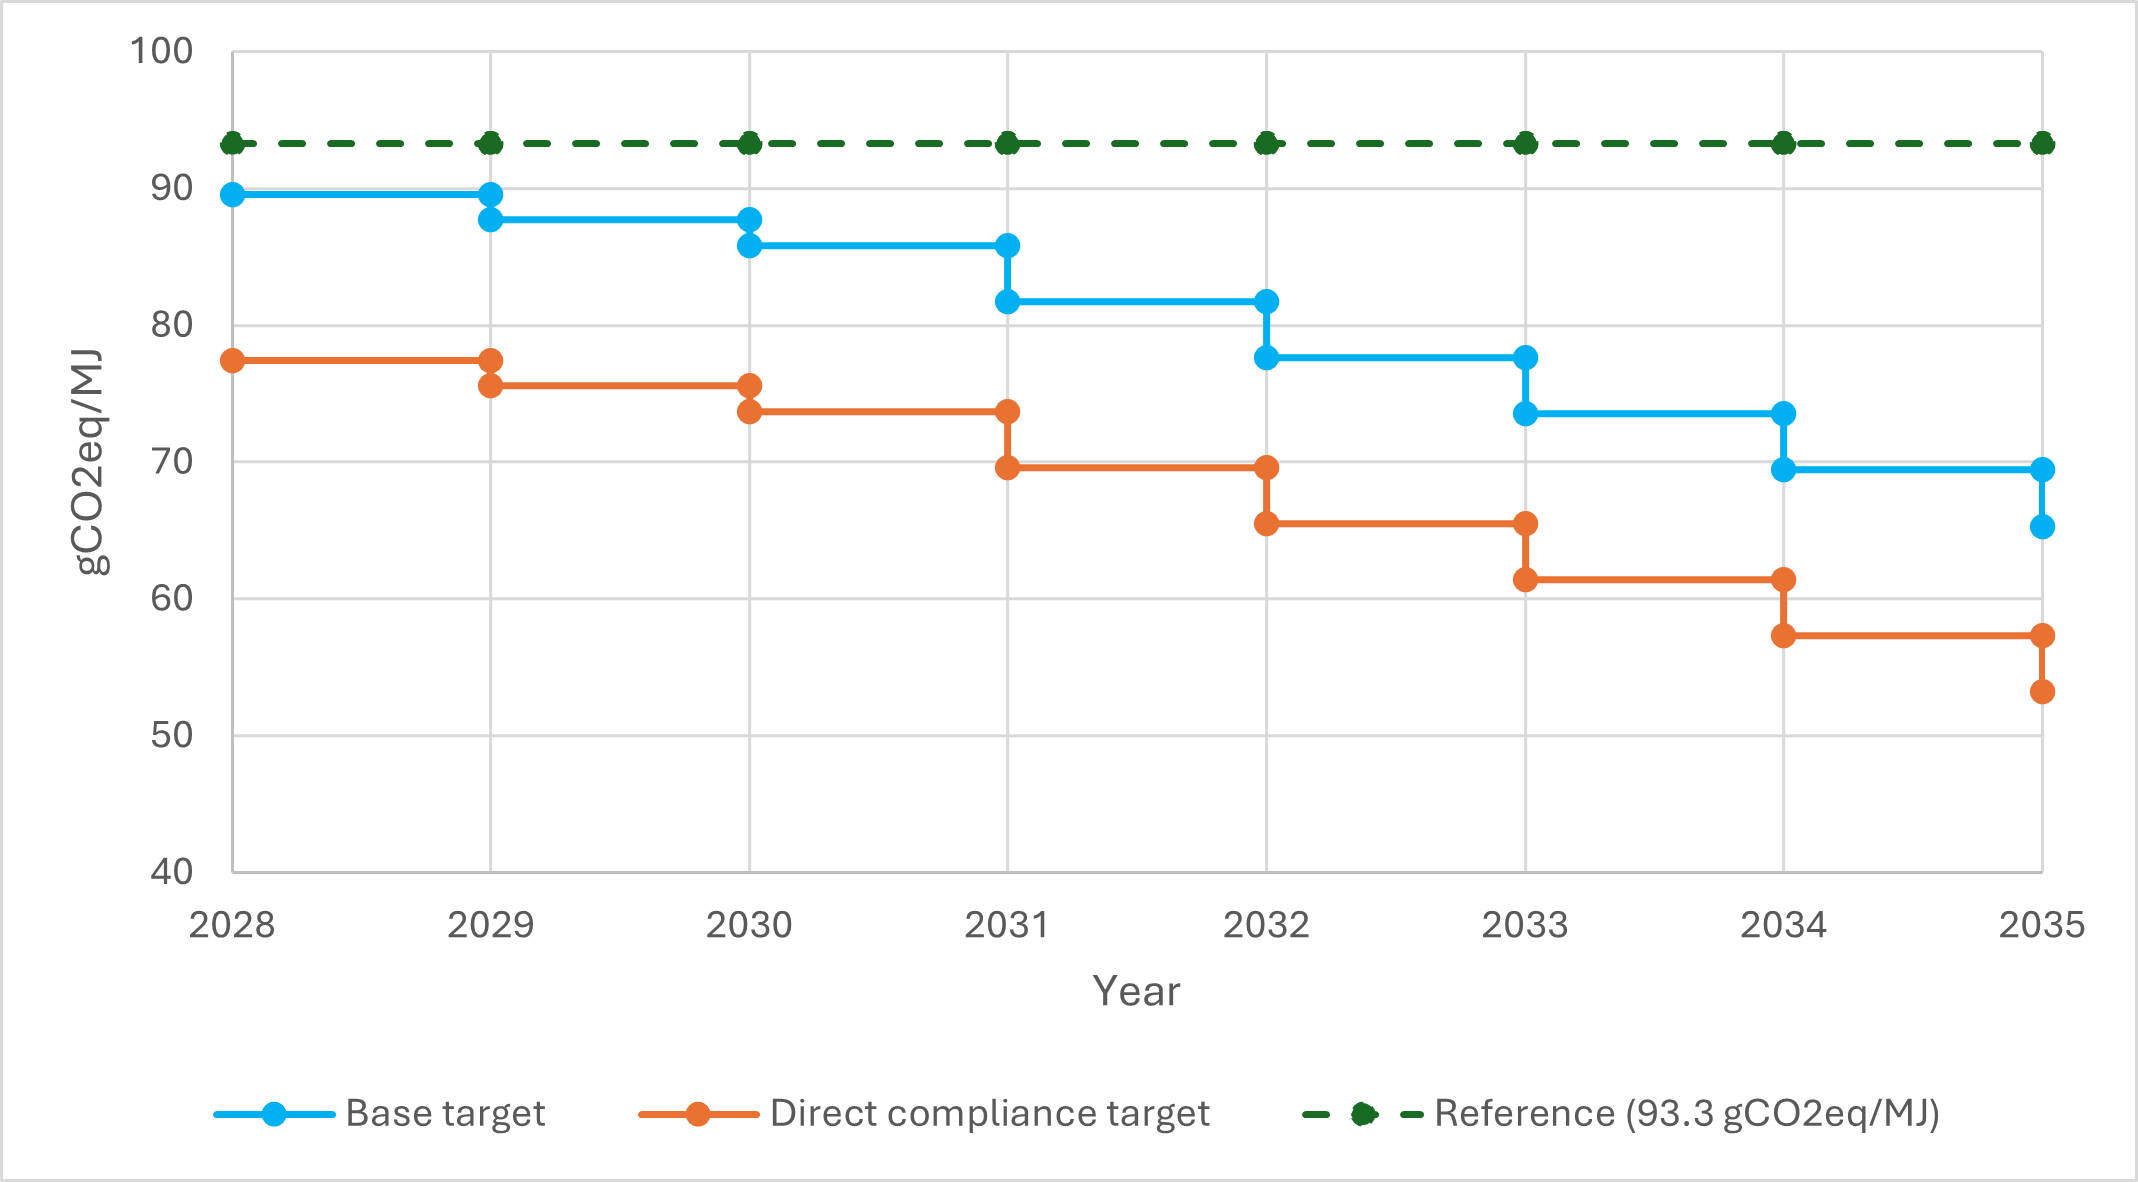
Fig.1 Trajectory for Base and Direct Compliance targets (2028-2035)
The basics of the GFI
The GHG Fuel Intensity (GFI) mid-term measures agreed are similar to but broader than the FuelEU Maritime Regulation. We will explore the similarities and differences in a subsequent article.
The GFI is the GHG intensity of the energy used onboard a ship. This comprises the energy from the fuel, from other sources, e.g. wind-assisted propulsion, and savings in emissions from technology such as carbon capture. The GFI is a measure of the grams of CO2 or CO2 equivalent, i.e. methane, nitrous oxide, per megajoule of energy; the unit is gCO2e/MJ. This is the same as the measure used for FuelEU Maritime.
Each energy source, whether it be fuel or alternative energy, is given a well-to-wake (WtW) figure for the GHG emissions. These are the GHG emissions throughout the lifecycle of the energy source: production – transportation – consumption onboard. The GFI figure for each fuel or energy source will be calculated by an IMO-recognised Sustainable Fuel Certification Scheme.
Starting from 1 January 2028 there are two trajectories of reductions in the permitted GFI levels as compared to a 2008 starting figure. See Fig.1 above:
The ‘Base’ target which tracks the IMO’s base targets of a 20% reduction in GHG emissions by 2030 and 70% reduction by 2040; and
The ‘Direct Compliance’ target. This tracks the ‘striving for’ targets of 30% and 80% reductions, respectively.
The two target trajectories have been agreed up to 2035 only, other than a single Base target reduction of 65% for 2040. The targets for the period 2026 to 2040 must be agreed by 1 January 2032.
By March each year, the shipowner will report the weighted average GHG intensity of the energy used onboard the vessel over the previous calendar year. This is the vessel’s Attained GFI. The shipowner will also report the vessel’s annual GFI Compliance Balance. This is the difference between the Direct Compliance target and the vessel’s Attained GFI, multiplied by the total energy used that year. It will be a positive or negative figure, measured in tonnes of CO2eq.
The reporting obligation applies to all vessels of 5,000gt or above, subject to several exceptions: ships operating only in the waters of their flag state; ships not using mechanical propulsion; FPSOs, FSUs, drilling rigs and semi-submersible vessels.
Note: The full article by Gard can be viewed here.
Photo credit: Chris Pagan on Unsplash
Published: 2 June, 2025
Decarbonisation
DNV: New research shows how regulation could reshape shipping
DNV summarizes findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness.
Classification society DNV on Thursday (24 September) released a new article summarizing findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness:
Shipping’s energy transition has entered a new phase. The technology options are increasingly well understood. LNG, methanol, biofuels, wind-assisted propulsion, and emerging ammonia solutions are no longer concepts but commercial realities. Yet despite this progress, shipowners face a more difficult challenge than ever: making investment decisions amid unprecedented regulatory uncertainty.
The 2026 edition of DNV’s Maritime Forecast to 2050 argues that uncertainty itself is now becoming one of the most important drivers of fleet strategy.
“Decisions taken today on vessel design, retrofits, and fuel capability will determine competitiveness for decades, while the outcome of ongoing regulatory negotiations could significantly reshape the economics of shipping’s energy transition,” says Øyvind Sekkesæter, Senior Consultant at DNV and lead author of this year’s report. “Maritime Forecast to 2050 aims to assist that decision-making with our latest core insights and case study examples.”
Four regulatory scenarios could shape shipping very differently
This year’s Maritime Forecast takes a scenario-based approach, presenting four possible regulatory futures for shipping. These range from the full adoption of IMO’s initially approved Net-Zero Framework (NZF) to its rejection and prolonged political gridlock, while also exploring several intermediate outcomes, including a delayed or revised NZF and scenarios where regional regulations play a more prominent role in driving decarbonization. Rather than predicting which outcome is most likely, the scenarios illustrate how different regulatory futures could affect fuel demand, energy-efficiency uptake, investment signals, and fleet competitiveness.
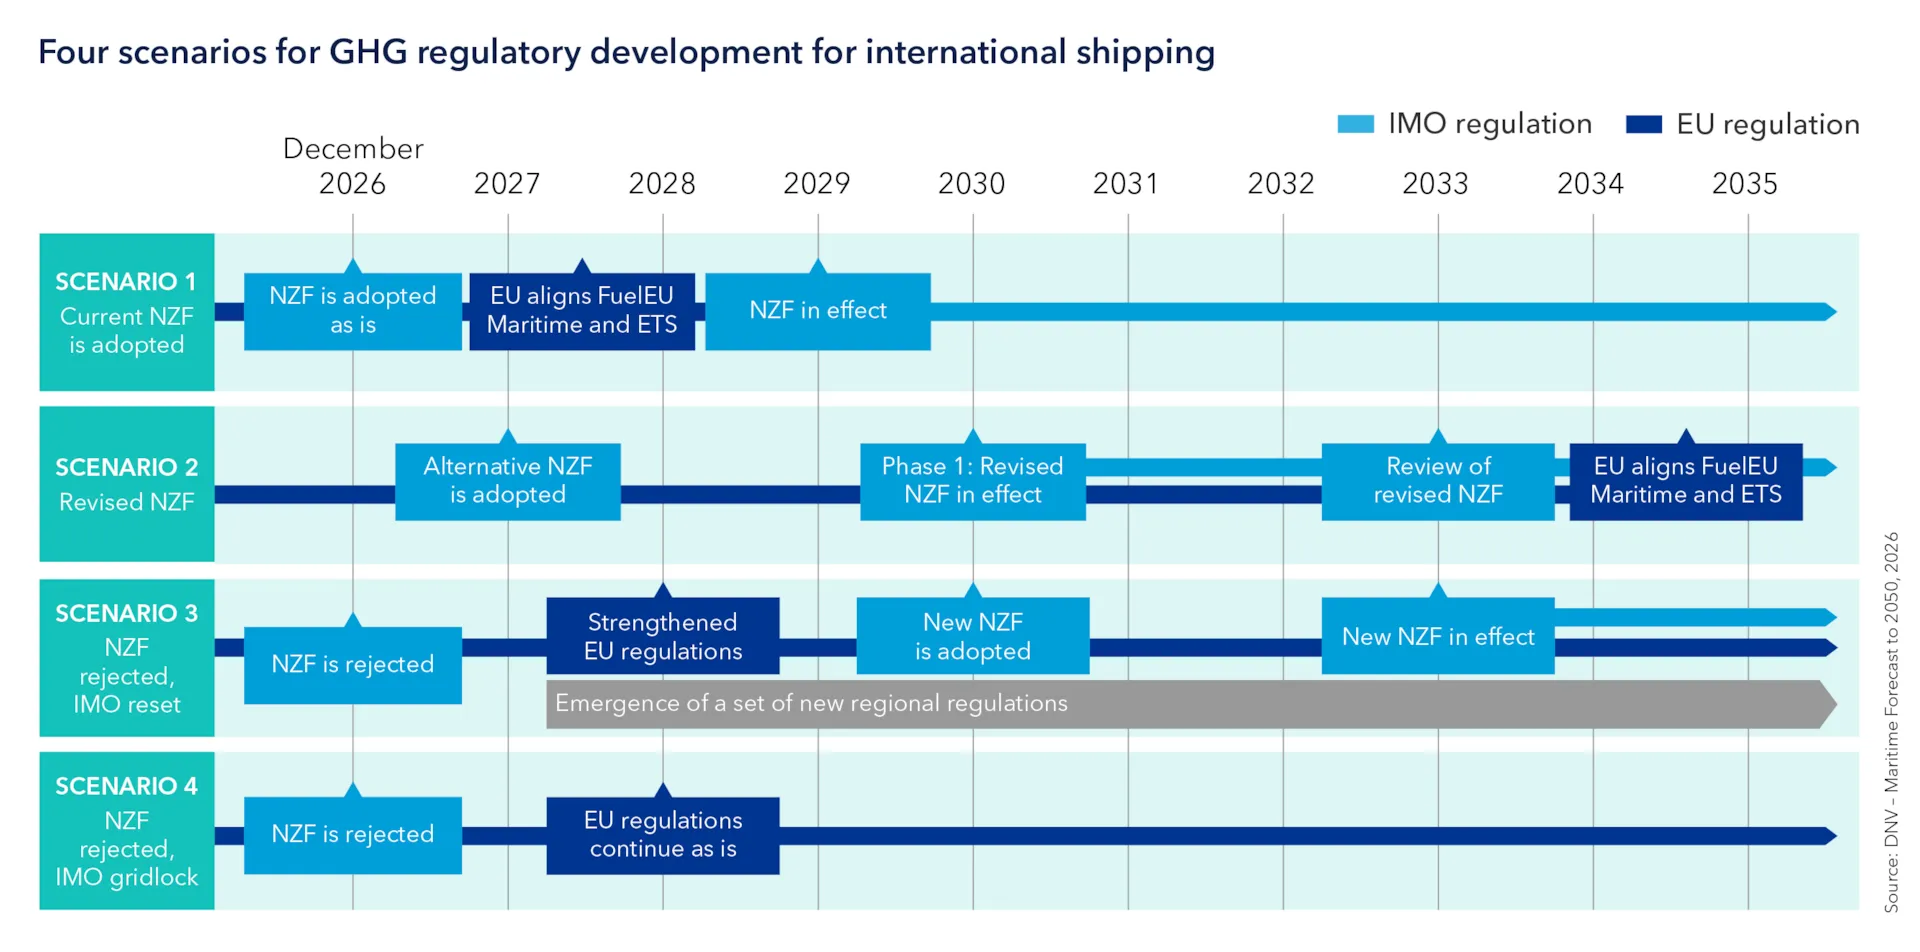
Stronger global regulation accelerates demand for low-GHG fuels and increases the attractiveness of energy-efficiency measures, while the absence of such regulation slows market development. The result is a transition whose pace may vary significantly depending on future policy decisions.
“For shipowners, this means the challenge is no longer identifying a single fuel pathway that fits the operational profile of their fleet. Instead, it is preparing fleets that remain competitive across multiple possible futures,” Sekkesæter concludes.
Tapping the fleet’s efficiency potential
Fully realizing the fleet’s energy-saving potential requires improvements not only to newbuilds but also to existing ships through retrofits.
Installing energy-saving devices during scheduled dry-docking can be a highly cost-effective decarbonization strategy, as illustrated by the Maritime Forecast’s case study of a hypothetical 15-year-old 5,000 TEU containership (built in 2013).
This envisages USD 2.35 million being invested to retrofit the ship with hydrodynamic enhancements including a bow retrofit, propeller upgrade, and a propeller boss cap fin.
The vessel can achieve estimated fuel savings of around 16% under the modelling assumptions. Evaluating the investment under three price scenarios for low sulphur heavy fuel oil (LSHFO) results in payback periods from 1.4 years to 4.2 years.
Note: The full Maritime Impact article by DNV can be found here.
Photo credit: DNV
Published: 25 September, 2026
Newbuilding
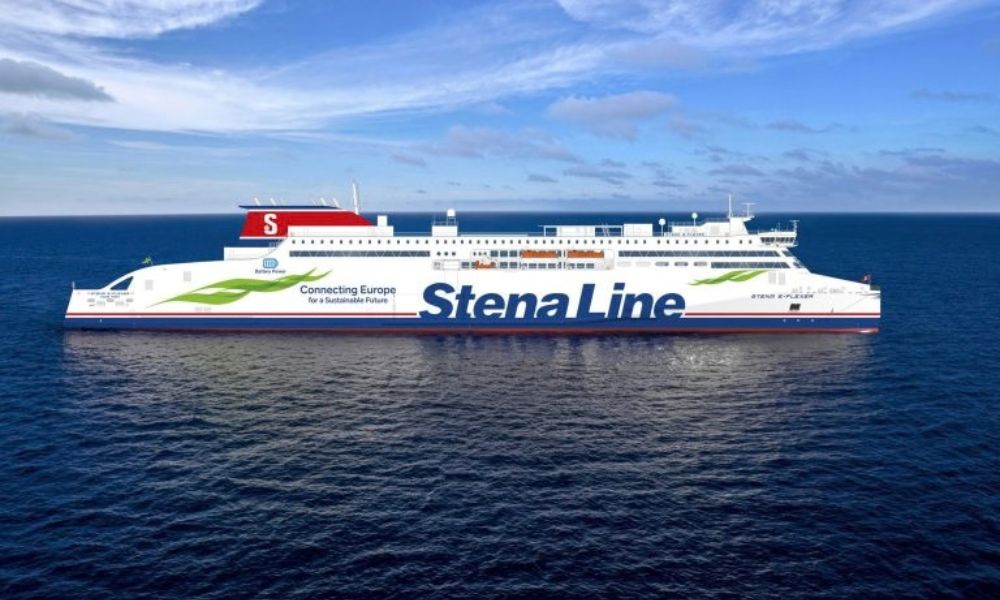
Stena Line orders two new hybrid ferries for Sweden – Denmark route
Vessels will feature the latest hybrid propulsion technology, allowing them to operate on both conventional fuel and electricity and will be prepared for conversion to 100% electric operation.
Alternative Fuels
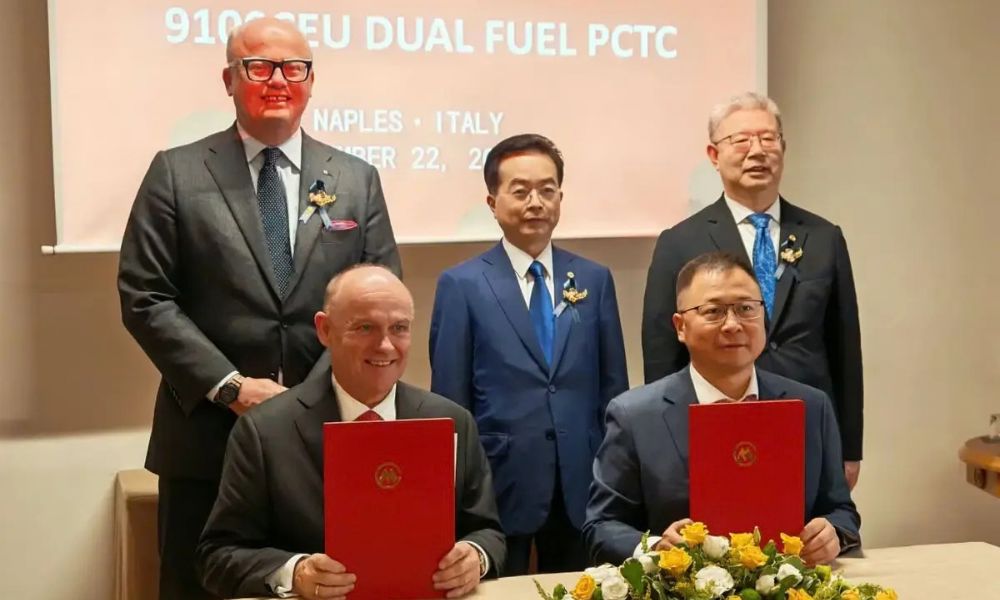
Höegh Autoliners orders six more ammonia, methanol-ready Aurora class PCTCs
Höegh Autoliner inked a contract with China Merchants Group for six additional Aurora class PCTCs, which will be built by China Merchants Heavy Industry (Jiangsu) and delivered between 2029 and 2031.

OUR INDUSTRY PARTNERS

Shell Singapore charged over Pulau Bukom oil leaks, reporting delays

MPA probes Singapore Strait collision involving fishing vessel, bulk carrier

TFG Marine deploys first MFM-equipped bunker barge in Jamaica

Seascale Energy names Gaetan Perret co-CEO as Olivier Josse prepares to retire

DNV: New research shows how regulation could reshape shipping

Stena Line orders two new hybrid ferries for Sweden – Denmark route

ENGINE: Americas Bunker Fuel Availability Outlook (24 Sep 2026)

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

High Court of Singapore issues winding up order against Hengli Petrochemical International

APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists

APPEC 2026: Panellists navigate maritime decarbonisation and alternative marine fuel strategies

LDA’s methanol-powered “Spirit of Toulouse” gets Norsepower rotor sail in Shanghai

Goldwind green methanol facility completes trial production, ships first 500 mt

Singapore: Bunker fuel sales down by 4% on year in August 2026
-
 Winding up2 weeks ago
Singapore: Marine fuel testing firm CCIC Singapore faces winding up application
-
 Winding up2 weeks ago
High Court of Singapore issues winding up order against Hengli Petrochemical International
-
 Technology2 weeks ago
APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists
-
 Alternative Fuels2 weeks ago
APPEC 2026: Panellists navigate maritime decarbonisation and alternative marine fuel strategies
-
 Wind-assisted2 weeks ago
LDA’s methanol-powered “Spirit of Toulouse” gets Norsepower rotor sail in Shanghai
-
 Methanol2 weeks ago
Goldwind green methanol facility completes trial production, ships first 500 mt
-
 Alternative Fuels2 weeks ago
Singapore: Bunker fuel sales down by 4% on year in August 2026
-
 Bunker Fuel2 weeks ago
APPEC 2026: Equatorial and Kuwait Petroleum Corporation discuss Middle East bunker market dynamics