Connect with us

Bunker Fuel

ENGINE: Americas Fuel Availability Outlook (11 June 2026)

Tight prompt supply in Houston; Paranagua, Rio de Janeiro supply constrained; Punta Colorada targets higher throughput.

Admin

Published

on

RESIZED ENGINE Americas

The following article regarding bunker fuel availability in the Americas region has been provided by online marine fuel procurement platform ENGINE for post on Singapore bunkering publication Manifold Times:

  • Tight prompt supply in Houston
  • Paranagua, Rio de Janeiro supply constrained
  • Punta Colorada targets higher throughput

North America

In Houston, bunker demand has been steady over the past week, with prompt availability tight across all three conventional fuel grades. HSFO and VLSFO require lead times of 5–7 days, and LSMGO can be delivered by most suppliers within 4–5 days, a trader said.

At the Galveston Offshore Lightering Area (GOLA), operations are being conducted on a first-come, first-served basis and remain subject to weather conditions.

High seas are forecast for 14 June, which could impact bunker deliveries at the anchorage. Recommended lead times for all three conventional grades stand at 5–8 days this week.

In New York, bunker demand has softened this week, while variable fuel availability has resulted in unclear lead times, a trader said. HSFO and VLSFO are tight for prompt supply, with lead times of 6–8 days this week, while LSMGO is available within 3–5 days.

No backlog or bunker barge readiness issues have been reported. High wind gusts are forecast through 12 June, which could disrupt bunkering operations at the port.

The Atlantic hurricane season began on 1 June, though tropical cyclone risks across North America are currently low.

High pressure is expected to maintain stable conditions across the Gulf of Mexico and western Atlantic this week, reducing the likelihood of weather-related disruptions to bunker operations.

On the US West Coast, fuel availability across all three conventional grades is normal at the ports of Los Angeles and Long Beach. Recommended lead times for HSFO, VLSFO, and LSMGO stand at 7–10 days this week.

Latin America and the Caribbean

In Panama, bunker demand is strong, and fuel prices continue to be high, a trader said.

Availability is good at both Balboa and Cristobal, with recommended lead times of 3-4 days for VLSFO and LSMGO. HSFO requires slightly longer lead times of 4-5 days.

High wind gusts forecast in Balboa on 12-13 June could disrupt bunker operations. Deliveries are being carried out on a first-come, first-served basis, with priority given to vessels holding confirmed Panama Canal transit slots.

In Colombia, the ports of Santa Marta, Cartagena and Barranquilla have good availability of both VLSFO and LSMGO, with the earliest delivery dates available in 3-4 days, a source said.

Across the Caribbean, the remnants of Tropical Storm Cristina are forecast to move into the Bay of Campeche later this week, bringing increased showers and thunderstorms.

While the system has a low chance of further development, a low-end tropical storm cannot be completely ruled out. Elsewhere, dry air and wind shear are expected to suppress tropical development across much of the Caribbean.

In Freeport, Bahamas, bunkering conditions remain stable with no weather-related disruptions expected. Cruise ships continue to receive operational priority, which may influence bunker scheduling, a trader tells ENGINE.

Further south, St. Eustatius is expected to experience high wind gusts from 10-14 June, which could affect bunkering operations.

Deliveries are conducted at the anchorage, while cruise ships receive priority. Bunker barge operations may face weather-related delays.

Offshore Trinidad, high wind gusts and rough seas are forecast through 13 June, posing a risk of disruptions to offshore bunkering operations.

Deliveries are conducted while underway, and bunker barge delays are possible due to adverse sea conditions, a source said.

In Brazil, bunker availability varies by port. Santos is experiencing congestion, with VLSFO and LSMGO available in 5-8 days, although shorter lead times may be possible depending on stem size and price premiums, a source said.

Availability is normal in Rio Grande, Belem, and Vila do Conde, where both grades can be supplied within 4-6 days.

In contrast, Paranagua is facing tight availability, with the earliest delivery date currently 15 June. Availability is also tight in Rio de Janeiro, where bookings are being done under prior consultation and lead times remain uncertain, a trader said.

Bunker deliveries in Argentina’s Zona Comun continue despite rough weather conditions at the anchorage, a source told ENGINE.

Dense fog forecast through 12 June could disrupt operations. Deliveries are being carried out on a first-come, first-served basis.

VLSFO and LSMGO availability remains good, with typical lead times of 5-7 days.

Meanwhile, a major supplier is increasing the planned throughput capacity of its new crude export terminal at Punta Colorada from 550,000 b/d to 700,000 b/d.

According to Antares Ship Agency, the decision reflects current market dynamics and growing interest in diversifying crude supply sources. The higher capacity will be achieved through increased pumping rates and enhanced onshore infrastructure.

Once operational, the terminal is expected to handle up to 128 vessels annually, with each lifting around 200,000 barrels.

By Gautamee Hazarika


Photo credit and source: ENGINE
Published: 12 June, 2026

Continue Reading

Alternative Fuels

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

New fuels could reach around 60% of fleet energy consumption under a sufficiently strong carbon price signal, modelled at USD 700/tCO2e by 2050.
Admin

Published

on

By

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

With vessels operating for 25 to 30 years and only around 4% of the fleet renewed annually, newbuild decisions made over the coming decade will establish much of the engine capacity available in 2050, Global Centre for Maritime Decarbonisation said on Thursday (17 September). 

Yet having the capacity to consume a new fuel does not guarantee its uptake. Dual-fuel engines allow shipowners to switch between conventional fuels and the selected new fuel as economics and regulations evolve; continued fuel competitiveness is therefore critical to what vessels ultimately consume.

These are among the findings of Navigating the maritime fuel transition: How fuel economics, regulations, and fleet decisions shape the future bunkering landscape, based on a model jointly developed by the GCMD and Boston Consulting Group (BCG).

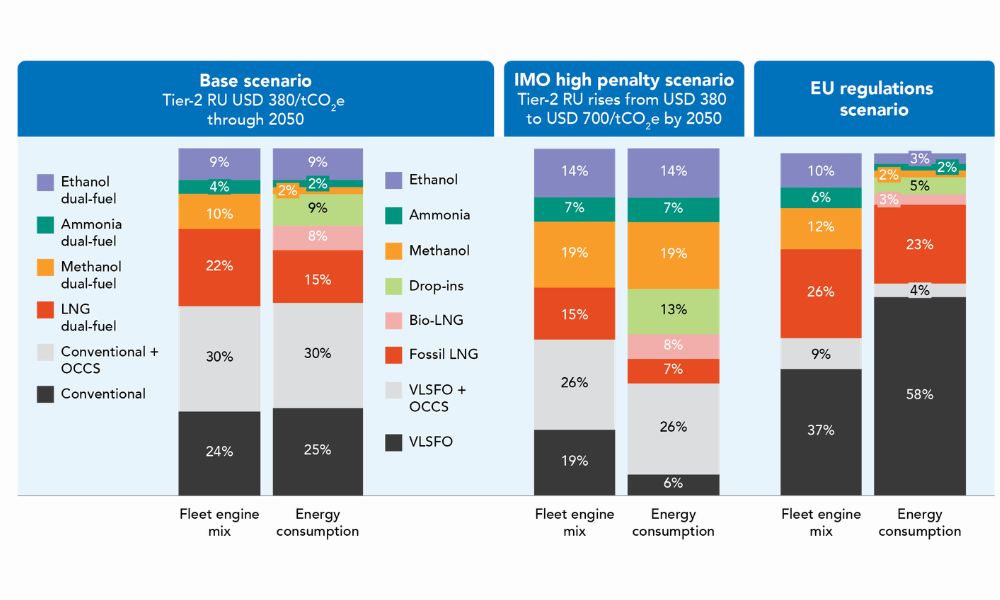
The model illustrates this dynamic in its base scenario. With the Tier-2 penalty under the IMO Net-Zero Framework held at USD 380/tCO2e through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity in 2050, but methanol represents just 2% of fleet energy consumption. With conventional fuels remaining more economical under this regulatory regime, methanol dual-fuel vessels continue to operate on fuels cheaper than methanol (Figure 1).

A global carbon price of USD 700/tCO2e materially changes the transition

The base scenario demonstrates how fuel economics can limit uptake even when vessels have the capacity to use new fuels. This picture changes if the IMO Tier-2 penalty rises to USD 700/tCO2e by 2050, at which point new fuels, including dropins, reach approximately 61% of fleet energy consumption (Figure 1).

By contrast, EU regulations alone will not drive a marked global shift, as they cover only around 20% of international shipping’s energy demand.

Overall cost of using e-methanol and e-ammonia is near parity

While a stronger global carbon price can accelerate the shift towards new fuels, the model does not point to a clear cost winner between e-methanol and e-ammonia.

E-ammonia’s production cost advantage is largely offset by higher logistics costs arising from its toxicity, including specialised crew training, larger exclusion zones, and more complex bunkering. As a result, the overall cost (Figure 2) of using e-ammonia and e-methanol is near parity through to 2050.
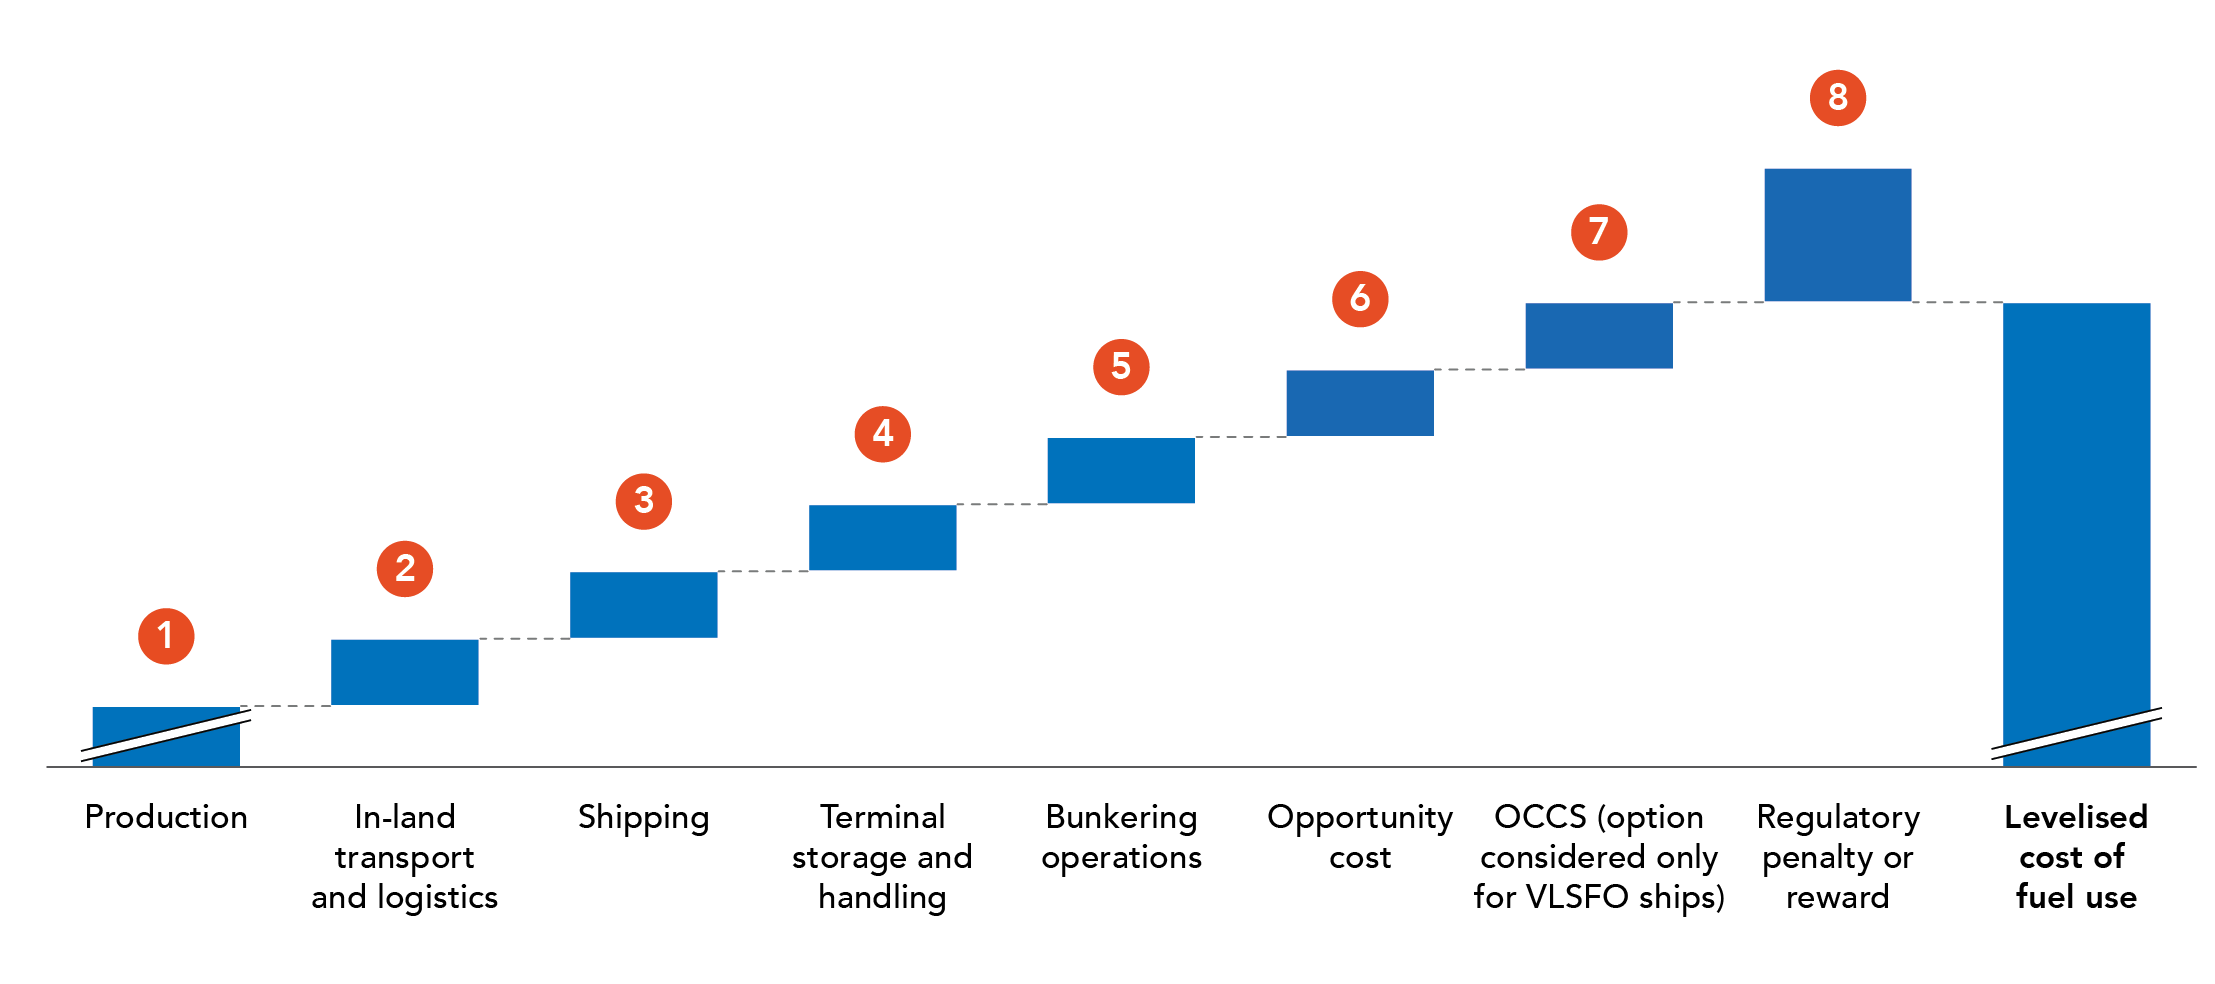
Fig 2 Constituents of levelised cost of fuel use

Professor Lynn Loo, CEO of GCMD, said: “Many vessels ordered over the coming decade will still be operating in 2050. Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear. 

“Our modelling puts into perspective just how difficult closing the cost gap between new and conventional fuels will be. The carbon price required to close this gap is substantial. And achieving it will be particularly challenging in today’s geopolitical environment. Understanding the signposts that could change these economics will be critical to the decisions the industry makes today.”

Anand Veeraraghavan, Managing Director & Senior Partner at BCG, said: “The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness. 

“Rather than offer a single prediction, our approach with GCMD maps how sensitive each fuel pathway’s competitive position is to a handful of critical variables — policy scenarios, key cost drivers, and potential restrictions. Our hope is that this gives shipowners, fuel suppliers, port operators, and infrastructure investors a practical tool to stress-test their own fuel strategies as conditions change.”


Photo credit: Global Centre for Maritime Decarbonisation
Published: 18 September, 2026

Continue Reading

Newbuilding

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

Yang Ming held a naming ceremony at the HD HHI shipyard in Ulsan, South Korea, for “YM Weight”, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI.
Admin

Published

on

By

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

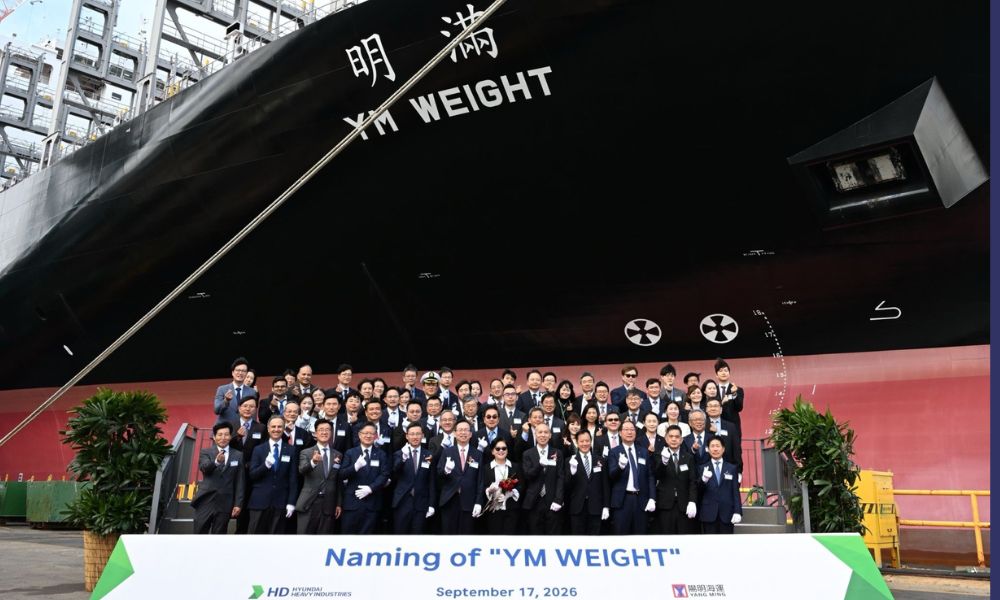
Taiwanese shipping firm Yang Ming Marine Transport Corporation (Yang Ming) on Thursday (17 September) held a naming ceremony at the HD Hyundai Heavy Industries (HD HHI) shipyard in Ulsan, South Korea, for YM Weight, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI. 

Mrs. Chiu-Lien Lin, the spouse of Administrative Deputy Minister of Transportation and Communications Mr. Kuo-Shian Lin, was invited as the Godmother to officially name the vessel and perform the ceremonial cord-cutting, wishing the ship smooth sailing and full loading on all future voyages. 

This series of vessels built by HD HHI has a length overall (LOA) of 364.97 meters, a breadth of 51 meters, and a capacity of approximately 15,600 TEU. 

The vessels are equipped with high-pressure dual-fuel main engines that run on both LNG and low-sulphur fuel oil, along with integrated navigational information, equipment monitoring, broadband maritime satellite systems, and multiple energy-saving systems to enhance operational efficiency and navigational safety. 

YM Weight, the fourth vessel in the series, is jointly classed by CR and the American Bureau of Shipping (ABS), bringing international classification expertise and capabilities to safeguard the safety and technical compliance of next-generation LNG dual-fuel vessels. 

Furthermore, following proactive underwater noise measurements, the vessel has achieved two industry firsts by receiving the Underwater Noise (UWN) notation from ABS and the Underwater Radiated Noise (URN) notation from CR. The dual recognitions underscore Yang Ming’s commitment to mitigate operational impact on marine life and sustainable development. 

In addition to expanding its next-generation fleet and strengthening its core shipping business, Yang Ming has continued to strengthen professional training for seafarers operating alternative-fuel vessels. 

Yang Ming’s senior Captain Ming-Yeong Pan will serve as the delivery captain of ‘YM Weight’. Captain Pan is the first seafarer in Taiwan to receive the Advanced Training Certificate under the International Code of Safety for Ships Using Gases or Other Low-flashpoint Fuels (IGF Code), Certificate No. 0001, issued by the Maritime and Port Bureau, MOTC. 

To date, 148 Yang Ming officers have completed advanced IGF Code training and will progressively undertake onboard training aboard LNG-fueled vessels and practical alternative-fuel bunkering training. 


Photo credit: Yang Ming Marine Transport
Published: 18 September, 2026

Continue Reading

Incident

Peninsula: Missing “Hercules Star” crew member found dead after Dubai incident

Firm confirmed crew member reported missing following last week’s incident involving bunker tanker “Hercules Star” off Dubai has been found dead.
Admin

Published

on

By

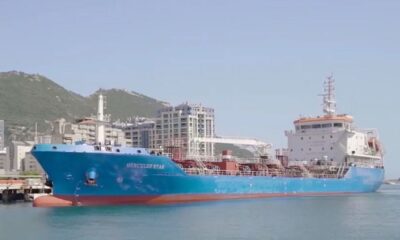
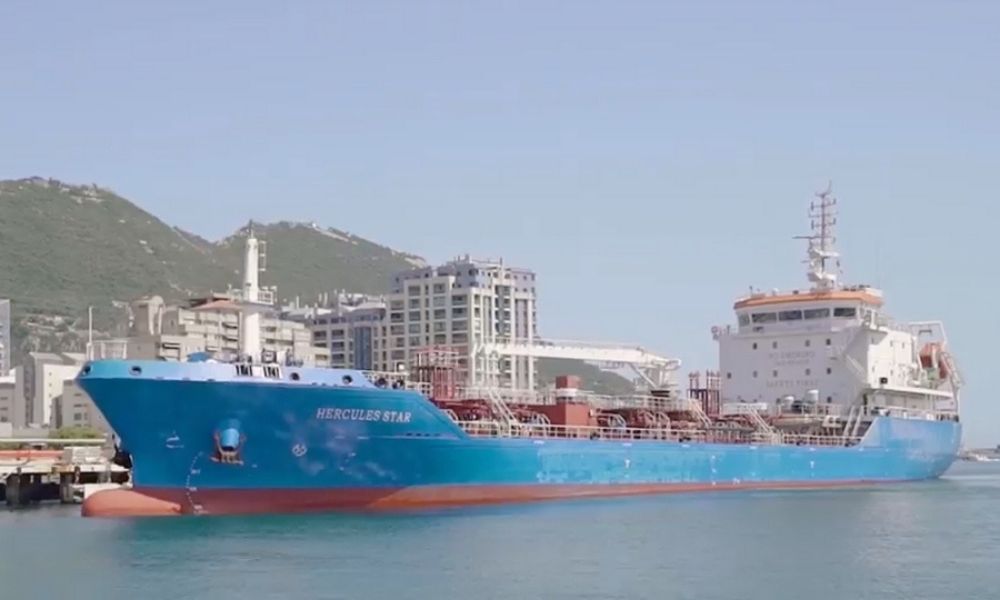
bunker tanker Hercules Star

Marine fuels supplier Peninsula on Thursday (17 September) confirmed that the crew member reported missing following last week’s incident involving bunker tanker Hercules Star off Dubai has been found dead.

The confirmation brings the death toll from the incident to two.

“Following the report of a loss of life during the incident involving the Hercules Star in the early hours of 9th September whilst at anchor off Dubai, we regret to announce that the missing crew member has been found deceased,” company said. 

“Their family have been informed, and we continue to offer our full support and our deepest condolences.”

“All members of the Hercules Star crew have now been repatriated and we continue to support them.”

According to a Reuters report last week, citing preliminary assessments by maritime security sources, the vessel may have been struck by a drone.

The report also said the UK Maritime Trade Operations (UKMTO) received a report of a vessel listing while at anchor about 24 nautical miles off the UAE’s Port Rashid, with the condition “possibly indicating water ingress following an attack from an unknown projectile”.

Related: Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”


Photo credit: Peninsula
Published: 18 September, 2026

Continue Reading

Trending