Biofuel
Brazil launches public consultation on biofuel bunkering rules overhaul
Law firm Mayer Brown says Brazil’s ANP has launched a 45-day public consultation on proposed revisions to the country’s marine fuel specifications, paving the way for routine use of up to 100% biofuel.

Alternative Fuels
Singapore: Bunker fuel sales down by 4% on year in August 2026
4.77 million metric tonnes of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt recorded during the similar month in 2025, according to MPA.
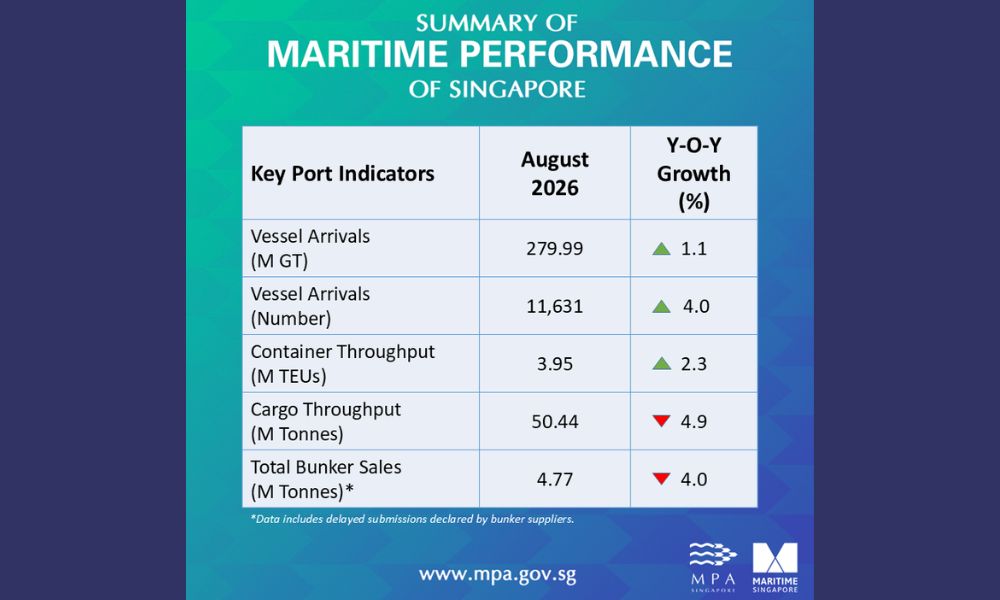
Sales of marine fuel at Singapore port fell by 4% on year in August 2026, according to data from the Maritime and Port Authority of Singapore (MPA).
In total, 4.77 million metric tonnes (mt) (exact 4,772,700 mt) of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt (4,965,300 mt) recorded during the similar month in 2025.
Deliveries of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August (against on year) recorded respectively 2.1 million mt (11.1% from 1.89 million mt), 2.19 million mt (-12.4% from 2.50 million mt), zero (from zero), zero (-100% from 1,800 mt) and zero (from zero).
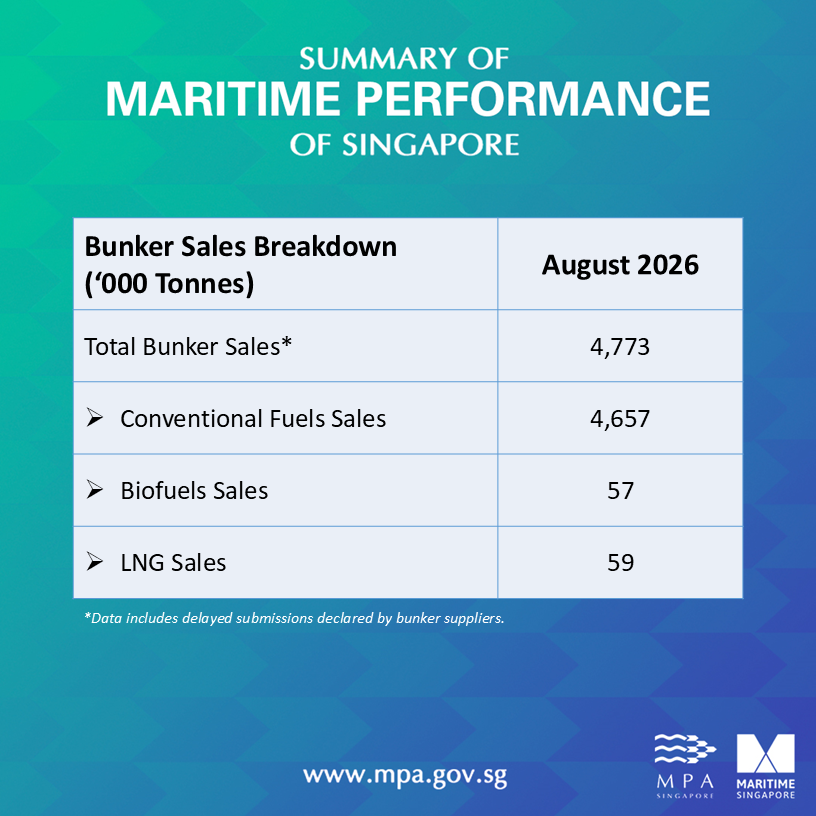
Bio-blended variants of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August, (against on year) recorded respectively 8,700 mt (-74.9% from 34,700 mt), 47,900 mt (-48.9% from 93,800 mt), zero (from zero), zero (from zero) and zero (from zero). B100 biofuel bunkers, introduced in February last year, recorded 800 mt (-83.3% from 4,800 mt).
LNG and methanol sales were 58,600 mt (-12.5% from 67,000 mt) and zero (from zero) respectively. There were no recorded sales of ammonia for the month and so far since 2025.
Photo credit: Maritime and Port Authority of Singapore
Published: 15 September, 2026
Alternative Fuels
ENGINE on Fuel Switch Snapshot: Gas supply risks lift Rotterdam’s LNG and LBM
B30-LSMGO swings to $37/mt discount to LNG (Otto MS); Singapore LNG (diesel SS) discount to LSMGO widens; ZRE A tickets surge on aggressive compliance buying.
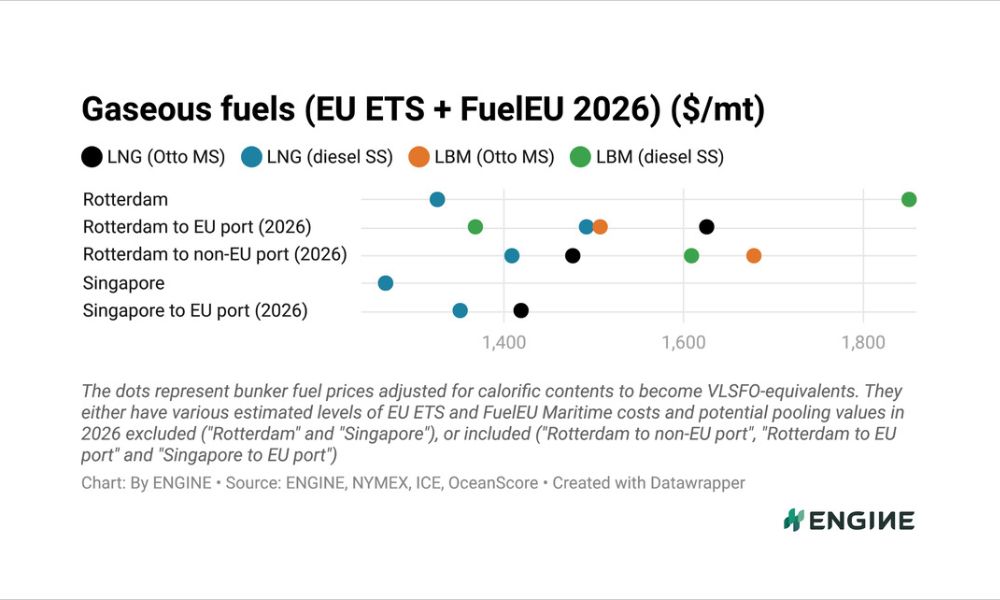
Once a week, bunker intelligence platform ENGINE will publish a snapshot of alternative and conventional bunker fuel prices in the world’s two biggest bunkering hubs. The following is the latest snapshot:
14 September 2026
- B30-LSMGO swings to $37/mt discount to LNG (Otto MS)
- Singapore LNG (diesel SS) discount to LSMGO widens
- ZRE A tickets surge on aggressive compliance buying
Rotterdam’s B30-LSMGO has swung from a $90/mt premium over LNG burnt in Otto medium speed (Otto MS) engines to a $37/mt discount, as LNG has gained $150/mt over the past week against the blend’s $24/mt.
Liquefied biomethane’s (LBM) premiums over HSFO in Rotterdam have widened by $105-107/mt to $348-487/mt depending on engine type, and over VLSFO by $90-92/mt to $233-372/mt.
LBM’s discounts to LSMGO have narrowed by $6-8/mt to $261-400/mt. Its premiums over B100 have widened by $84-86/mt to $271-411/mt.
Rotterdam’s LNG premiums over VLSFO have widened by $95-97/mt to $356-492/mt depending on engine type, and LNG’s discounts to LSMGO have narrowed by $11-13/mt to $141-277/mt.
In Singapore, LNG’s premiums over VLSFO have narrowed by $1-2/mt to $255-323/mt, and its discounts to LSMGO have widened by $85-86/mt to $88-155/mt. The wider discount is for vessels with diesel slow speed (diesel SS) engines.
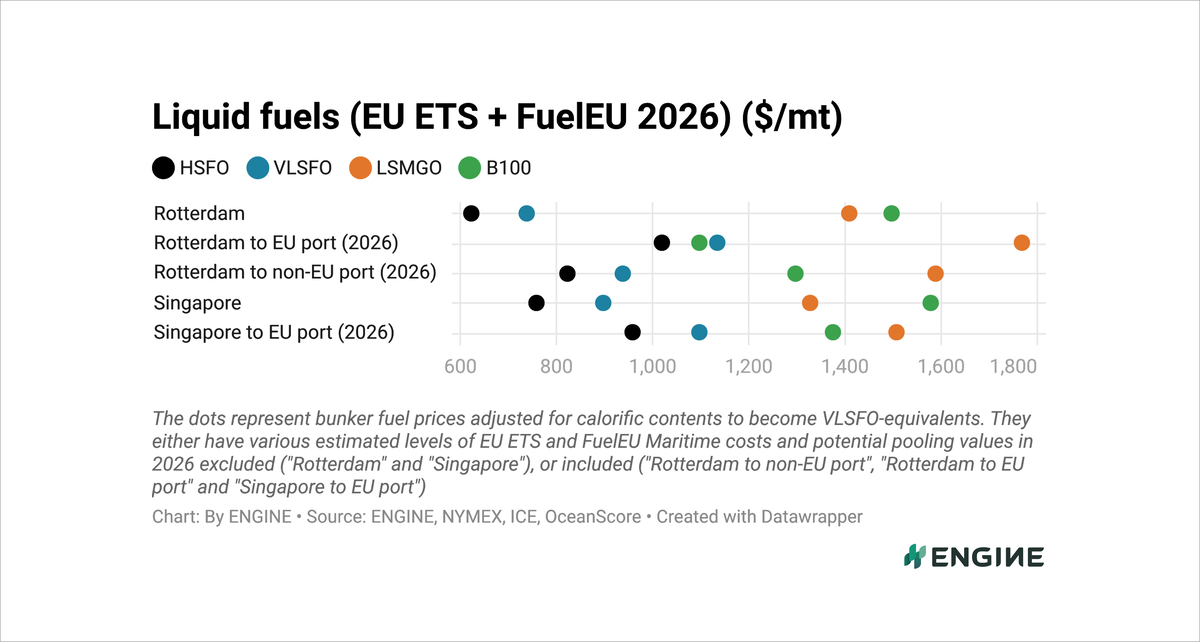
B100’s premium over HSFO in Rotterdam has widened by $21/mt to $76/mt while its discount to VLSFO has narrowed by $6/mt to $39/mt. Its discount to LSMGO has widened by $78/mt to $672/mt.
Singapore’s B100 has widened its premium over VLSFO by $14/mt to $280/mt and its discount to LSMGO by $70/mt to $130/mt.
ENGINE-assessed FuelEU Maritime pooling values have eased by $1/mt for both B100 and LBM, the smaller credits adding to each fuel’s gains, while the OceanScore FuelEU pooling index has held at €118.90/mtCO2e ($138/mtCO2e).
Liquid fuels
Rotterdam’s conventional fuel prices have gained $38-137/mt over the past week, with LSMGO up the most and its benchmark at the highest level in at least four years.
B100 has gained $59/mt and B30-VLSFO $64/mt.
Dutch ZRE A tickets have moved up by €21/mtCO2e ($24/mtCO2e) to €200/mtCO2e ($232/mtCO2e) over the past week. Compliance buyers rather than speculators have driven the increase, Prima Markets analyst Ulrich Arnheiter said.
Conventional bunker fuel availability in the ARA is tight for prompt deliveries, with lead times of 5-7 days advised for most grades, a trader said.
Singapore’s conventional fuel prices have gained $49-133/mt, again with LSMGO up the most, and B100 has gained $63/mt.
Supply in Singapore has remained constrained despite subdued demand, with VLSFO lead times of 12-15 days against 9-16 days a week earlier.
Front-month ICE Brent futures have rallied $10.53/bbl ($77/mt) higher to $108.72/bbl ($797/mt), lifted by vessel attacks near the Strait of Hormuz and Saudi Arabia halting flows through its East-West Pipeline. Dec26 EUA prices have risen by $2.99/mtCO2e to $102.47/mtCO2e.
Liquid gases
Rotterdam’s LNG prices have gained $148-150/mt depending on engine type over the past week, and the port’s LBM prices $143-145/mt, tracking a sharp rise in the front-month Dutch TTF gas contract.
How long the Strait of Hormuz stays closed remains the single most important supply-side uncertainty, IEA gas analyst Greg Molnár said.
Rotterdam’s LBM discounts to LNG have widened by $5/mt to $119-124/mt depending on engine type.
Singapore’s LNG prices have gained $46-47/mt depending on engine type, tracking the front-month NYMEX Japan/Korea Marker.
LNG importers continue to seek cargoes with no resolution of the Middle East conflict in sight, ANZ Bank senior commodity strategist Daniel Hynes said.
By Erik Hoffmann
Photo credit and source: ENGINE
Published: 15 September, 2026
Engine
Polaris Shipping orders WinGD engines capable of running on methanol, ethanol
Ability to operate on either fuel gives Polaris Shipping greater flexibility to respond to changes in fuel availability, pricing and regulatory requirements over the vessels’ operating lives.


OUR INDUSTRY PARTNERS

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Singapore: Bunker fuel sales down by 4% on year in August 2026

ABS joins Korean initiative to develop standards for hydrogen-fuelled ships

World’s first operational ammonia bunker vessel enters service following conversion

IBIA Africa update: Algoa Bay remains a missed bunkering opportunity

ENGINE on Fuel Switch Snapshot: Gas supply risks lift Rotterdam’s LNG and LBM

APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists

Rajah & Tann: Bunker disputes are won in the first 48 hours

Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor

Singapore strengthens LNG bunkering framework with new SS 727 standard

Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean

Auramarine: Marine fuel flexibility will be key to shipping’s energy transition

TFG Marine advances global MFM rollout with two US Gulf bunker barges

Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Bunker Claim2 weeks ago
Rajah & Tann: Bunker disputes are won in the first 48 hours
-
 Vessel Arrest2 weeks ago
Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor
-
 LNG Bunkering2 weeks ago
Singapore strengthens LNG bunkering framework with new SS 727 standard
-
 Alternative Fuels2 weeks ago
Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean
-
 Alternative Fuels1 week ago
Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
-
 Mass Flowmeter2 weeks ago
TFG Marine advances global MFM rollout with two US Gulf bunker barges
-
 Incident5 days ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Winding up1 week ago
Singapore: Liquidators of Nan Ho Maritime, Nan Xin Maritime issue notices of dividend