Connect with us

Biofuel

Petrochina International blends over 30,000 mt of marine biofuel since March

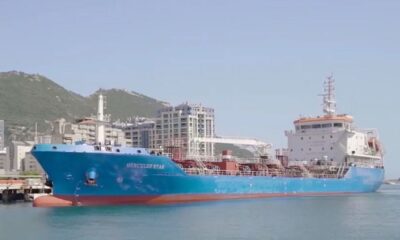
Company has been developing marine biofuel blending operations at China (Zhejiang) Pilot Free Trade Zone, leveraging storage and logistics facilities at its Aoshan base.

Admin

Published

on

Zhoushan completes China’s first batch of marine biofuel blending under pilot programme

Petrochina International Co Ltd recently said it has blended more than 30,000 metric tonnes (mt) mt of biofuel since completing the country’s first biofuel marine fuel blending operation on 13 March.

The company said the milestone demonstrates its ability to conduct continuous and large-scale biofuel marine fuel blending operations.

The company has been developing marine biofuel blending operations at China (Zhejiang) Pilot Free Trade Zone, leveraging storage and logistics facilities at its Aoshan base.

Its latest product, B24 marine fuel containing 24% biofuel component, meets relevant International Maritime Organization (IMO) requirements and marine fuel standards, according to the company. It said the product can be supplied for bunkering vessels operating on international routes.

It has used its global trading network to secure feedstock supplies and support cost control and supply security for the blending operations, it added.

The company said the large-scale blending of its marine biofuel products marks a development in China’s marine biofuel blending market.

It plans to work with upstream and downstream businesses within its group to support the development of Zhoushan Port as a major bonded marine fuel bunkering hub and contribute to its parent group’s transition towards lower-carbon energy.

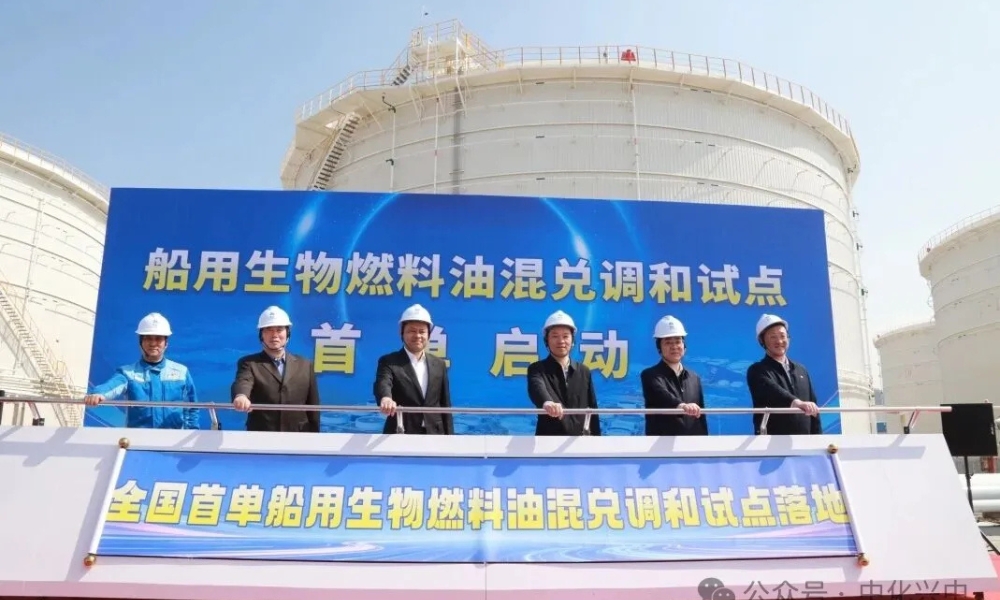
Manifold Times previously reported China (Zhejiang) Pilot Free Trade Zone launching the first pilot programme for marine biofuel blending in China with the completion of the first batch of B24-HSFO. 

The launch was marked with the blending of 2,000 mt of biodiesel and 6,300 mt of high sulphur fuel oil (HSFO) in storage tank F-02 of Sinochem-Xingzhong Oil Staging (Zhoushan), producing 8,300 mt of B24-HSFO. 

Manifold Times also reported the first cross-regional bonded bunkering operation of blended biofuel in East China was successfully completed at the Meishan Port Area of ​​Ningbo-Zhoushan Port. 

The B24-HSFO used in the bunkering operation was supplied by the Aoshan Petroleum Base in Zhoushan from the first pilot programme for marine biofuel blending in China. 

Related: Zhoushan completes China’s first batch of marine biofuel blending under pilot programme
Related: Ningbo wraps up East China’s first cross-regional biofuel blending and bunkering
Related: China debuts first marine biofuel blending pilot programme in Zhoushan
Related: China’s first batch of domestically blended marine biofuel delivered to Qingdao for bunkering


Photo credit: Sinochem-Xingzhong Oil Staging (Zhoushan)
Published: 21 September, 2026

Continue Reading

Alternative Fuels

DNV: How ethanol is expanding shipping’s fuel choices

DNV examines why interest in ethanol is growing, drawing on insights from cargo owners, engine manufacturers, and other industry stakeholders.
Admin

Published

on

By

RESIZED Venti Views on Unsplash

Classification society DNV on Thursday (17 September) published a Maritime Impact article, examining why interest in ethanol is growing, drawing on insights from cargo owners, engine manufacturers, and other industry stakeholders. 

The article explores recent vessel projects, technology developments, and the factors that will influence future uptake, including economics, fuel availability, sustainability, and regulation:

For years, ethanol sat on the periphery of the maritime fuel debate. Whilst the orderbook shows that LNG and, more recently, methanol have seen growing uptake in the global fleet, ethanol has remained largely confined to regional discussions despite being the world’s most widely produced liquid biofuel.

That picture is beginning to change.

Why interest is growing in ethanol as marine fuel

Part of ethanol’s appeal is its maturity outside shipping. Decades of use in road transport have created extensive production capacity, established supply chains, and well-developed fuel logistics. At the same time, increasing focus on lifecycle emissions and regulations such as FuelEU Maritime are directing attention towards fuels capable of delivering meaningful well-to-wake greenhouse gas reductions.

However, production scale and emissions performance alone do not explain the growing interest. Ethanol is entering the maritime conversation at a time when the industry is searching for practical pathways that can support decarbonization without locking companies into a single long-term fuel choice.

Why cargo owners are investing in ethanol-powered ships

Among those exploring ethanol’s potential is VALE, a mining company and cargo owner which sees the fuel as part of its broader decarbonization strategy.

That commitment is already translating into projects. VALE has partnered with Shandong Shipping to build at least two Guaibamax vessels equipped with rotor sails and powered by ethanol, with delivery expected in 2029, and is evaluating the conversion of methanol-fuelled vessels into tri-fuel ships capable of operating on methanol, ethanol, and conventional fuel.

For VALE, a central focus of these projects is how they support the company in maintaining flexibility, thus creating options in an uncertain market. This reflects a broader industry trend towards preserving fuel flexibility whilst continuing to reduce emissions.

“Designing and constructing new ships is the most cost-effective and integrated opportunity to incorporate technological advances in our decarbonization program,” says Rodrigo Bermelho, Shipping Director at VALE. “This approach provides flexibility during regulatory and market uncertainty, enabling VALE to advance decarbonization whilst maintaining different strategic options.”  

Shared technology, greater flexibility: the growing ethanol–methanol opportunity

One of the most interesting aspects of ethanol’s emergence is that it is not developing in isolation.

The fuel enters the maritime conversation at a time when investments in methanol technology are accelerating. The two alcohol fuels share several characteristics, creating opportunities to build on existing engine developments, fuel systems, and operational experience rather than requiring a completely separate technological pathway.

“Ethanol shares some characteristics with methanol and may offer additional flexibility for certain vessel applications over time,” says Mario Barbosa, General Manager Latin America at Wärtsilä.

This connection could prove important as shipowners seek to maintain flexibility in an increasingly uncertain fuel landscape. Rather than committing to a single fuel pathway, they may be able to leverage technologies and vessels capable of accommodating multiple future fuel options.

Ethanol requires own technical assessment

Whilst the similarities between methanol and ethanol create opportunities, industry experts stress that the two fuels should not be treated identically. Safety considerations also remain important. However, ethanol benefits from the fact that alcohol fuels are already covered by established IMO safety frameworks, whilst growing operational experience with methanol is helping the industry better understand the safe handling and use of alcohol-based marine fuels.

“Engine parameters, fuel injection, fuel system specifications, and safety considerations need to be carefully assessed for each vessel and application,” says Barbosa. “Ethanol brings its own characteristics, including differences in energy content, which means optimization is important to support reliable and efficient operation.”

In practice, this means that ethanol benefits from lessons learned through methanol adoption but still requires its own technical assessment. Fuel system design, engine configuration, and operational requirements must all be considered when evaluating ethanol for a specific vessel or trade.

Note: The full article by DNV can be found here


Photo credit: Venti Views on Unsplash
Published: 21 September, 2026

Continue Reading

Biofuel

IMO issues shipboard checklist for FAME-based biofuel blends

Checklist is intended to help vessel operators navigate some of the practical considerations involved when bunkering and consuming biofuel blends, particularly when using them for the first time.
Admin

Published

on

By

RESIZED IMO Building

The International Maritime Organization (IMO) on Wednesday (16 September) said the Shipboard Biofuel Blend Checklist for FAME-based biofuels has now been issued as an annex to document MEPC 85/INF.10.

The checklist was developed by the IBIA Technical Working Group as part of the ongoing update of the IBIA/BIMCO Shipmaster’s Bunkering Manual and is intended to help vessel operators navigate some of the practical considerations involved when bunkering and consuming biofuel blends, particularly when using them for the first time. 

It covers a range of areas, including fuel assessment, compatibility checks, tank preparation, water management, bunkering operations, storage and machinery performance monitoring.

As the use of biofuel blends continues to grow, IMO said having clear and practical guidance for crews and operators is increasingly important. 

The checklist is based on the CIMAC Guideline 04|2024, Marine fuels containing FAME, and is intended as a practical tool to support good fuel management onboard.

“It’s great to see the work now formally included in an IMO document and available to its membership,” IMO said. 

Note: The checklist can be viewed here


Photo credit: International Maritime Organization
Published: 17 September, 2026

Continue Reading

Biofuel

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Marine biofuel growth hindered by economic squeezes and fragmented policies, requiring predictable carbon pricing and demand guarantees to scale.
Admin

Published

on

By

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Bio-bunkers are not capacity constrained; they are economics constrained, and policy asymmetry is dictating where volumes materialise, according to international bunker trading firm Dan-Bunkering.

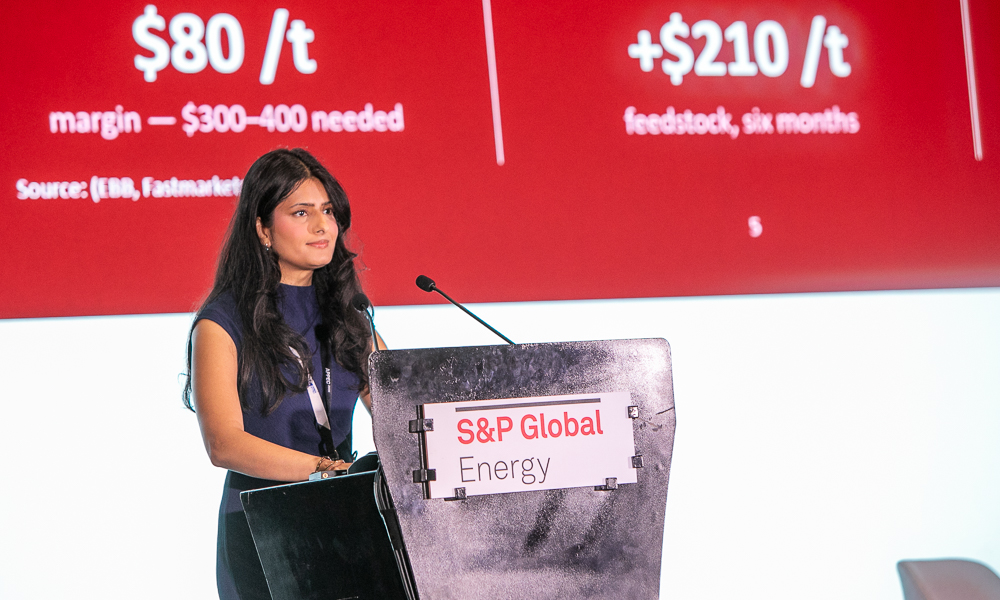
Mahnoor Samee, New Fuels Lead – APAC, Dan-Bunkering, was sharing a presentation Bio-Bunker Dynamics: Where is it Heading? with delegates at APPEC 2026 on Thursday (10 September) when she noted the following:

Disconnect in Production Margins

The primary constraint on marine biofuel, particularly Fatty Acid Methyl Ester (FAME), is not a lack of production capability, but a severe margin squeeze.

European FAME plants are operating at only 52% capacity, yet producers are unable to scale due to unfavourable economics.

Producers face a ‘falling ceiling’ as EU pooling credit prices have dropped by 50% in the past six months, and a ‘rising floor’ as Used Cooking Oil (UCO) feedstock costs have climbed significantly across the same period.

Consequently, the premium between UCO and Used Cooking Oil Methyl Ester (UCOME) has averaged around USD 80 pmt, well below the USD 300-400 pmt industry experts deem necessary for a sustainable business.

Contrasting Regional Demand

Demand for biofuels is meanwhile highly bifurcated and driven primarily by regional policy rather than global market trends.

In Singapore, bio-bunker sales have fallen by 45-60% year-over-year; as conventional fuel prices spiked, shipowners shifted to cheaper compliance alternatives such as pooling.

In contrast, Rotterdam has reached two-year highs in biofuel sales, supported by the Dutch ticket incentive system, which stabilises end-user pricing.

China has also seen a fourfold increase in demand over the past two years, driven by high EU exposure and voluntary emission goals, aided by lower logistics costs and strong trade routes to Europe.

Regulatory Fragmentation

Regulatory uncertainty remains a significant barrier to investment. The International Maritime Organization (IMO) is currently debating four conflicting proposals – ranging from delayed targets to tripled penalties – which has stalled projects and left the industry without a clear framework to engage.

In addition, the emergence of approximately 40 different carbon schemes globally, including the potential expansion of the UK Emissions Trading System (ETS) to include international voyages has created significant planning risks for shipowners.

The implementation of Renewable Energy Directive (RED) III in Europe has further complicated the landscape, creating a “RED III premium” that has caused some volume to shift to nearby ports like Antwerp to avoid higher costs, though Rotterdam remains resilient due to its national incentive schemes.

A critical challenge for the industry is how bunker buyers value biofuels. Many stakeholders compare the listed price of biofuel directly against conventional fuel or pooling, failing to account for “stacked benefits.”

When factoring in FuelEU compliance, reduced EU ETS carbon bills, and improved Carbon Intensity Indicator (CII) ratings, the “true premium” is significantly lower – estimated at USD 5-90 pmt rather than the sticker price of USD 300-400.

Policy Continues to Drive Demand

Looking toward 2030, the market faces a clear reality: 95% of the global fleet will still rely on conventional engines, making drop-in biofuels the only scalable emissions lever.

To unlock this potential, the industry requires a predictable carbon price and a mechanism to guarantee demand, similar to the Sustainable Aviation Fuel (SAF) levy model recently adopted in Singapore.

Without these structural changes, Asia’s technical capacity may remain underutilised, and the market will continue to consolidate in policy-advantaged hubs.


Photo credit: Manifold Times
Published: 17 September 2026

Continue Reading

Trending