Connect with us

Bunker Fuel Availability

ENGINE: East of Suez Bunker Fuel Availability Outlook (21 April 2026)

Bunker availability good in Zhoushan; VLSFO and LSMGO availability good across several Taiwanese ports; bunker demand picking up across South Korean ports.

Admin

Published

on

RESIZED ENGINE East of Suez

The following article regarding regional bunker fuel availability outlook for the East of Suez region has been provided by online marine fuels procurement platform ENGINE for publication on Singapore bunkering publication Manifold Times:

  • Bunker availability good in Zhoushan
  • VLSFO and LSMGO availability good across several Taiwanese ports
  • Bunker demand picking up across South Korean ports

Singapore and Malaysia

Prices in Singapore have edged lower, supported by expectations that upcoming US-Iran peace talks could ease regional tensions and potentially increase supply from the Middle East, a source said.

Soft demand is adding to the pressure. “Demand for VLSFO is slow,” a Singapore-based trader said, contributing further to the decline in the benchmark.

In terms of availability, VLSFO lead times in Singapore remain broadly stable at 5-12 days. HSFO lead times are now assessed at 5-10 days, compared with a wider 3-12-day range last week.

LSMGO lead times continue to hold steady at 2-7 days, largely unchanged week on week.

On the supply side, Singapore’s residual fuel oil inventories have averaged 5% lower so far in April compared to March, according to Enterprise Singapore. Total fuel oil stocks have dropped below 23 million bbls, driven by a sharp 54% decline in net imports this month. Imports have fallen by 2.39 million bbls, while exports have risen slightly by 151,000 bbls.

In contrast, middle distillate inventories have increased, averaging 15% so far this month and reaching their highest levels since September.

At Malaysia’s Port Klang, VLSFO availability remains relatively steady, particularly for smaller prompt stems. However, tighter LSMGO supply and continued constraints in HSFO availability are making both grades harder to secure.

East Asia

Availability in Zhoushan remains strong across all grades, with recommended lead times steady at 3-7 days, largely unchanged from last week. However, adverse weather later this week could disrupt bunkering operations, a source noted.

Across northern China, supply conditions are uneven. Dalian and Qingdao have sufficient VLSFO and LSMGO stocks, although HSFO remains limited in Qingdao. Tianjin is facing tight availability across all grades, while Shanghai is seeing constrained VLSFO and HSFO supply, with LSMGO relatively stable.

Further south, supply remains tighter. Fuzhou is experiencing limited availability of both VLSFO and LSMGO. Xiamen has adequate VLSFO supply but restricted LSMGO volumes. In Yangpu and Guangzhou, both grades continue to face supply pressure.

In Hong Kong, bunker availability is largely stable, with lead times for all grades holding at around seven days in recent weeks.

Meanwhile, CPC Corporation has lifted restrictions on bunker delivery order extensions and cancellation charges at Taiwanese ports with immediate effect.

“There is no such problem [shortage of cargo] happening till now, therefore CPC thinks it is unnecessary to keep this rule in place,” a trader said.

The company added that it will resume accepting requests to extend delivery order validity, and that cancellation charges introduced on 10 March will no longer apply.

In Taiwan, supply conditions remain stable, according to a local trader. Lead times are around two days for both VLSFO and LSMGO across Keelung, Taichung, Kaohsiung and Hualien.

In South Korea’s southern ports – including Busan, Ulsan, Masan, Onsan, Yeosu and Kwangyang – recommended lead times for all fuel grades remain steady at around 2-3 days, broadly unchanged from approximately three days last week.

At western ports such as Incheon, Daesan, Dangjin, Pyeongtaek and Taean, lead times are also at 2-3 days, easing from a wider 4-6-day range in the previous week.

Bunker demand in the country has shown some improvement, supported by a decline in Brent futures amid expectations of easing tensions in the Middle East, a South Korea-based trader said.

Weather disruptions persist, with potential delays expected in Busan and Ulsan between 23-24 April, in Yeosu on 23 April, and in Daesan between 26-27 April.

In Japan, a 7.5-magnitude earthquake struck off the Sanriku coast in Iwate Prefecture on Monday, prompting the Japan Meteorological Agency to issue tsunami warnings for Iwate and parts of Hokkaido and Aomori. Waves of up to 3 metres were anticipated, though the warnings—and subsequent advisories covering parts of Hokkaido, Aomori, Iwate, Miyagi and Fukushima—were later lifted.

Port operations were unaffected, with a source confirming there was “no impact.” However, the Japan Meteorological Agency has since warned of a potential mega quake, advising residents across seven prefectures to remain alert and follow updates.

Bunker supply in Japan remains tight overall, driven by crude procurement constraints and ongoing Middle East tensions. Osaka is described as severely tight, while Tokyo Bay (Chiba, Kawasaki and Yokohama) offers limited, selectively available supply depending on demand. Suppliers are prioritising discreet, case-by-case negotiations, avoiding open market inquiries, the source added.

As a result, availability across all fuel grades in major Japanese ports – including Tokyo, Chiba, Yokohama, Kawasaki, Nagoya, Yokkaichi, Mizushima, Kashima, Tokuyama and Oita – is now assessed individually rather than through standard market availability.

Oceania

Availability across Australian ports has improved, although prices remain elevated and smaller operators continue to face volume constraints, an Australia-based trader said.

Last week, a fire broke out at the Viva Energy Refinery Geelong. Emergency services responded and brought the situation under control. Geelong Port has since confirmed that the refinery pier has resumed normal operations, with all berths now operational, according to Inchcape Shipping. The trader added that the incident had “no impact” on LSMGO and VLSFO supply.

In Western Australia, VLSFO supply at Kwinana and Fremantle typically requires about one week’s notice, with deliveries carried out by barge through a single supplier.

In New South Wales, VLSFO deliveries at Port Kembla can be arranged via truck or pipeline. Suppliers in Sydney maintain ample VLSFO and LSMGO stocks, while HSFO remains tight, with lead times of around seven days.

In Queensland, ports including Brisbane and Gladstone are offering VLSFO and LSMGO with lead times of roughly seven days. HSFO in Brisbane is available on request. Deliveries of VLSFO and LSMGO are handled by two barges operated by separate suppliers, while HSFO availability depends on enquiry.

In Victoria, VLSFO inventories remain strong in both Melbourne and Geelong, although HSFO availability is limited for prompt supply. Bunkering operations in these ports rely on a single barge, with recommended lead times close to seven days.

Australia’s cyclone season, which typically runs from November to April, is also coming to an end, the source said.

In New Zealand, bunker supply conditions remain stable. VLSFO is readily available in Tauranga and Auckland, with some Tauranga berths connected by pipeline. At Marsden Point, both VLSFO and LSMGO can be supplied via pipeline to vessels.

South Asia

In India, VLSFO availability remains good in Cochin, while lead times of around 3-4 days are reported in Kandla, a source said.

Adverse weather is expected to affect operations at several Indian ports, including Kandla between 22-24 April, Sikka on 23 April, Visakhapatnam between 22-25 April, and Mumbai on 25 April, which could disrupt bunkering activities.

Middle East

“The bunkering situation in the Middle East is more stable now, but still not fully consistent,” a regional source said.

At Fujairah, bunkering continues without disruption, with terminals and anchorages operating normally. “Avails [are] ok as of now, all offers are subject to firm inquiry,” another trader said.

While operations are ongoing, some suppliers are loading barges based on actual demand rather than at full capacity, reflecting subdued demand in the port.

Elsewhere in the UAE, operations at Jebel Ali, Hamriyah and Sharjah are running as usual. Petroleum terminals in Abu Dhabi, including Ruwais, are also functioning normally. Ship-to-ship (STS) operations at Dubai anchorage have resumed with tug support, with each case evaluated individually, according to Inchcape Shipping.

“Prices have improved slightly, but they can still change quickly. Vessel operations are better than before, with smoother port entry and departure, though some delays can still happen. It is still recommended to book in advance to avoid any issues,” a trader noted.

Ports in Ras Al Khaimah remain fully operational. However, RAK Ports introduced a marine risk surcharge in March for vessels calling at its ports, harbours and anchorages.

In Kuwait, Shuaiba and Shuwaikh are operating normally. Saudi Arabia has not issued formal alerts, although bunker availability in Jeddah remains tight, particularly for VLSFO and LSMGO.

In Qatar, port activity remains steady at Hamad, Doha and Al Ruwais, with operations also ongoing at Mesaieed and Ras Laffan. However, VLSFO and LSMGO supply is tight in Ras Laffan, while in Al Ruwais availability is limited to smaller vessels such as dhows and barges.

In Oman, all ports are fully operational, with good LSMGO availability and prompt lead times in Muscat, Duqm and Sohar, the source said.

In Bahrain, vessel movements are gradually resuming, though operations remain limited. Egyptian ports are functioning normally, but VLSFO is nearly depleted at Port Suez, while LSMGO supply remains sufficient.

Both VLSFO and LSMGO availability are tight at Djibouti’s port of Djibouti.

Port conditions remain stable in Jordan, while ports in Iraq, Cyprus, Pakistan and Lebanon continue normal operations.

Israeli ports—including Eilat, Ashkelon, Ashdod, Hadera and Haifa—are operating at full capacity, according to Inchcape Shipping.

By Tuhin Roy


Photo credit and source: ENGINE
Published: 22 April, 2026
Continue Reading

Bunker Fuel

ENGINE: Europe & Africa Bunker Fuel Availability Outlook (23 Sep 2026)

Prompt availability tight in ARA ports; busy summer cruise season increases lead times in Piraeus; increase in demand tightens availability in South African ports.

Admin

Published

on

By

RESIZED ENGINE Europe and Africa

The following article regarding Europe and Africa bunker fuel availability has been provided by online marine fuel procurement platform ENGINE for post on Singapore bunkering publication Manifold Times:

  • Prompt availability tight in ARA ports
  • Busy summer cruise season increases lead times in Piraeus
  • Increase in demand tightens availability in South African ports

Northwest Europe

Fuel availability in the ARA is tight for prompt delivery dates, and buyers are recommended lead times of 5-7 days to secure supplies at competitive prices, a trader told ENGINE.

The ARA’s independently held fuel oil stocks have averaged 17% higher in September so far compared with August’s monthly average, according to Insights Global data.

The ARA hub has imported around 297,000 b/d of fuel oil in September so far, down from around 342,000 b/d in August, according to Vortexa cargo flows data.

Most shipments have arrived from Mexico (24%), Benin (19%) and France (15%).

The region’s independent gasoil inventories – which include diesel and heating oil – have risen by 2% in September so far, compared to August, according to the Insights Global data.

The region has imported around 141,000 b/d of gasoil in September so far, down from an average of around 155,000 b/d imported in August, according to Vortexa data. A majority of shipments have arrived from the US (28%), Germany (13%) and the UK (11%).

Fuel availability in Hamburg is steady, with five days’ notice recommended to secure any grade in the German port, a trader told ENGINE.

Bunker availability remains tight off Skaw and in Gothenburg, and buyers are asked to give around 10-14 days for delivery of any grade in the Scandinavian hubs, a trader said.

Mediterranean

Prompt fuel availability at ports in the Gibraltar Strait is tight, with lead times of 10-12 days recommended for reliable coverage, a trader told ENGINE.

Gibraltar is seeing slight congestion, with around eight vessels currently awaiting bunkers, port agent MH Bland said. Bunkering delays of around 4-8 hours can be expected in the port. Some suppliers in Algeciras can be delayed by around 18-24 hours, the port agent added.

In the Spanish port of Ceuta, barge and ex-pipe deliveries are running on schedule now, after slight delays seen last week, the port agent said.

Fuel availability is tight in Las Palmas, and buyers are recommended lead times of around 10-12 days to secure deliveries, a trader noted.

LSMGO is seeing high demand off Malta. Fuel availability is comparatively stable compared to last week, and lead times have reduced to 3-4 days for LSMGO, VLSFO and ULSFO, compared to 5-7 days last week, a trader said.

Fuel availability in Greece’s Piraeus is tight for HSFO, VLSFO and ULSFO, and buyers are recommended lead times of around 5-7 days for those grades, a trader said. LSMGO deliveries are more prompt, with a notice of three days sufficient, according to the trader.

The port is seeing a busy summer cruise season, and barge availability is an issue in Piraeus, especially for HSFO, the trader added.

Istanbul fuel availability is stable, with every grade obtainable on 1-4 days of notice, a trader said.

Africa

In Senegal’s Dakar, fuel availability is stable and stems can be delivered promptly by at least one supplier.

In the Togolese port of Lome, prompt VLSFO and LSMGO supply is a bit tight due to high demand, and buyers are recommended to book with lead times of at least a week, a trader told ENGINE.

In Nigeria’s Lagos anchorage, VLSFO fuel supplies are tight with buyers recommended at least nine days’ notice for deliveries, a local supplier told ENGINE.

Off Namibia’s Walvis Bay, prompt fuel availability is tight, and buyers have been advised to book with lead times between 5-7 days for VLSFO and LSMGO deliveries, a trader told ENGINE.

Increasing demand has tightened fuel availability in South African hubs like Durban, Algoa Bay, Richards Bay and Cape Town, a trader said. Some suppliers in these ports need at least 10-15 days of lead time to arrange deliveries of HSFO, VLSFO and LSMGO, the trader added.

Fuel availability remains very tight in Port Louis, with buyers recommended to book around 10-14 days ahead to get deliveries of VLSFO and LSMGO, a trader said. HSFO availability is very limited in the port.

VLSFO availability remains tight for prompt supplies at the Mozambican ports of Nacala and Maputo, where notice of seven days is recommended, a trader told ENGINE.

By Nachiket Tekawade


Photo credit and source: ENGINE
Published: 24 September, 2026

Continue Reading

Bunker Fuel

ENGINE: East of Suez Fuel Availability Outlook (22 Sep 2026)

VLSFO availability tight in Singapore; VLSFO and LSMGO availability good across several Taiwanese ports; availability tight across all grades in Fujairah.

Admin

Published

on

By

RESIZED ENGINE East of Suez

The following article regarding regional bunker fuel availability outlook for the East of Suez region has been provided by online marine fuels procurement platform ENGINE for publication on Singapore bunkering publication Manifold Times:

  • VLSFO availability tight in Singapore
  • VLSFO and LSMGO availability good across several Taiwanese ports
  • Availability tight across all grades in Fujairah

Singapore and Malaysia

Singapore’s bunker market remains tight, with recommended lead times for VLSFO at 13-17 days, almost unchanged from 13-16 days a week earlier. Most suppliers are holding low stock levels, while delays in cargo arrivals linked to the conflict in the Middle East have added further pressure to availability, according to a Singapore-based source.

HSFO availability has improved slightly, with advised lead times easing to 9-12 days from 10-19 days last week. LSMGO supply has also strengthened, with lead times narrowing to 5-7 days from 6-8 days previously.

Singapore’s residual fuel oil stocks have averaged 7% higher so far this month compared with August, according to the latest Enterprise Singapore data. Stocks have climbed above 20 million bbls, supported by an 18% increase in net fuel oil imports so far in September. Both imports and exports have declined during the period, with imports falling by 167,000 bbls and exports decreasing more sharply by 643,000 bbls.

Middle distillate inventories have also risen by 3% this month to 8.46 million bbls.

At Malaysia’s Port Klang, bunker supply remains constrained. Prompt VLSFO availability is particularly tight, while LSMGO supply remains limited and HSFO availability continues to face pressure.

East Asia

In Zhoushan, VLSFO lead times remain at around 10 days, unchanged from last week, as several suppliers are running low on stocks and delays in replenishment cargoes are limiting availability, according to a source. LSMGO and HSFO supply has improved, with lead times falling to around seven days from 10 days previously.

Supply conditions remain mixed across other Chinese ports. Dalian and Qingdao have adequate VLSFO and LSMGO stocks, although HSFO remains tight in Qingdao. Tianjin is facing shortages across all three major grades, while Shanghai has limited availability of VLSFO and HSFO but relatively stable LSMGO supply.

Pressure is also evident in southern China. Suppliers in Fuzhou and Xiamen are short of VLSFO and LSMGO, while supplies of both grades remain constrained in Yangpu and Guangzhou.

Bunkering activity is expected to remain muted at several Chinese ports during the Mid-Autumn Festival from 25-27 September. Deliveries against existing orders will continue as usual during the holiday period, while 22 September is the final day for placing stem orders at most ports for delivery during the holidays, according to a China-based source.

In Hong Kong, the bunker market is broadly unchanged, with suppliers maintaining lead times of around seven days for the major grades.

In Taiwan, VLSFO and LSMGO lead times remain at around two days at Keelung, Taichung, Hualien and Kaohsiung, showing little change from last week.

In South Korea, lead times for all major grades at southern ports, including Busan, Ulsan, Masan, Onsan, Yeosu and Kwangyang, have settled at around nine days, compared with 6-10 days a week earlier. Western ports, including Incheon, Daesan, Dangjin, Pyeongtaek and Taean, are seeing a similar trend, with VLSFO, LSMGO and HSFO lead times also at around nine days, versus 6-10 days previously.

Meanwhile, weather-related disruptions are possible in the coming days. Bunkering operations at Busan, Ulsan and Yeosu could remain affected until 23 September due to bad weather, while Daesan may face disruptions from 25-26 September.

In Japan, recent operational issues have been resolved, but the September loading schedule remains fully committed, leaving prompt supply virtually exhausted. Some October availability is beginning to emerge, although suppliers are accepting inquiries strictly on a firm-inquiry basis, subject to confirmation. Early inquiries are therefore advised to secure prompt allocations.

“September prompt spot remains extremely tight with minimal fresh offers. October inquiries are being reviewed on a case-by-case basis as supply schedules normalise,” a Japan-based trader said.

The trader also recommended arranging bunker requirements well in advance, citing the Silver Week holiday from 19-23 September and exceptionally tight market conditions.

Availability of VLSFO, LSMGO and HSFO has tightened across several Japanese ports, including Tokyo, Chiba, Kawasaki, Nagoya, Yokkaichi, Osaka, Kobe, Mizushima, Tokuyama and Oita. Supplies of all three grades are virtually unavailable this month, while October and later stems remain subject to inquiry. Kashima continues to face tight availability of VLSFO and HSFO.

By contrast, Indonesia continues to have healthy bunker fuel availability. Suppliers at Jakarta, Surabaya, Balikpapan and Cigading are generally recommending VLSFO lead times of just 2-3 days.

Oceania

Bunker fuel supply in Western Australia remains stable, with VLSFO readily available at Kwinana and Fremantle. Suppliers at both ports are quoting lead times of around seven days. Each port is served by a single supplier, with all deliveries carried out by barge.

Supply conditions are more mixed along Australia’s east coast. At Port Kembla, VLSFO supply is normal and can be delivered by truck or pipeline, while VLSFO and LSMGO availability in Sydney is adequate. HSFO supply is comparatively tighter in Sydney, with suppliers generally requiring around seven days’ notice.

Further north, Brisbane and Gladstone have ample VLSFO and LSMGO availability, with delivery lead times of roughly one week. Suppliers in Melbourne and Geelong also have comfortable VLSFO stocks, although both ports rely on a single bunker barge, keeping lead times at around seven days. HSFO availability has tightened further in both Melbourne and Brisbane.

Separately, one supplier is offering VLSFO, LSMGO and HSFO at Brisbane, Sydney and Melbourne with shorter lead times of approximately five days.

In Western Australia, pipeline bunkering at Dampier Cargo Wharf (DCW) is expected to remain suspended until around the end of September as repair work continues. Limited truck deliveries are available, depending on vessel size. During the disruption, the supplier has designated the Toll Supply Base (TSB) in Dampier as the preferred bunkering point, according to a source.

Across the Tasman, New Zealand’s bunker market remains broadly stable. VLSFO is readily available at Tauranga and Auckland, with suppliers quoting lead times of around four days. At Marsden Point, vessels can receive both VLSFO and LSMGO directly via pipeline.

Weather remains the main operational risk in New Zealand, with Wellington and ports across the South Island particularly susceptible to bunker delivery delays when adverse conditions disrupt marine operations.

South Asia

Bunker lead times of around 3–4 days are recommended for VLSFO, HSFO and LSMGO at several major Indian ports, including Mumbai, Cochin, Paradip, Visakhapatnam, Kakinada, Haldia, Chennai, Tuticorin and New Mangalore. This is broadly unchanged from the previous week, an India-based source said.

Weather conditions could, however, put some pressure on bunker deliveries in the coming days. Rough weather is expected to disrupt operations at Sikka on 25–26 September and Kandla on 24–26 September, while rough waves are forecast off Visakhapatnam from 22–26 September.

In Sri Lanka, adverse weather is also expected at Colombo and Trincomalee from 22–26 September, potentially causing delays to bunker deliveries.

Middle East

Bunker fuel availability in Fujairah remains severely constrained as ongoing US-Iran tensions continue to disrupt shipping through the Strait of Hormuz. Supply of all major fuel grades is described as “super tight”, while fuel oil imports have fallen sharply amid heightened regional uncertainty.

Similar supply pressure is being reported at nearby Khor Fakkan, where availability of all grades remains limited, according to a Middle East-based source.

In Saudi Arabia, VLSFO and LSMGO availability at Jeddah remains steady. However, adverse weather could intermittently disrupt bunkering operations at Jeddah on 25–26 September and Yanbu on 24–26 September.

At Qatar’s Ras Laffan, supplies of both VLSFO and LSMGO remain restricted.

In Oman, “the conflict is still ongoing, and prices have increased significantly. However, from the operations side, supply is continuing as normal with no major challenges so far,” an Oman-based trader said.

LSMGO supply remains stable at key Omani ports, including Salalah, Muscat, Duqm and Sohar, with suppliers recommending lead times of around one day.

In Egypt, bunker inventories at Port Suez have dropped to critically low levels across all three conventional fuel grades. Further south, Djibouti is also experiencing limited availability across major fuel grades.

By Tuhin Roy


Photo credit and source: ENGINE
Published: 23 September, 2026

Continue Reading

Biofuel

ENGINE on Biofuel Bunker Snapshot: B30-VLSFO prices drop across global hubs

B100 price surges in Rotterdam this week; Gibraltar’s B30-VLSFO price drops sharply; Singapore’s bio-blended bunker volumes rose sharply.

Admin

Published

on

By

ENGINE on Biofuel Bunker Snapshot: B30-VLSFO prices drop across global hubs

Once a week, bunker intelligence platform ENGINE will publish a snapshot of biofuel bunker prices in Europe, Fujairah and Singapore. The following is the latest snapshot:

  • B100 price surges in Rotterdam this week
  • Gibraltar’s B30-VLSFO price drops sharply
  • Singapore’s bio-blended bunker volumes rose sharply

Europe

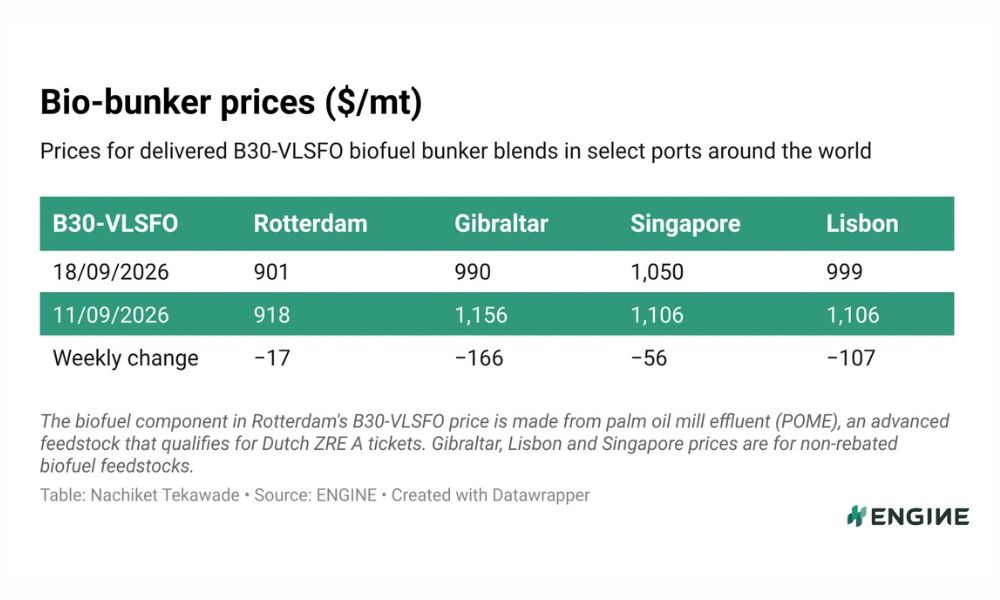
Rotterdam’s B30-VLSFO (POMEME) price has dropped $17/mt in the past week, most probably pressured by a $24/mt drop in the Dutch port’s conventional VLSFO price during the same period.

Rotterdam’s B30-LSMGO (POMEME) price has gained by $17/mt to $1,476/mt, which has been similar to a $19/mt gain in the port’s conventional LSMGO price.

B100 has been priced at $1,418/mt in Rotterdam today, a sharp $209/mt increase compared to last week.

Prima Markets’ POMEME barge price, which is an indicator of feedstock sourcing costs, has gone up by $35/mt to $2,059/mt.

Dutch suppliers can generate ZRE A tickets for selling low carbon fuels, which can be traded with other suppliers. The price of these tickets has dropped from €200/mtCO2e ($230/mtCO2e) last Friday to €190/mtCO2e ($218/mtCO2e) on Thursday this week.

Gibraltar’s B30-VLSFO (UCOME) price has slumped $166/mt lower in the past week. The port’s conventional VLSFO price has remained largely unchanged during this period.

This has cut the port’s B30-VLSFO price premium over conventional VLSFO by $172/mt in a single week to $250/mt.

Lisbon’s B30-VLSFO price has dropped $107/mt during the week. It has flipped to a modest $9/mt premium over Gibraltar’s B30-VLSFO price, coming from a $50/mt discount last Friday.

Lisbon’s B30-LSMGO price has slumped $115/mt to $1,600/mt, while the B100 price in the Portuguese port has plunged $215/mt lower to $1,665/mt.

Asia

Singapore’s B30-VLSFO (UCOME) price has dropped $56/mt since last Friday, while the port’s conventional VLSFO price has gained only $5/mt over the same period.

This has narrowed the port’s B30-VLSFO price premium by $61/mt in a single week.

Data this week showed Singapore’s bio-blended bunker sales rose by 48% in August to 57,000 mt, which was the highest monthly volume since April.

B30-VLSFO is priced at $1,015/mt in Hong Kong, which is a $35/mt price discount to Singapore.

Hong Kong’s B30-VLSFO price is at a $109/mt premium over its conventional VLSFO price.

By Nachiket Tekawade


Photo credit and source: ENGINE
Published: 22 September, 2026

Continue Reading
Advertisement

OUR INDUSTRY PARTNERS


Trending