Connect with us

FuelEU

CTI-Maritec: FuelEU Maritime regulation effective 1 January 2025

FuelEU Maritime Regulation will be enforced by the EU for all ships trading within the EU or European Economic Area (EEA).

Admin

Published

on

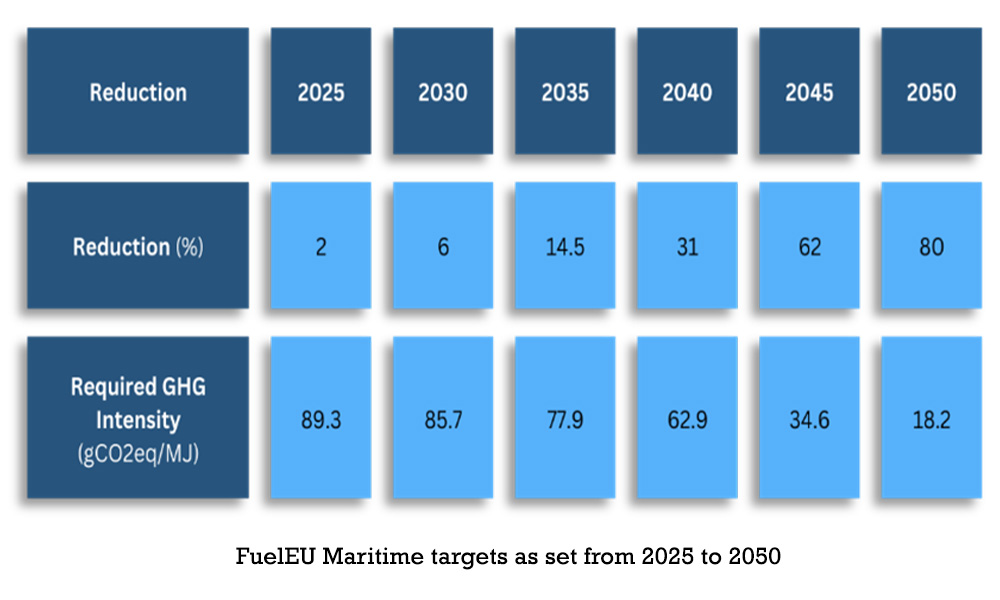
Maritec FuelEU Maritime targets

Marine environmental services and fuel testing solutions company CTI-Maritec on Friday (27 December) shared an update detailing the workings of the upcoming FuelEU Maritime regulation effective next year:

With its impending implementation on 01 January 2025, the FuelEU Maritime Regulation will be enforced by the EU for all ships trading within the EU or European Economic Area (EEA). FuelEU Maritime sets ‘Green House Gas (GHG) Intensity’ targets (not to be exceeded) on the annual average GHG Intensity of energy used by vessels.

The GHG Intensity targets are strategically reduced every 5 years, set from 2025 up to 2050. This will start at a 2% reduction of GHG Intensity in 2025, increasing to 6% in 2030, and accelerating from 2035 to reach an 80% reduction by 2050.

How It Works & Key Aspects to Note

  • GHG Intensity is measured as GHG emissions per energy unit (gCO2e/MJ) and, in turn, GHG emissions are calculated in a Well-To-Wake (WTW) perspective.
  • The calculation takes into account emissions related to the extraction, cultivation, production and transportation of fuel, in addition to emissions from energy used on board the ship.
  • The baseline for the calculation is the average WTW GHG Intensity of the fleet in 2020 (HFO 91.16 gCO2e/MJ).
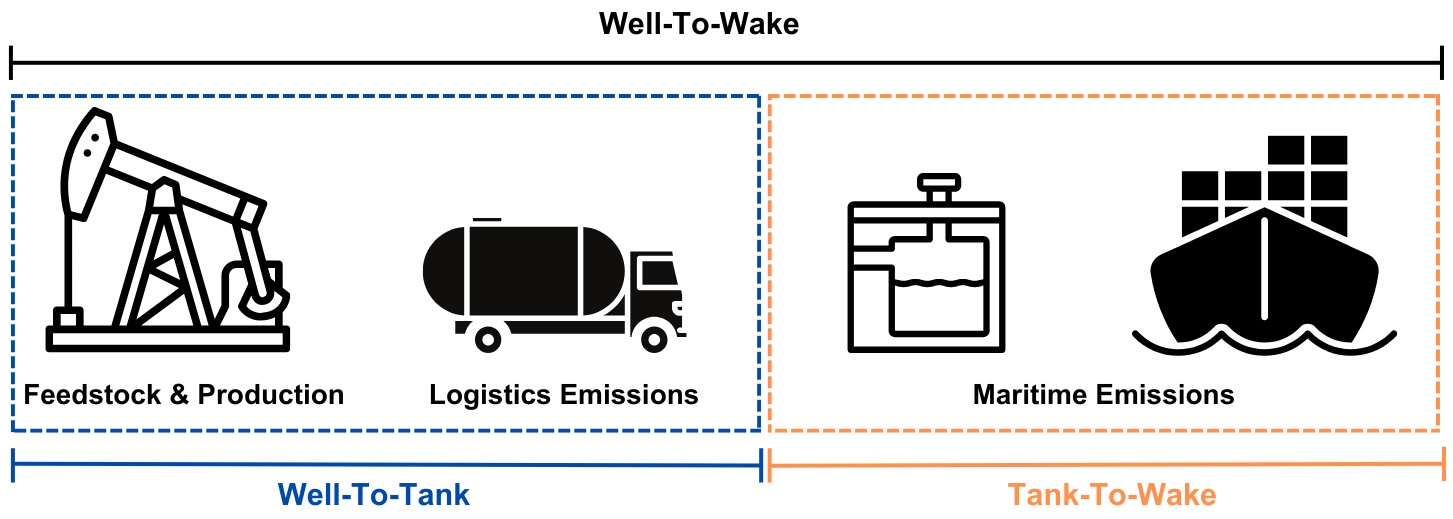
Well to wake

  • The GHG intensity requirement applies to 100% of energy used on voyages and port calls within the EU or EEA, and 50% of energy used on voyages into or out of the EU or EEA.
  • Not complying with the WTW GHG intensity target from 2025 will result in a penalty of approx. EUR 30 per tonne of VLSFO-equivalent.
  • Owing to its GHG Intensity, fossil fuels except LNG will not comply from 2025 onwards.
  • Vessels require only approx. 15% adoption of B24 BioFuel for EU voyages fuel consumption to avoid penalty
  • Use of B24 BioFuel is a “ready solution” in your marine energy transition journey.
  • Ship owners must purchase fuel from Traders with EU recognized Sustainability Certification (such as ISCC EU)

Recommended Plan of Action for Ship Owners

CTI-Maritec recommends the following as key overarching actions to help set you on course in your journey towards compliance with FuelEU Maritime, however must state that the same is not limited to only the below:

  • Submit a FuelEU Monitoring Plan to an accredited verifier. This plan should outline how you intend to monitor and report emissions for each ship in your fleet. This should be completed by 31 August 2024 or within 2 months after first port of call in 2025.
  • Start reporting key data related to FuelEU Maritime from 1 January 2025. This data includes fuel consumption, carbon emissions, and distance travelled.
  • Submit the individual ship’s FuelEU reports by 31 January 2026.
  • By 30 April 2026, have the compliance balance approved in the FuelEU Maritime database
  • By 30 June 2026, have the FuelEU Document of Compliance on board. This is also the penalty payment deadline.

What Mechanisms to Adopt to Ensure You are Meeting your FuelEU Maritime Targets

  • Use energy sources of a lower well-to-wake GHG intensity, such as sustainable biofuels like B24 BioFuel, renewable fuels of non-biological origin (RFNBO), recycled carbon fuels (RCF), Fossil LNG/LPG, shore power, wind-assisted propulsion, etc.
  • Ensure fuel is purchased from traders with EU recognized Sustainability Certification (achieved when systems such as the ISCC EU scheme is adopted)
  • Use of flexibility mechanisms, such as borrowing an advance compliance surplus from the next year (maximum 2%, not allowed for two consecutive periods) or include the ship’s compliance balance in a pool of ships (also possible in collaboration with other companies)
  • For Fuel Suppliers: Integrate robust systems established by credible institutes such as the ISCC (International Sustainability and Carbon Certification) EU Schemes into your organisations procedures, which ensures sustainability in feedstock production (e.g. Proof-of-Sustainability documents from fuel traders), traceability of sustainable products through the supply chain as well as credible, verified reductions of life cycle emissions. With the ISCC system recognized under the EU’s revised Renewable Energy Directive (“RED II”) as well as other major energy markets, ISCC certification is set to play a major role under the upcoming FuelEU Maritime regulation and beyond.


Photo credit and source: CTI-Maritec
Published: 31 December 2024

Continue Reading

Biofuel

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Marine biofuel growth hindered by economic squeezes and fragmented policies, requiring predictable carbon pricing and demand guarantees to scale.
Admin

Published

on

By

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Bio-bunkers are not capacity constrained; they are economics constrained, and policy asymmetry is dictating where volumes materialise, according to international bunker trading firm Dan-Bunkering.

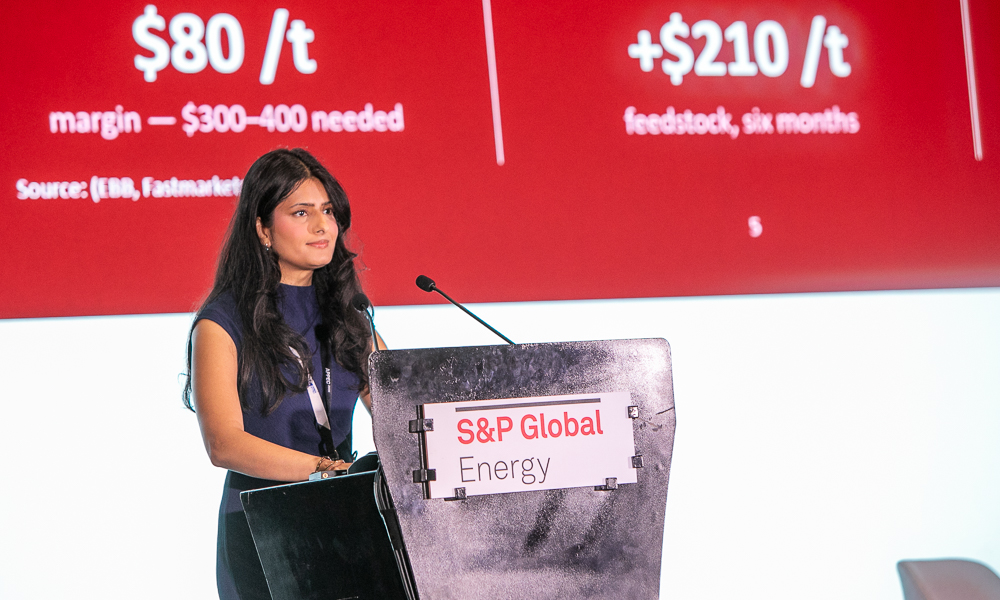
Mahnoor Samee, New Fuels Lead – APAC, Dan-Bunkering, was sharing a presentation Bio-Bunker Dynamics: Where is it Heading? with delegates at APPEC 2026 on Thursday (10 September) when she noted the following:

Disconnect in Production Margins

The primary constraint on marine biofuel, particularly Fatty Acid Methyl Ester (FAME), is not a lack of production capability, but a severe margin squeeze.

European FAME plants are operating at only 52% capacity, yet producers are unable to scale due to unfavourable economics.

Producers face a ‘falling ceiling’ as EU pooling credit prices have dropped by 50% in the past six months, and a ‘rising floor’ as Used Cooking Oil (UCO) feedstock costs have climbed significantly across the same period.

Consequently, the premium between UCO and Used Cooking Oil Methyl Ester (UCOME) has averaged around USD 80 pmt, well below the USD 300-400 pmt industry experts deem necessary for a sustainable business.

Contrasting Regional Demand

Demand for biofuels is meanwhile highly bifurcated and driven primarily by regional policy rather than global market trends.

In Singapore, bio-bunker sales have fallen by 45-60% year-over-year; as conventional fuel prices spiked, shipowners shifted to cheaper compliance alternatives such as pooling.

In contrast, Rotterdam has reached two-year highs in biofuel sales, supported by the Dutch ticket incentive system, which stabilises end-user pricing.

China has also seen a fourfold increase in demand over the past two years, driven by high EU exposure and voluntary emission goals, aided by lower logistics costs and strong trade routes to Europe.

Regulatory Fragmentation

Regulatory uncertainty remains a significant barrier to investment. The International Maritime Organization (IMO) is currently debating four conflicting proposals – ranging from delayed targets to tripled penalties – which has stalled projects and left the industry without a clear framework to engage.

In addition, the emergence of approximately 40 different carbon schemes globally, including the potential expansion of the UK Emissions Trading System (ETS) to include international voyages has created significant planning risks for shipowners.

The implementation of Renewable Energy Directive (RED) III in Europe has further complicated the landscape, creating a “RED III premium” that has caused some volume to shift to nearby ports like Antwerp to avoid higher costs, though Rotterdam remains resilient due to its national incentive schemes.

A critical challenge for the industry is how bunker buyers value biofuels. Many stakeholders compare the listed price of biofuel directly against conventional fuel or pooling, failing to account for “stacked benefits.”

When factoring in FuelEU compliance, reduced EU ETS carbon bills, and improved Carbon Intensity Indicator (CII) ratings, the “true premium” is significantly lower – estimated at USD 5-90 pmt rather than the sticker price of USD 300-400.

Policy Continues to Drive Demand

Looking toward 2030, the market faces a clear reality: 95% of the global fleet will still rely on conventional engines, making drop-in biofuels the only scalable emissions lever.

To unlock this potential, the industry requires a predictable carbon price and a mechanism to guarantee demand, similar to the Sustainable Aviation Fuel (SAF) levy model recently adopted in Singapore.

Without these structural changes, Asia’s technical capacity may remain underutilised, and the market will continue to consolidate in policy-advantaged hubs.


Photo credit: Manifold Times
Published: 17 September 2026

Continue Reading

Alternative Fuels

APPEC 2026: Panellists navigate maritime decarbonisation and alternative marine fuel strategies

Experts discuss maritime decarbonisation, emphasising global regulatory clarity, crew training, and collaborative strategies for adopting sustainable alternative marine fuels.
Admin

Published

on

By

IMG 9319 MT

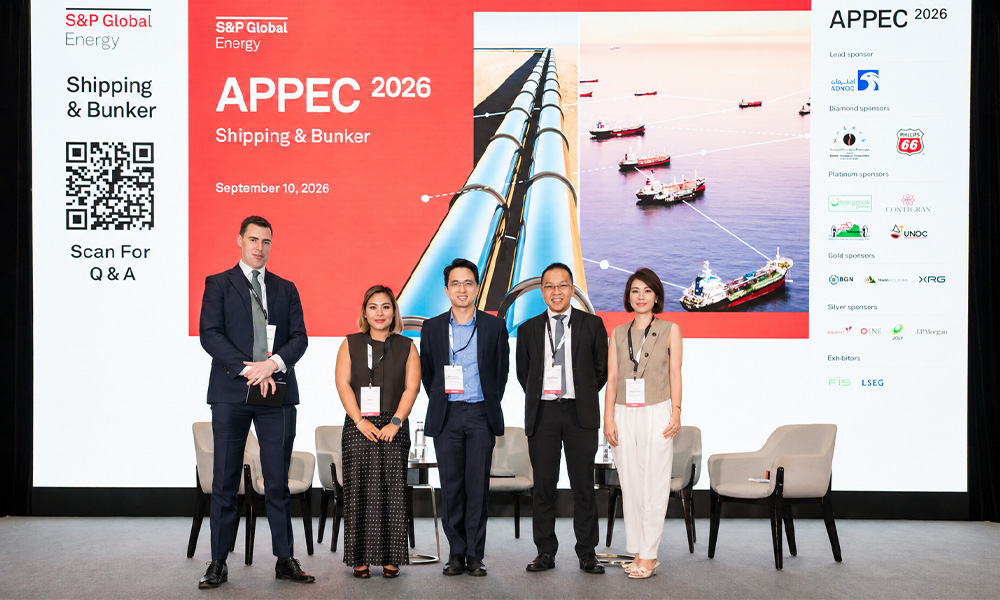
Panel members consisting of Singapore’s maritime and port regulator Maritime and Port Authority of Singapore (MPA), legal firm Rajah & Tann, bunker trading firm Sing Fuels, and the International Bunker Industry Association (IBIA) discussed the complexities of maritime decarbonisation at APPEC 2026 on Thursday (10 September).

The panel Balancing the Bunker Fuel Mix on the Path to Decarbonization moderated by John Morley, Global Director, Crude and Fuel Oil Markets, S&P Global Energy explored the complex landscape of maritime decarbonisation, sanctions fragmentation, and the transition to alternative marine fuels in Singapore.

Panellists broadly agree regulatory clarity – particularly from the International Maritime Organization (IMO) – is the single most critical enabler for large-scale investment, whilst highlighting regional fragmentation, crew competency gaps, and trade finance constraints pose significant near-term challenges.

Biofuels were seen as the most immediately scalable alternative marine fuel, with methanol and ammonia as longer-term prospects.

The following points were raised by panel members during discussion:

New Wei Siang, Director, Maritime Decarbonisation & Net-Zero Pathways, MPA, advocated for a global, IMO-led regulatory framework to guide shipping’s decarbonisation.

He believed regional patchwork regulations create unhelpful uncertainty, whereas a unified approach would be more helpful for long-term investment.

While acknowledging progress at recent IMO inter-sessional meetings held in September has been “slow but deliberate,” he remains focused on the upcoming MEPC 85 scheduled from November 30 to December 3, 2026.

To address the technical and safety challenges of new bunker fuels, he pointed out the MPA has established the Maritime Energy Training Facility (METF) to upskill crews on handling future marine fuels including methanol.

Furthermore, the MPA has launched ten green and digital shipping corridor partnerships to trial alternative fuels, exchange knowledge, and raise safety standards.

Mr New emphasised Singapore’s goal is to serve as a comprehensive maritime hub, balancing global regulatory engagement with practical, collaborative efforts to build competency for the future.

Nathanael Lin, Partner, Shipping & International Trade, Rajah & Tann Singapore, highlighted the significant legal and commercial challenges posed by regulatory fragmentation.

He argued regional environmental rules, such as those in the EU, force shipowners to make high-stakes gambles on trade routes and infrastructure until the IMO codifies standards into MARPOL Annex VI.

He also noted sanctions compliance has become dramatically more complex, with competing unilateral regimes replacing the previous era of UN consensus, creating immense operational risk for industry participants.

Furthermore, Mr Lin warned trade finance frameworks are currently ill-equipped to handle the complexities of blended alternative bunker fuels; he recommended banks to actively upskill their compliance functions to support the maritime energy transition.

Finally, he observed while claims regarding alternative marine fuels remained low due to the sophistication of early adopters, they will likely rise as adoption broadens. He also flagged the future migration of residual fuel demand as a critical, under-examined industry issue.

Juwita Setiawan, Trading Manager & New Fuels Lead, Sing Fuels, emphasised the energy transition has been making bunkering increasingly complex due to overlapping regulations.

She advocated for holistic voyage planning, where shipowners consider total emissions, costs, and marine fuel flexibility rather than evaluating port calls in isolation. She highlighted the critical role of high-quality data, fuel flexibility, including dual-fuel capabilities and fuel optimisation as essential tools for navigating the increasingly complex energy transition and supporting a practical pathway towards decarbonisation.

Regarding market structure, Ms Setiawan believed a symbiotic partnership between large integrated energy companies – which provide necessary capital and infrastructure – and agile, specialist suppliers is vital for success.

She identified biofuels and LNG as the most viable near-term maritime decarbonisation solutions, with methanol emerging as a mid-term option.

Ultimately, even though government incentives remain essential to help shipowners manage the high costs associated with adopting greener bunker fuels, regulatory clarity is the single most important factor to simplify market trading.

Looking ahead, she believes three things need to happen over the next three years:

  1. Clear and stable regulation – Shipowners and fuel suppliers need regulatory certainty and confidence to make long-term investments.
  2. Scale in supply and infrastructure – The industry needs to move beyond pilot projects towards reliable volumes, competitive pricing and stronger infrastructure across major bunkering hubs.
  3. Greater confidence in the fuels themselves – Common standards, proven technologies and reliable fuel performance will be essential to building trust and accelerating adoption.

“At Sing Fuels, we believe the transition is not about choosing one fuel for every vessel. It is about optimising the right fuel, at the right place, at the right cost, with the right emissions outcome – while keeping operational realities at the centre of the decision.

Siti Noraini Zaini, Regional Manager, Asia, IBIA, identified energy security and decarbonisation as objectives that need not be competing, noting that when energy security is under pressure, the immediate focus naturally shifts towards availability, reliability and affordability.

Over the longer term, however, a diversified marine fuel mix ultimately enhances industry resilience.

She stressed low carbon fuels alone is insufficient; shipowners need confidence that fuels will be available to meet the demand, where they are needed and at commercially manageable prices.

A critical focus for Ms Siti is the parallel development of standards. She warned the industry could not wait for the market to mature before establishing protocols. Standards for fuel quality measurement, green bunkering procedures, safety, and crew competency must be developed alongside the fuels themselves.

Looking ahead, she identified the upcoming MEPC 85 meeting as the industry’s primary regulatory watchpoint. Achieving clarity at the meeting is essential to enable the safe, financed, and commercially viable bunkering of new marine fuels, ensuring shipping’s decarbonisation transition remains both practical and sustainable.


Photo credit: S&P Global
Published: 14 September 2026

Continue Reading

FuelEU

Ahti Climate and DNV connect verified emissions data to FuelEU pooling platform

New integration connects Ahti’s FuelEU pooling platform with DNV’s verification services, Veracity, helping customers reduce manual administration and streamline compliance.
Admin

Published

on

By

Ahti Climate brings DNV-verified emissions data into FuelEU pooling platform

Ahti Climate on Monday (31 August) announced a new integration with Veracity, DNV’s independent industry cloud platform, enabling shipowners and operators to seamlessly transfer DNV-verified emissions data into Ahti’s FuelEU pooling platform. 

The integration simplifies emissions reporting by connecting operational data verification with FuelEU compliance workflows, helping customers reduce manual administration, improve data quality and confidently meet regulatory requirements.

For customers such as shipping company Bore Ltd, the integration streamlines the flow of emissions data between verification and compliance systems. Raw fuel consumption data is automatically converted into the required OVD format and submitted for DNV verification through Veracity. Once verified, the emissions figures are securely shared with Ahti’s FuelEU pooling platform, creating a more efficient workflow with less manual administration and greater confidence in reported emissions data.

“Being on one of the surplus generators of the pool, trust in the data is everything for us – we need to know the numbers we’re selling hold up to scrutiny. With verified emissions data flowing straight from Veracity by DNV into the Ahti Pooling Platform, we no longer have to manually cross-check figures before every transaction. It gives us confidence that what we’re bringing to the pool is accurate, and that our partners can rely on it too,” said Marcus Strand ICT Manager at Bore Ltd. 

The integration enables customers to:

  • Reduce manual data entry and administrative workload
  • Improve data quality and reduce the risk of reporting errors
  • Securely exchange verified emissions data across systems and stakeholders
  • Increase transparency and confidence in compliance reporting
  • Connect commercial, operational and compliance workflows
  • Reduce turnaround times for reporting and voyage settlements

“Every partnership we build comes back to the same question: does this make compliance easier for shipowners? With Veracity by DNV, the answer is clearly yes – verified data, connected systems, and one less thing for our customers to worry about,” said Risto-Juhani Kariranta, CEO of Ahti Climate. 

With connectivity to the majority of the world fleet, Veracity’s trusted partner ecosystem, combined with Ahti’s expertise in FuelEU pooling, gives shipowners a more connected approach to emissions verification and compliance. By enabling verified data to flow securely between systems, the partnership helps customers reduce complexity and get greater value from their data and access a growing network of digital solutions.


Photo credit: Ahti Climate
Published: 1 September, 2026

Continue Reading

Trending