Connect with us

Biofuel

Argus Media: Rotterdam 2Q biomarine sales overtake Singapore

It is the first quarter this has happened since the EU imposed anti-dumping duties (ADDs) on Chinese-origin biodiesel in the third quarter of 2024, according to Argus.

Admin

Published

on

resized argusmedia

Rotterdam marine biodiesel blend sales in the second quarter were above those in Singapore, according to official data from both ports, the first quarter this has happened since the EU imposed anti-dumping duties (ADDs) on Chinese-origin biodiesel in the third quarter of 2024.

Marine biodiesel blend sales in the Port of Rotterdam were up sharply on the year and more than double the previous quarter (see table).

Market participants reported firmer demand following the start of the US-Iran war. The war changed pricing dynamics between marine biodiesel blends and conventional fuels, leading to discounts for the former. These initially failed to support significant demand growth, evidenced by declining sales in the first quarter. Then, volatility weighed on overall trading activity and buyers were hesitant to make significant changes to their procurement strategy based on what was perceived as an acute price spread at the time.

But demand rose as the war extended, which led to higher blend sales in the second quarter.

An initial agreement to end the war was signed on 18 June by the US and Iran, which led to easing conventional fuel prices and a return to traditional dynamics, with fossil bunker fuels back at a discount to marine biodiesel blends.

But this agreement collapsed and hostilities resumed, leading to sharp increases in oil futures prices and a return to discounts for some marine biodiesel blends.

B100 Advanced fatty acid methyl ester (Fame) dob Netherlands has averaged a discount of about $86/t to marine gasoil (MGO) dob ARA since hostilities restarted, when accounting for EU emissions trading system (ETS) costs for an intra-EU voyage.

In that time, Singapore marine biodiesel prices — which had been mostly cheaper than EU equivalents — posted sharp gains and sales fell as a result.

EU ADDs on Chinese-origin biodiesel supported flows into Singapore, which ended up in the bunker pool, resulting in cheaper prices and higher sales than Rotterdam for more than 18 months. B24 dob Singapore prices averaged $753/t when accounting for EU ETS costs from August 2024 to February 2026, compared with $803/t for the cheapest European option, B30 Advanced Fame and VLSFO dob Netherlands. The latter averaged $1,080/t in March-June this year, compared with $1,110/t for B24 Singapore.

This change is reflected in sales data. Marine biodiesel blend sales in Singapore fell sharply on the year and on the quarter in April-June (see table).

Another reason for the sharp increase in sales could be attributed to changes stemming from the EU’s renewable energy directive (RED III). The Netherlands unilaterally implemented RED III mandates for international maritime starting this year.

Participants have pointed to diminishing demand in the Mediterranean region for marine biodiesel blends, particularly from non-passenger vessel segments, some of which may have been absorbed into Rotterdam because of more competitive pricing.

Bio-LNG volumes continued to rise, as it has become a popular option for generating FuelEU Maritime compliance due to a very competitive abatement cost.

Biomethanol sales more than doubled on the quarter, but down on the year. Volumes for ethanol as a bunker fuel were reported in Rotterdam port official data for the first time, following an initial ethanol-methanol blend bunkering operation in May. Ethanol is seen as an option to decarbonise maritime transport and meet regulations, and companies have been trialling its use. Danish shipowner Maersk completed its first voyage using 100pc ethanol in the first quarter on a dual-fuel methanol engine and is investing in further tests.

By Hussein Al-Khalisy

Note: Tables mentioned in the article can be found here


Photo credit and source: Argus Media
Published: 29 July, 2026

Continue Reading

Biofuel

IMO issues shipboard checklist for FAME-based biofuel blends

Checklist is intended to help vessel operators navigate some of the practical considerations involved when bunkering and consuming biofuel blends, particularly when using them for the first time.
Admin

Published

on

By

RESIZED IMO Building

The International Maritime Organization (IMO) on Wednesday (16 September) said the Shipboard Biofuel Blend Checklist for FAME-based biofuels has now been issued as an annex to document MEPC 85/INF.10.

The checklist was developed by the IBIA Technical Working Group as part of the ongoing update of the IBIA/BIMCO Shipmaster’s Bunkering Manual and is intended to help vessel operators navigate some of the practical considerations involved when bunkering and consuming biofuel blends, particularly when using them for the first time. 

It covers a range of areas, including fuel assessment, compatibility checks, tank preparation, water management, bunkering operations, storage and machinery performance monitoring.

As the use of biofuel blends continues to grow, IMO said having clear and practical guidance for crews and operators is increasingly important. 

The checklist is based on the CIMAC Guideline 04|2024, Marine fuels containing FAME, and is intended as a practical tool to support good fuel management onboard.

“It’s great to see the work now formally included in an IMO document and available to its membership,” IMO said. 

Note: The checklist can be viewed here


Photo credit: International Maritime Organization
Published: 17 September, 2026

Continue Reading

Biofuel

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Marine biofuel growth hindered by economic squeezes and fragmented policies, requiring predictable carbon pricing and demand guarantees to scale.
Admin

Published

on

By

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Bio-bunkers are not capacity constrained; they are economics constrained, and policy asymmetry is dictating where volumes materialise, according to international bunker trading firm Dan-Bunkering.

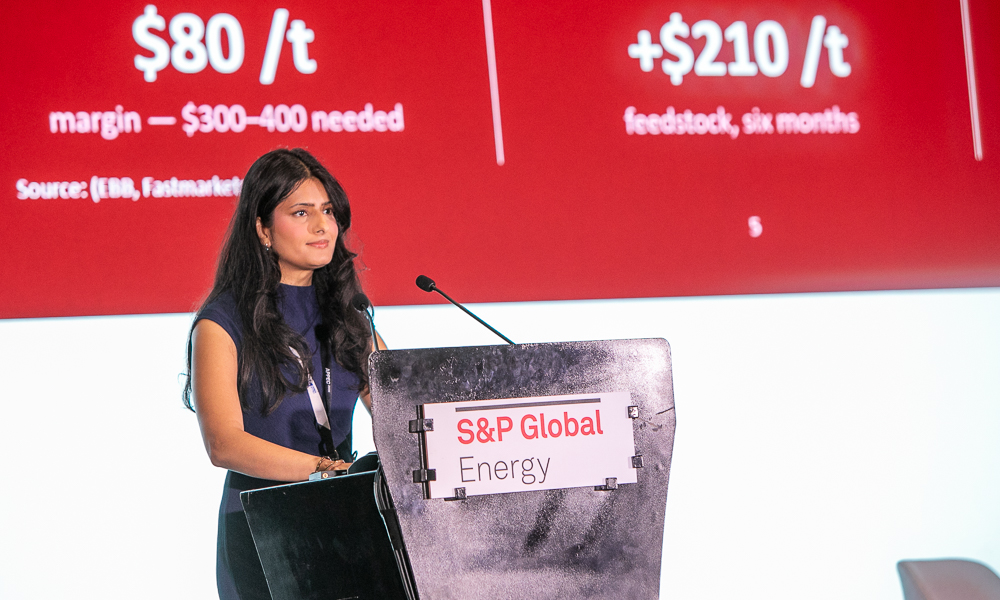
Mahnoor Samee, New Fuels Lead – APAC, Dan-Bunkering, was sharing a presentation Bio-Bunker Dynamics: Where is it Heading? with delegates at APPEC 2026 on Thursday (10 September) when she noted the following:

Disconnect in Production Margins

The primary constraint on marine biofuel, particularly Fatty Acid Methyl Ester (FAME), is not a lack of production capability, but a severe margin squeeze.

European FAME plants are operating at only 52% capacity, yet producers are unable to scale due to unfavourable economics.

Producers face a ‘falling ceiling’ as EU pooling credit prices have dropped by 50% in the past six months, and a ‘rising floor’ as Used Cooking Oil (UCO) feedstock costs have climbed significantly across the same period.

Consequently, the premium between UCO and Used Cooking Oil Methyl Ester (UCOME) has averaged around USD 80 pmt, well below the USD 300-400 pmt industry experts deem necessary for a sustainable business.

Contrasting Regional Demand

Demand for biofuels is meanwhile highly bifurcated and driven primarily by regional policy rather than global market trends.

In Singapore, bio-bunker sales have fallen by 45-60% year-over-year; as conventional fuel prices spiked, shipowners shifted to cheaper compliance alternatives such as pooling.

In contrast, Rotterdam has reached two-year highs in biofuel sales, supported by the Dutch ticket incentive system, which stabilises end-user pricing.

China has also seen a fourfold increase in demand over the past two years, driven by high EU exposure and voluntary emission goals, aided by lower logistics costs and strong trade routes to Europe.

Regulatory Fragmentation

Regulatory uncertainty remains a significant barrier to investment. The International Maritime Organization (IMO) is currently debating four conflicting proposals – ranging from delayed targets to tripled penalties – which has stalled projects and left the industry without a clear framework to engage.

In addition, the emergence of approximately 40 different carbon schemes globally, including the potential expansion of the UK Emissions Trading System (ETS) to include international voyages has created significant planning risks for shipowners.

The implementation of Renewable Energy Directive (RED) III in Europe has further complicated the landscape, creating a “RED III premium” that has caused some volume to shift to nearby ports like Antwerp to avoid higher costs, though Rotterdam remains resilient due to its national incentive schemes.

A critical challenge for the industry is how bunker buyers value biofuels. Many stakeholders compare the listed price of biofuel directly against conventional fuel or pooling, failing to account for “stacked benefits.”

When factoring in FuelEU compliance, reduced EU ETS carbon bills, and improved Carbon Intensity Indicator (CII) ratings, the “true premium” is significantly lower – estimated at USD 5-90 pmt rather than the sticker price of USD 300-400.

Policy Continues to Drive Demand

Looking toward 2030, the market faces a clear reality: 95% of the global fleet will still rely on conventional engines, making drop-in biofuels the only scalable emissions lever.

To unlock this potential, the industry requires a predictable carbon price and a mechanism to guarantee demand, similar to the Sustainable Aviation Fuel (SAF) levy model recently adopted in Singapore.

Without these structural changes, Asia’s technical capacity may remain underutilised, and the market will continue to consolidate in policy-advantaged hubs.


Photo credit: Manifold Times
Published: 17 September 2026

Continue Reading

Alternative Fuels

APPEC 2026: LNG and methane pathway a ‘pragmatic’ decarbonisation route for shipping, states Shell

LNG has become the dominant alternative bunker fuel for the marine sector, with the dual-fuel fleet growing by 8% in just eight months between late 2025 and mid-2026.
Admin

Published

on

By

Chua Han Wee, Strategic Customer Director, Shell Marine

Liquefied natural gas (LNG) is a resilient, scalable “methane pathway” using existing systems for shipping to decarbonise, Chua Han Wee, Strategic Customer Director, Shell Marine told delegates at APPEC 2026 on Thursday (10 September).

Though the material is supported by expanding infrastructure and improving methane management, adoption is primarily regulation-led, with high-cost environments dampening alternative investment.

In his presentation Looking Ahead: The Methane Pathway for Shipping’s Energy Transition Mr Chua highlighted the global LNG market has expanded by nearly 60% over the last decade, with regasification infrastructure growing in parallel across various geographies.

He noted LNG today represents the largest alternative-fuelled fleet, with the dual-fuel LNG fleet growing by 8% in the first eight months of 2026.

Despite current geopolitical disruptions in the Middle East causing spot price volatility, he argued the LNG market is mature and resilient, capable of rebalancing through levers like storage drawdowns, fuel switching, and demand management.

Looking forward, he pointed to record levels of liquefaction projects taking Final Investment Decision (FID) in 2025 and 2026, with approximately 200 million tons of new LNG supply expected to come online from the early 2030s, which may outstrip demand growth and improve fuel availability.

The following main points were covered in the presentation:

‘Methane Pathway’ and Progressive Emissions Reduction

Mr Chua presented the “methane pathway” as a pragmatic, scalable decarbonisation route that utilises the same storage, handling, and engine infrastructure for different LNG fuel types (LNG → bio-LNG → synthetic LNG). This pathway allows for progressive emissions reduction utilising LNG material:

  • LNG: Provides immediate greenhouse gas (GHG) reductions on a well-to-wake basis compared to conventional fuel oil, while also improving air quality by reducing soot, NOx, and particulate matter.
  • Bio-LNG*: Already available as a marine fuel today, it can reduce GHG emissions by 33% to 200% depending on the feedstock and processing.
  • Synthetic LNG*: Synthetic LNG: Currently in the pre-commercial stage, it is expected to reduce GHG emissions by 53% to 91%.

Progress in Methane Abatement Across LNG Industry

The LNG industry is meanwhile making tangible progress in managing methane emissions across the value chain:

  • Upstream: Members of the Oil and Gas Climate Initiative (OGCI) have reduced methane emissions intensity by over 50% since 2016, with Shell averaging 0.05% in 2023.
  • Shipping: Over 90% of LNG-fuelled vessels currently on order are fitted with engines designed for low methane slip (less than 0.8%).
  • Technology: Shell is currently conducting a year-long trial of a Methane Abatement Catalyst (MAC) on an LNG bunkering vessel in Singapore to remove unburned methane from engine exhaust.

Regulatory Enablers Needed for Scale

To support the methane pathway, identified several critical regulatory enablers need to be addressed at the International Maritime Organization (IMO) level:

  • Updated Default Factors: Conservative default values (such as the current 18.5 gCO2/MJ in FuelEU Maritime) need to progress toward more representative, asset-level data; a study by Rystad Energy using asset-level data suggest a lower value of 14.0 gCO2/MJ from Norway and the Republic of Korea.
  • Recognition of Avoided Emissions: The formal recognition of avoided emissions from bio- and synthetic pathways within a lifecycle assessment framework, similar to existing models in the EU Renewable Energy Directive and US Low Carbon Fuel Standards.
  • Mass Balancing: Acceptance of “mass balancing” as a chain of custody model across interconnected gas infrastructure, which is already recognised by the EU.

“We advocate at the IMO for LNG default factors to reflect the latest assessments, as these provide more representative emissions estimates,” said Mr Chua.

“The current LNG default factor under FuelEU Maritime is 18.5 gCO₂/MJ. Norway and the Republic of Korea have proposed to GESAMP a lower LNG default factor of 14.0 gCO₂/MJ, based on analysis by Rystad Energy.

“Unlike regional-average approaches, the Rystad study uses asset-level data that reflects the LNG facilities supplying the marine bunker market, providing a more representative estimate of emissions performance.”

*Disclaimer: All GHG reduction figures mentioned in the presentation are calculated using fuel default values from FuelEU Maritime regulation (EU) 2023/1805. These are compared to Very Low Sulphur Fuel Oil (VLSFO), the differences in greenhouse gas (GHG) reductions on a well-to-wake basis for each fuel are due to variations in the materials used, how the fuel is made, and how emissions are measured.


Photo credit: Manifold Times
Published: 16 September 2026

Continue Reading

Trending