Connect with us

EU ETS

EmissionLink urges fair treatment for shipping under proposed EU ETS expansion

While broader coverage may support Europe’s climate objectives, EmissionLink warned that it will also create new commercial, contractual and compliance challenges.

Admin

Published

on

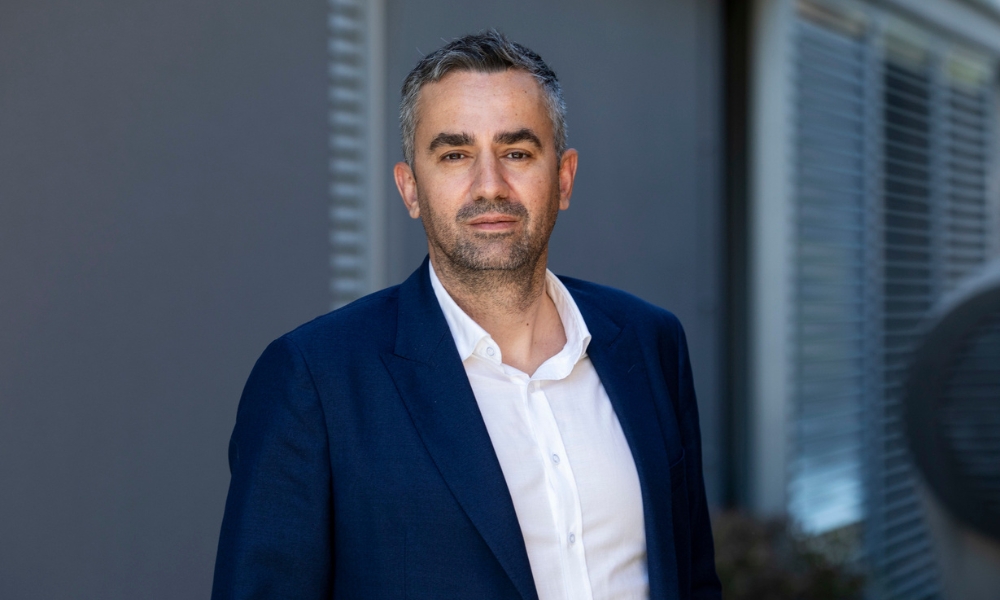
Philippos Ioulianou, EmissionLink

The proposed expansion of the EU Emissions Trading System (EU ETS) must provide fair treatment for shipping and deliver meaningful emissions reductions, according to emissions compliance specialist EmissionLink on Wednesday (5 August). 

The European Commission’s proposals would extend the system to offshore activities from 2027 and certain vessels between 400 and 5,000 GT from 2029. 

While broader coverage may support Europe’s climate objectives, EmissionLink warned that it will also create new commercial, contractual and compliance challenges.

Philippos Ioulianou, Managing Director of EmissionLink, said: “Expanding the EU ETS will not automatically make it more effective. The system must be coherent, proportionate and capable of delivering practical decarbonisation.

“Shipping should not pay twice for the same tonne of emissions. If the EU ETS operates alongside a future IMO carbon-pricing mechanism, there must be an automatic and transparent way to recognise payments and reconcile liabilities.”

The inclusion of offshore activities will be particularly complex. Offshore vessels may remain at worksites for extended periods, with operational control, fuel consumption and emissions responsibilities divided between owners, charterers, contractors and project developers. This means ETS obligations will increasingly need to be addressed in charterparties and project agreements, including responsibility for emissions monitoring, purchasing allowances and managing carbon-price exposure.

Smaller operators entering the system from 2029 may also face disproportionate compliance demands, as many lack the specialist teams, established data systems and carbon-market expertise available to larger shipping companies.

EmissionLink has welcomed proposals to align EU Monitoring, Reporting and Verification requirements more closely with FuelEU Maritime reporting, as well as changes intended to prevent circumvention through transhipment. However, the company is also calling for at least 50% of the ETS revenues generated by shipping to be reinvested in maritime decarbonisation at national level.

Ioulianou added: “Carbon pricing must be matched by practical investment. A meaningful share of shipping-generated revenues should support sustainable fuels, port infrastructure, vessel retrofits and credible energy-efficiency technologies.

“The credibility of the EU ETS will ultimately depend not on how much money it raises, but on whether it treats shipping fairly and helps the industry reduce emissions.”


Photo credit: EmissionLink
Published: 6 August, 2026

Continue Reading

Biofuel

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Marine biofuel growth hindered by economic squeezes and fragmented policies, requiring predictable carbon pricing and demand guarantees to scale.
Admin

Published

on

By

APPEC 2026: Future of bio-bunkers determined by economics and regulations, highlights Dan-Bunkering

Bio-bunkers are not capacity constrained; they are economics constrained, and policy asymmetry is dictating where volumes materialise, according to international bunker trading firm Dan-Bunkering.

Mahnoor Samee, New Fuels Lead – APAC, Dan-Bunkering, was sharing a presentation Bio-Bunker Dynamics: Where is it Heading? with delegates at APPEC 2026 on Thursday (10 September) when she noted the following:

Disconnect in Production Margins

The primary constraint on marine biofuel, particularly Fatty Acid Methyl Ester (FAME), is not a lack of production capability, but a severe margin squeeze.

European FAME plants are operating at only 52% capacity, yet producers are unable to scale due to unfavourable economics.

Producers face a ‘falling ceiling’ as EU pooling credit prices have dropped by 50% in the past six months, and a ‘rising floor’ as Used Cooking Oil (UCO) feedstock costs have climbed significantly across the same period.

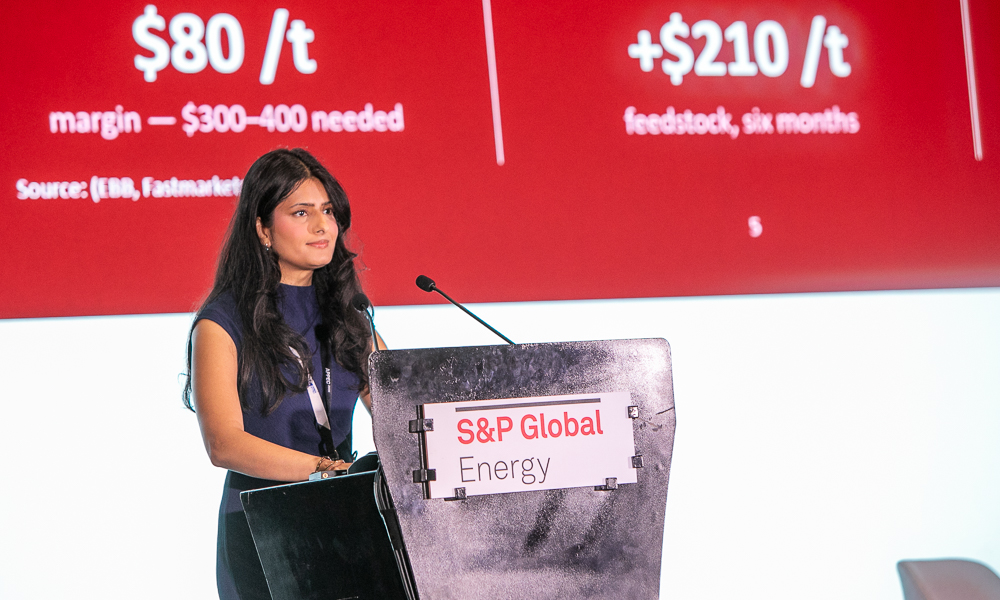
Consequently, the premium between UCO and Used Cooking Oil Methyl Ester (UCOME) has averaged around USD 80 pmt, well below the USD 300-400 pmt industry experts deem necessary for a sustainable business.

Contrasting Regional Demand

Demand for biofuels is meanwhile highly bifurcated and driven primarily by regional policy rather than global market trends.

In Singapore, bio-bunker sales have fallen by 45-60% year-over-year; as conventional fuel prices spiked, shipowners shifted to cheaper compliance alternatives such as pooling.

In contrast, Rotterdam has reached two-year highs in biofuel sales, supported by the Dutch ticket incentive system, which stabilises end-user pricing.

China has also seen a fourfold increase in demand over the past two years, driven by high EU exposure and voluntary emission goals, aided by lower logistics costs and strong trade routes to Europe.

Regulatory Fragmentation

Regulatory uncertainty remains a significant barrier to investment. The International Maritime Organization (IMO) is currently debating four conflicting proposals – ranging from delayed targets to tripled penalties – which has stalled projects and left the industry without a clear framework to engage.

In addition, the emergence of approximately 40 different carbon schemes globally, including the potential expansion of the UK Emissions Trading System (ETS) to include international voyages has created significant planning risks for shipowners.

The implementation of Renewable Energy Directive (RED) III in Europe has further complicated the landscape, creating a “RED III premium” that has caused some volume to shift to nearby ports like Antwerp to avoid higher costs, though Rotterdam remains resilient due to its national incentive schemes.

A critical challenge for the industry is how bunker buyers value biofuels. Many stakeholders compare the listed price of biofuel directly against conventional fuel or pooling, failing to account for “stacked benefits.”

When factoring in FuelEU compliance, reduced EU ETS carbon bills, and improved Carbon Intensity Indicator (CII) ratings, the “true premium” is significantly lower – estimated at USD 5-90 pmt rather than the sticker price of USD 300-400.

Policy Continues to Drive Demand

Looking toward 2030, the market faces a clear reality: 95% of the global fleet will still rely on conventional engines, making drop-in biofuels the only scalable emissions lever.

To unlock this potential, the industry requires a predictable carbon price and a mechanism to guarantee demand, similar to the Sustainable Aviation Fuel (SAF) levy model recently adopted in Singapore.

Without these structural changes, Asia’s technical capacity may remain underutilised, and the market will continue to consolidate in policy-advantaged hubs.


Photo credit: Manifold Times
Published: 17 September 2026

Continue Reading

Alternative Fuels

APPEC 2026: Panellists navigate maritime decarbonisation and alternative marine fuel strategies

Experts discuss maritime decarbonisation, emphasising global regulatory clarity, crew training, and collaborative strategies for adopting sustainable alternative marine fuels.
Admin

Published

on

By

IMG 9319 MT

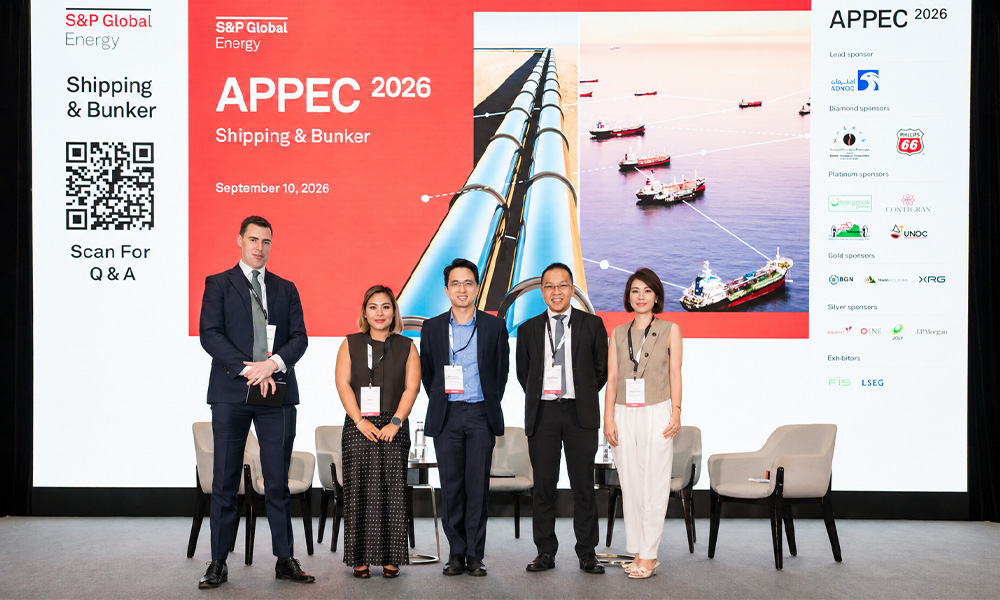
Panel members consisting of Singapore’s maritime and port regulator Maritime and Port Authority of Singapore (MPA), legal firm Rajah & Tann, bunker trading firm Sing Fuels, and the International Bunker Industry Association (IBIA) discussed the complexities of maritime decarbonisation at APPEC 2026 on Thursday (10 September).

The panel Balancing the Bunker Fuel Mix on the Path to Decarbonization moderated by John Morley, Global Director, Crude and Fuel Oil Markets, S&P Global Energy explored the complex landscape of maritime decarbonisation, sanctions fragmentation, and the transition to alternative marine fuels in Singapore.

Panellists broadly agree regulatory clarity – particularly from the International Maritime Organization (IMO) – is the single most critical enabler for large-scale investment, whilst highlighting regional fragmentation, crew competency gaps, and trade finance constraints pose significant near-term challenges.

Biofuels were seen as the most immediately scalable alternative marine fuel, with methanol and ammonia as longer-term prospects.

The following points were raised by panel members during discussion:

New Wei Siang, Director, Maritime Decarbonisation & Net-Zero Pathways, MPA, advocated for a global, IMO-led regulatory framework to guide shipping’s decarbonisation.

He believed regional patchwork regulations create unhelpful uncertainty, whereas a unified approach would be more helpful for long-term investment.

While acknowledging progress at recent IMO inter-sessional meetings held in September has been “slow but deliberate,” he remains focused on the upcoming MEPC 85 scheduled from November 30 to December 3, 2026.

To address the technical and safety challenges of new bunker fuels, he pointed out the MPA has established the Maritime Energy Training Facility (METF) to upskill crews on handling future marine fuels including methanol.

Furthermore, the MPA has launched ten green and digital shipping corridor partnerships to trial alternative fuels, exchange knowledge, and raise safety standards.

Mr New emphasised Singapore’s goal is to serve as a comprehensive maritime hub, balancing global regulatory engagement with practical, collaborative efforts to build competency for the future.

Nathanael Lin, Partner, Shipping & International Trade, Rajah & Tann Singapore, highlighted the significant legal and commercial challenges posed by regulatory fragmentation.

He argued regional environmental rules, such as those in the EU, force shipowners to make high-stakes gambles on trade routes and infrastructure until the IMO codifies standards into MARPOL Annex VI.

He also noted sanctions compliance has become dramatically more complex, with competing unilateral regimes replacing the previous era of UN consensus, creating immense operational risk for industry participants.

Furthermore, Mr Lin warned trade finance frameworks are currently ill-equipped to handle the complexities of blended alternative bunker fuels; he recommended banks to actively upskill their compliance functions to support the maritime energy transition.

Finally, he observed while claims regarding alternative marine fuels remained low due to the sophistication of early adopters, they will likely rise as adoption broadens. He also flagged the future migration of residual fuel demand as a critical, under-examined industry issue.

Juwita Setiawan, Trading Manager & New Fuels Lead, Sing Fuels, emphasised the energy transition has been making bunkering increasingly complex due to overlapping regulations.

She advocated for holistic voyage planning, where shipowners consider total emissions, costs, and marine fuel flexibility rather than evaluating port calls in isolation. She highlighted the critical role of high-quality data, fuel flexibility, including dual-fuel capabilities and fuel optimisation as essential tools for navigating the increasingly complex energy transition and supporting a practical pathway towards decarbonisation.

Regarding market structure, Ms Setiawan believed a symbiotic partnership between large integrated energy companies – which provide necessary capital and infrastructure – and agile, specialist suppliers is vital for success.

She identified biofuels and LNG as the most viable near-term maritime decarbonisation solutions, with methanol emerging as a mid-term option.

Ultimately, even though government incentives remain essential to help shipowners manage the high costs associated with adopting greener bunker fuels, regulatory clarity is the single most important factor to simplify market trading.

Looking ahead, she believes three things need to happen over the next three years:

  1. Clear and stable regulation – Shipowners and fuel suppliers need regulatory certainty and confidence to make long-term investments.
  2. Scale in supply and infrastructure – The industry needs to move beyond pilot projects towards reliable volumes, competitive pricing and stronger infrastructure across major bunkering hubs.
  3. Greater confidence in the fuels themselves – Common standards, proven technologies and reliable fuel performance will be essential to building trust and accelerating adoption.

“At Sing Fuels, we believe the transition is not about choosing one fuel for every vessel. It is about optimising the right fuel, at the right place, at the right cost, with the right emissions outcome – while keeping operational realities at the centre of the decision.

Siti Noraini Zaini, Regional Manager, Asia, IBIA, identified energy security and decarbonisation as objectives that need not be competing, noting that when energy security is under pressure, the immediate focus naturally shifts towards availability, reliability and affordability.

Over the longer term, however, a diversified marine fuel mix ultimately enhances industry resilience.

She stressed low carbon fuels alone is insufficient; shipowners need confidence that fuels will be available to meet the demand, where they are needed and at commercially manageable prices.

A critical focus for Ms Siti is the parallel development of standards. She warned the industry could not wait for the market to mature before establishing protocols. Standards for fuel quality measurement, green bunkering procedures, safety, and crew competency must be developed alongside the fuels themselves.

Looking ahead, she identified the upcoming MEPC 85 meeting as the industry’s primary regulatory watchpoint. Achieving clarity at the meeting is essential to enable the safe, financed, and commercially viable bunkering of new marine fuels, ensuring shipping’s decarbonisation transition remains both practical and sustainable.


Photo credit: S&P Global
Published: 14 September 2026

Continue Reading

EU ETS

EmissionLink warns shipowners of growing financial risk from delayed EUA transfers

Philippos Ioulianou warns shipowners and operators that waiting until September to secure and transfer EUAs is creating unnecessary financial, commercial and compliance risk as EU ETS enters its next phase.

Admin

Published

on

By

Philippos Ioulianou, EmissionLink

Emissions compliance specialist EmissionLink on Friday (11 September) has warned shipowners and operators that waiting until September to secure and transfer EU Allowances (EUAs) is creating unnecessary financial, commercial and compliance risk as the EU Emissions Trading System (EU ETS) enters its next phase.

Philippos Ioulianou, Managing Director of EmissionLink, said: “The problem is not the September deadline itself, but the industry’s habit of waiting until the last possible moment. This can push critical funding and compliance decisions to the brink and leave owners, managers and compliance providers carrying significant exposure.”

Following the first FuelEU Maritime compliance cycle, operators must also surrender EUAs covering their verified emissions before the end of September. However, EmissionLink said current practices between owners, charterers, managers and intermediaries can leave significant exposure unresolved until shortly before the deadline.

Many charter parties, including those incorporating BIMCO emissions trading provisions, allow charterers to transfer EUAs relatively close to the surrender date. While commercially flexible, EmissionLink said this can leave the party responsible for compliance exposed if allowances arrive late or are not transferred at all.

“Owners may be reluctant to buy allowances because the charterer is contractually liable, while charterers may delay because the contract permits them to”, added Mr Ioulianou. 

“In the meantime, the company responsible for compliance remains accountable to the regulator so that mismatch creates avoidable market risk.”

The issue is becoming increasingly significant as the EU ETS phase-in accelerates. The scheme covered 40% of shipping’s verified emissions for 2024, rising to 70% for 2025 and 100% for 2026. EmissionLink recommends verified emissions reports should therefore be treated as an early financial risk indicator rather than simply part of an annual administrative process.

Once verified emissions are known, owners and operators should quantify their EUA exposure, agree the allocation with charterers and establish clear transfer dates well ahead of September. The company is also calling for charter-party arrangements to move away from a last day approach to EUA transfers, with earlier milestones and clearer remedies for late delivery and associated costs.

Owners should also identify and purchase any known residual exposure at an early stage. This can include allowances arising from off-hire periods, operational adjustments or disputes, even where the owner’s eventual share represents only a small proportion of the vessel’s total liability. Delaying these purchases can expose companies not only to counterparty risk but also to movements in EUA prices.

Mr Ioulianou concluded: “EUAs now need to be treated as a core part of voyage economics, counterparty management and liquidity planning, not as a September administrative task. As exposure reaches 70% and then 100%, earlier allocation, earlier transfers and proactive purchasing will become essential to credible carbon compliance.”

By centralising emissions exposure, allowance allocation and transfer tracking, operators can gain earlier visibility of potential shortfalls and reduce the risk of a last-minute compliance scramble. As EU ETS exposure moves towards 100%, EmissionLink is calling for earlier allocation, earlier transfers and proactive purchasing as essential elements of effective carbon compliance and commercial risk management.


Photo credit: EmissionLink
Published: 14 September, 2026

Continue Reading

Trending