Alternative Fuels
Green corridors: A lane for zero-carbon shipping
Zero-emission fuels and vessels will need to start being deployed at scale over the next decade to achieve full decarbonization of the shipping sector by 2050.

This article is a collaborative effort by Martin Joerss, Arjen Kersing, Andrew Kramer, Detlev Mohr, and Matt Stone, representing views from McKinsey’s Sustainability and Travel, Logistics & Infrastructure Practices:
The shipping sector is the lifeblood of global trade, accounting for approximately 80 percent of all trade, with further growth expected. The sector also represents about 3 percent of total CO2 emissions—an amount that, if unchecked, could rise by as much as half by 2050.
Recognizing the need for climate action, the International Maritime Organization (IMO) has mandated emission reductions of 50 percent for all vessels by 2050. A number of countries—including Japan, the United Kingdom, and the United States—have declared a target for net-zero shipping emissions in the same time frame. To reach these goals, because ships have a 20- to 25-year operating life, the sector would need to implement comprehensive zero-emission programs over the next decade. The necessary technologies are available, but they would need to be deployed at not only greater scale and speed but also at lower cost. Zero-emission fuels cost significantly more than conventional fuels, increasing total cost of vessel ownership by between 40 and 60 percent, depending on the route.
Finding industry-wide solutions is challenging, given the varied and complex nature of the sector. One way to accelerate decarbonization is to implement “green corridors”: specific trade routes between major port hubs where zero-emission solutions are supported. A new report, The next wave: Green corridors, produced by the Getting to Zero Coalition in collaboration with the Global Maritime Forum, Mission Possible Partnership, and Energy Transitions Commission, with analytical support from McKinsey, probes the feasibility of two such selected corridors—with encouraging results.
Navigating to net zero via green corridors
Green corridors would establish favorable conditions for decarbonization, for they would allow policy makers to create an enabling ecosystem with targeted regulatory measures, financial incentives, and safety regulations. Policy makers could also consider regulations and incentives to lower the cost of green-fuel production, which could in turn help to mobilize demand for green shipping. Finally, green corridors could create secondary effects that reduce shipping emissions on other routes. For example, once the infrastructure to provide zero-emission fuel for one green corridor is in place, it can then be used for shipping on other, adjacent routes.
These corridors would ideally be large enough to include all relevant value-chain actors, such as fuel producers, cargo owners, and regulatory authorities. They would provide offtake certainty to fuel producers and send strong signals to vessel operators, shipyards, and engine manufacturers to ramp up investment in zero-emission shipping—making the risks more acceptable for all involved.
Zero-emission fuels have a major effect on the total cost of ownership (TCO) of vessels on the route. TCO includes all capital expenditure and operating expenses incurred during the lifetime of the ship. Elements include fuel cost, depreciation of the ship, cost of capital, daily running cost, voyage cost, and opportunity cost for lost cargo space if larger fuel tanks are needed for zero-emission fuels. TCO is an integral aspect of determining which routes, and which fuels, are viable for green shipping corridors. Sharing the burden and risk across the green corridor will be vital to bridge the “TCO gap” that comes from introducing zero-emission fuels.
The selection process for initial green corridors is crucial. Four critical building blocks are required for a potential green corridor: stakeholders that are committed to decarbonization and are willing to collaborate across the value chain; a viable fuel pathway (for more, see sidebar, “What fuels will power green shipping?”); customer demand for green shipping and initiatives to pool demand; and policy and regulation (for example, safety standards) that can narrow cost gaps and expedite adoption.
The report provides prefeasibility studies on two routes that have potential to become green corridors: the Australia–Japan iron-ore route and the Asia–Europe containership route. These routes show that accelerated decarbonization for the shipping industry is feasible and would provide stakeholders with the confidence to invest, coordinate, and deliver solutions at scale by 2030.
The Australia–Japan iron-ore route
In 2019, some 65 million metric tons of iron ore were exported from Australian mines to Japanese steelmakers, making this the third-largest dry-bulk trade route in the world. A total of 111 bulkers on the route burned approximately 550,000 metric tons of fuel oil in 2019—equal to 1.7 million metric tons of CO2 emissions. It would take 41 fully dedicated zero-emission vessels to decarbonize all iron-ore trade between Australia and Japan.
With the relative simplicity of the stakeholder environment, as well as strong existing political collaboration, the transformation of this route into a green corridor appears feasible. There is growing consensus among stakeholders on this route to decarbonize: already, 90 percent of the Australian iron ore exported to Japan is mined by companies with net-zero commitments, and Japanese steelmakers are exploring options to introduce green steel and to decarbonize their supply chains—which should allow for collaboration among miners, vessel operators, steel mills, fuel producers, and policy makers.
Equally importantly, Australia has good conditions, as well as planned capacity, for ample production of zero-emission fuel, especially green hydrogen and green ammonia. However, given supply dynamics and long-term cost advantage, analysis suggests it is likely that green ammonia will be the zero-emission fuel of choice for the corridor. Ammonia engines are expected to be available in 2024, with the first vessel operational in 2025; safety standards and bunkering infrastructure must be in place on this route by then.
Even so, analysis suggests that by 2030, an iron-ore bulk carrier that runs on green ammonia will still cost 65 percent more, in terms of the annualized end-to-end TCO, than an iron-ore bulk carrier that runs on fossil-heavy fuel oil. Most of the difference can be attributed to the higher cost of zero-carbon fuels such as green ammonia and green hydrogen (exhibit).

For shipping companies serving the Australia–Japan iron-ore route to switch to zero-carbon fuels and vessels, this cost gap would need to be narrowed. Stakeholders across the value chain can work together to pool demand, bridge the cost gap of fuel, and share the risk of building new zero-emission vessels. Partnerships between shipowners, steelmakers, and miners will be particularly significant, as such partnerships could help to derisk stakeholders’ investments, such as the capital expenditure required to build new zero-emission vessels.
An “insetting” mechanism is an example of a way to mobilize demand. Insetting refers to the process by which a company offsets emissions or other environmental or social impacts of another company within its own supply chain. Under this mechanism, vessel operators could buy green fuel from producers and in turn receive carbon credits compliant with the Science Based Targets initiative (SBTi). Other value-chain players could buy these carbon credits from the vessel operators to cover the iron ore shipped on this corridor.
The Asia–Europe container route
This route is the largest of the three major East–West containership routes and offers the greatest potential to reduce emissions. In 2019, approximately 24 million twenty-foot equivalent units (TEUs) were traded on the route, on 365 vessels. The ships burned approximately 11 million metric tons of fuel, accounting for roughly 3 percent of global shipping emissions—more than any other global trading route.
The Asia–Europe container route has a complex stakeholder environment, involving many vessel operators. The nature of container shipping, where one vessel might carry cargo from multiple owners, creates additional complexity. Nonetheless, the low cost of fuel and an enabling regulatory environment on the European leg of the route mean that this is a viable green corridor. Shipping decarbonization is a growing priority for policy makers, especially in the European Union, and European policy interventions affect the entire route. For instance, under the European Union’s “Fit for 55” legislative package, the Emissions Trading Scheme would apply to 50 percent of the shipping into and out of the European Union, which is a substantial part of the global market.
In addition, there is growing demand for decarbonization throughout the value chain, from diverse end-consumers to freight forwarders and shipping lines. As much as 70 percent of the total TEU capacity on the route is covered by five shipping lines—all committed to reducing GHG emissions by half (or more) by 2050.
Our analysis shows that the pipeline of announced green-fuel projects is more than sufficient to supply the 50 zero-emission new-build vessels that would be required to replace aging vessels on this corridor, factoring in economic growth on the route. These vessels could provide 1.2 million TEUs of green-container shipping by 2030: 17 percent of capacity on the route. Sustainable fuels could be made available on the route at several bunkering locations, including Europe, the Middle East, North Africa, and Singapore.
Still, a gap of 45 percent on TCO for this route is predicted to remain by 2030, with fuel cost again the primary driver. This means that it will be important to strengthen demand for zero-emission shipping. Multiyear offtake agreements could help to derisk investment in green fuels, as suppliers would be certain that the fuels they produce would be bought. Such agreements can be complemented by demand coalitions, allowing cargo owners to aggregate their commitments to buy green. Additionally, a corridor-based book-and-claim system would allow participants to ensure system boundaries and conditions for booking and claiming that meet their thresholds for quality and credibility. For instance, the system could exclude near-shore shipping or limit which fuels qualify.
In general, changes required to promote zero-emission container shipping include setting major milestones (such as a commitment among stakeholders to a green-corridor road map), aligning on a common fuel pathway, and mobilizing demand. Policy makers can also consider regulations and incentives that would further support the shift to green shipping. Establishing them in this corridor would send a clear demand signal through the supply chain and set the stage for global adoption of green shipping practices.
The prefeasibility studies of potential green corridors show how stakeholder collaboration can establish these corridors, helping the shipping industry to reach its goal of full decarbonization by 2050. Success will be built on credible fuel pathways, value-chain initiatives, and mobilized demand. Partnerships are crucial: the entire value chain—including cargo owners, fuel producers, and vessel operators—needs to come together, based on a shared commitment to zero-emission shipping. Policy makers can also consider various targeted changes that would encourage a transition to zero-emission shipping along particular corridors. If stakeholders agree on a credible, ambitious green-corridor plan and implement it together, the industry can contribute to the world’s progress toward net zero.
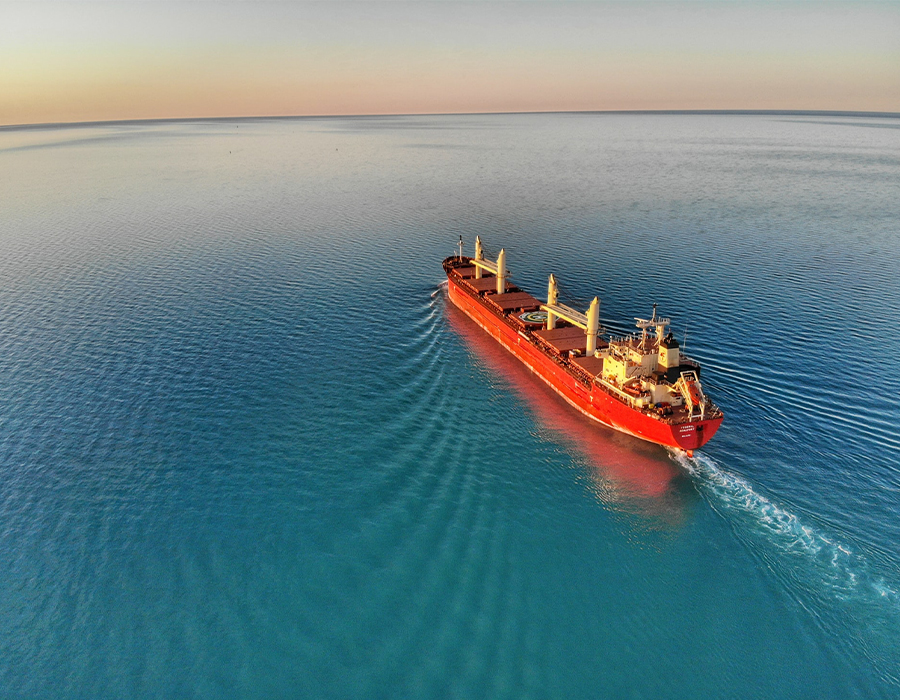
Photo credit: Chris Pagan from Unsplash
Source: McKinsey & Company
Published: 24 December, 2021
Alternative Fuels
Singapore-based Golden Island, Qingdao Port team up on alternative bunker fuels
Agreement covers green methanol, green ammonia and bio-LNG, with cooperation spanning fuel production and transportation through to storage, sales and bunkering.
Ammonia
HD HHI and HD KSOE secure ABS AiP for ammonia bunkering vessel design
ABS awarded approval in principle for the basic design of a 22,000 CBM bunkering vessel capable of supplying ammonia as marine fuel.
Alternative Fuels
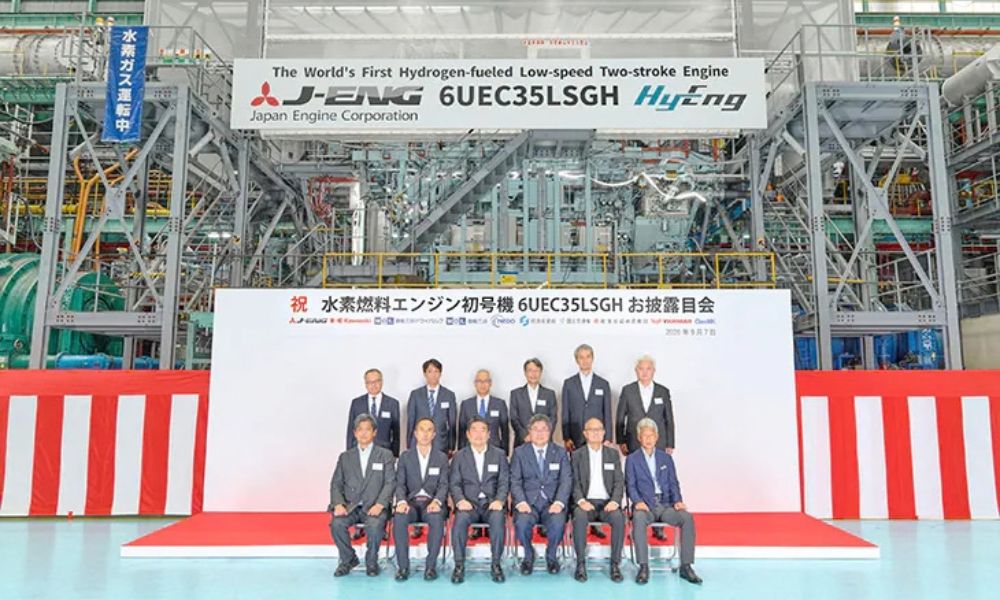
J-ENG completes land-based testing of hydrogen-fuelled marine engine
Engine will be installed on a 17,500 DWT multipurpose vessel to be built by Onomichi Dockyard for MOL and MOL Drybulk, with onboard demonstration testing scheduled to begin in April 2028.

OUR INDUSTRY PARTNERS

Singapore-based Golden Island, Qingdao Port team up on alternative bunker fuels

HD HHI and HD KSOE secure ABS AiP for ammonia bunkering vessel design

J-ENG completes land-based testing of hydrogen-fuelled marine engine

Trafigura launches Volare Shipping with six VLCCs, eight newbuilds on order

Bunkering firm Eleven Energy establishes presence in Greece with two trading hires

GTT Marine partners with BetterSea on FuelEU trading, pooling integration

DNV on IMO CCC 12: Revised guidelines for methanol as marine fuel

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”

Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE

Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea

High Court of Singapore issues winding up order against Hengli Petrochemical International

China: Guangzhou completes first bio-methanol STS bunkering operation

Polaris Shipping orders WinGD engines capable of running on methanol, ethanol
-
 Winding up1 week ago
Singapore: Marine fuel testing firm CCIC Singapore faces winding up application
-
 Incident2 weeks ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Technology2 weeks ago
Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE
-
 Ammonia2 weeks ago
Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea
-
 Winding up1 week ago
High Court of Singapore issues winding up order against Hengli Petrochemical International
-
 Alternative Fuels2 weeks ago
China: Guangzhou completes first bio-methanol STS bunkering operation
-
 Engine2 weeks ago
Polaris Shipping orders WinGD engines capable of running on methanol, ethanol
-
 Technology1 week ago
APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists