Connect with us

Analysis

Moore Stephens: Owners facing dilemma on scrubbers

Costas Constantinou applies some ‘mathematical logic’ to help owners make an appropriate decision.

Admin

Published

on

5b63ac87c9756 1533258887

Imagine walking into a car rental company in order to take delivery of a car you booked for your holidays. The employee greets you, takes you to the parking space, shows you two identical cars and lets you know that one car burns normal fuel while the other a special type of fuel that not only is it more expensive but also harder to find. Which car would you take if you had the choice? And wouldn’t you be willing to pay more for the conventional fuel car? If choosing the conventional car appears reasonable, why should charterers behave any differently when they are faced with a similar choice after the implementation of IMO’s regulation for reduced Sulphur emissions in two years’ time?

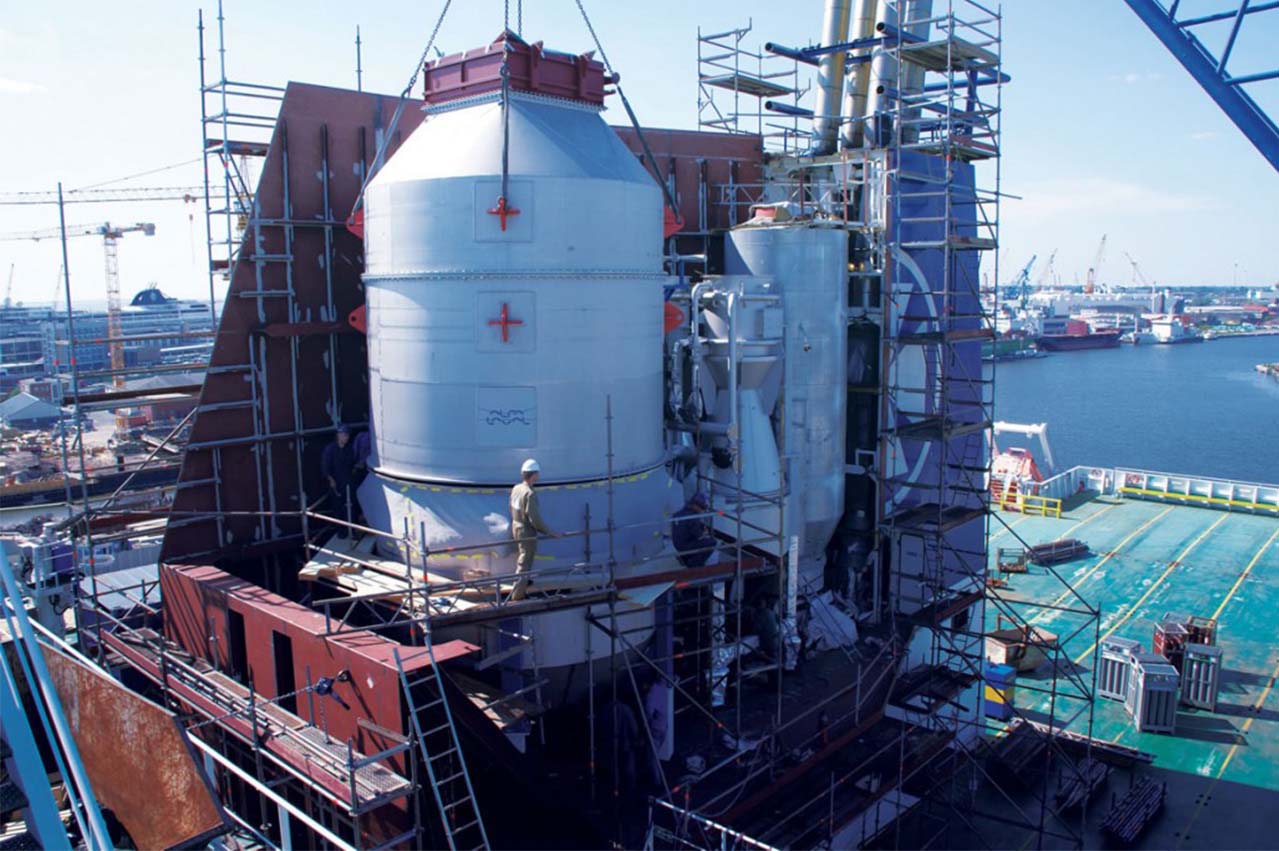
Compliance with this regulation can be achieved in two ways –either by switching to Low Sulphur content fuel or by installing a system of pollution control devices that removes Sulphur from the exhaust fumes and therefore enables the vessel to continue consuming normal Sulphur fuel. The first choice is expensive as the price of this new type of fuel is currently approximately $250 per ton higher than that of conventional fuel and the second needs substantial capital investment and is also disruptive as the vessel will need to go into a shipyard for major retrofit works. With this kind of price differential however, the additional total fuel bill is not going to be an immaterial amount and because fuel costs are borne by Charterers the answer to their question “do I charter a vessel burning expensive and hard to find Low Sulphur Fuel or should I charter one with a Scrubber installed?” seems to be quite obvious.

From the Owners’ perspective however, the decision of how to comply with the regulation is not as straight forward. Firstly, the potential benefit cannot be safely quantified as it depends on the price differential between the two fuel types in the future which is currently unknown and unpredictable. At the moment nobody can say with certainty what will happen to this differential, not just immediately after the implementation of the regulation but in the medium term after that, as this will depend on the future supply and demand curves of the two different fuel types. Due to the nature of the fuel market, there is a long lead time for supply to adjust to demand and also for demand to find a new equilibrium following the decisions that will be made by thousands of owners around the globe. So even if in the long-term supply will match demand, the short and medium term are most probably going to be volatile.

In addition, in contrast with the other environmental regulations Owners had to comply with, the impact of this decision is greater on the profitability, and therefore behavior, of their counterparty, the Charterer, rather their own. It appears that the Owners need to take on the business risk of the decision, for the Charterer to benefit and whereas Charterers have the luxury of waiting to see how the price differential will move and then make their choice, the owners must act a lot sooner as retrofitting a scrubber is not something that can be done quickly, making this difficult choice even harder.

I set out below my personal thoughts on the issue and try to apply some “mathematical logic” to this difficult problem hoping that this process will enlighten this complicated issue and help owners make an appropriate decision.

The Owner has to make one of the following choices:
A) Install a Scrubber or
B) Do nothing,
the financial outcome of which will depend on the future movement of the bunker price differential which may

1) Stay the same or
2) Equalize,
giving us four different outcomes A1, A2, B1 and B2 as follows:

A1-Scrubbers are installed and the differential does not fall
Vessels equipped with a scrubber will be able to consume the cheaper high Sulphur fuel and will have a substantial competitive advantage compared to vessels that will need to buy the more expensive fuel. Charterers would be willing to pay a premium to charter a vessel that will save them money and therefore demand and surely charter rates are bound to increase for these vessels.

A2-Scrubbers are installed and the differential equalizes
The owner will lose as he will be unable to take advantage of his vessels ability to burn low cost fuel. The investment he made will be worthless as he will be in no better position to the owner that chose to do nothing. His losses will be equal to the cost of the investment (capital and financial).

B1-Scrubbers are not installed and the differential does not fall
The owner will have to buy the more expensive low Sulphur fuel making his vessel quite unattractive to charterers who would not prefer to charter a vessel that has to burn expensive fuel. Charterers are likely to push back part of their costs to the owner by way of reduced charter rates or select ships with scrubbers.

B2-Scrubbers are not installed and the differential equalizes
There will not be a change from what we have today and there will be no change for either charterer or owner.

The above outcomes need to be quantified and to do so we need to primarily consider:

  1. Cost for retrofitting the Scrubber system (both direct and indirect)
  2. Additional operating costs to operate the Scrubber system
  3. Estimated annual consumption of fuel irrespective of whether the vessel is chartered on a voyage or time charter basis as illustrated by the car rental example.

Using data obtained from Clarksons (*) for a Capesize vessel (as of March 2017):

  • Cost of Scrubber: $5,000,000
  • Additional Opex : $100,000
  • Annual consumption: 12,900mt
  • Current differential: US$250 per mt.
  • Difference in fuel costs: 3,225,000 p.a.

And assuming, for simplicity purposes, that the benefits fully accrue either to the owner or to the charterer, we get table 1 (Amounts in US$)

Table 1:

    Yr0 Yr1-Yr4 Yr1 Yr2 Yr3 Yr4  
  Price differential Investment Opex p.a. Additional Fuel Cost Total
Install Scrubber Falls to Zero -5,000,000 -100,000 NIL NIL NIL NIL (5,400,000)
Difference remains -5,000,000 -100,000 3,225,000 3,225,000 3,225,000 3,225,000 7,500,000
Do not install Scrubber Falls to Zero NIL NIL NIL NIL NIL NIL NIL
Difference remains NIL NIL (3,225,000) (3,225,000) (3,225,000) (3,225,000) (12,900,000)

And plotting the above to a grid we get table 2.
Table 2:

  Fuel Price differential
Same Falls to zero
Choices A – Install Scrubber 7,500,000 -5,400,000
B – Do nothing -12,900,000 0

where we can see that by making Choice A, the owner could either gain US$7.5million or lose US$5.4million whereas with Choice B he could either lose US$12.9million or gain nothing depending on what will happen to the current price differential.

Just by looking at the numbers we see that the installation of a Scrubber, caps the potential loss to a known amount, avoids the worst-case scenario of trading with an uncompetitive vessel and opens the possibility for substantial gains. Not doing anything on the other hand has a best-case scenario of zero, rules out the possibility of gains and makes the owner vulnerable to substantial losses.

The above looks a lot like the Prisoners Dilemma Game studied in Game Theory and like the game, the choice the owner will make will depend on his individual risk profile and game strategy.

Real life however is not a simple game and in order to make such an important decision the owners need to consider other factors such as:

  1. Technical ability to install scrubber – Not all vessels are suited for the installation of scrubbers as these are physically quite substantial machines. There are many technical issues that need to be resolved.
  2. Time into the future to perform the analysis. A newer vessel has more leeway to recover the cost than an older vessel approaching retirement age.
  3. Individual to the Owner cost of capital to the company in order to discount the time series.
  4. The above example, for simplicity purposes, assumes a 50:50 probability of the movement of the price differential. Best estimates on the probabilities and fuel prices must be ascertained as they materially affect the choice.
  5. The opportunity to make financial profits or avoid making large losses depends on what the rest of the competitors do. On one extreme, if the owner of the example is the only one installing scrubbers and finds his vessels able to consume $250 per ton less than the competition then he will be able to claim a large portion of the savings for his own account. If on the other hand all owners install scrubbers then this saving will probably benefit just the Charterers. Who the “competition” is must be clearly defined and examined.
  6. Timing of the installation. The later this is left and the clearer the option of installing scrubbers becomes, the higher the probability that the shipyards that are able to perform this retrofit will not have the capacity to accommodate more vessels and therefore the cost of the installation may increase.
  7. Geographical areas of operations in order to consider the possibility of non-availability of low Sulphur fuel meaning that bunkering will be for much larger quantities with a negative impact on cash flows and, perhaps more importantly, place serious limits on the readiness of the vessel to capitalize on good chartering opportunities. If the vessel is already trading in ECAs then benefits will accrue before the IMO deadline.

In conclusion, it is very important to note that every shipping company has different operations and strategies and therefore there is no “one size fits all” solution to this problem. Each owner must “play his own game” by estimating and quantifying all parameters, preparing cash flow projections based on those individual to the company parameters, enter them into mathematical decision theory models so that they can commit to a decision earlier than their competition and get into beneficial agreements with Bankers, Shipyards, Charterers and Fuel Suppliers in order to get out of the ‘Low Sulphur Fuel prison trap’ unscathed.

The article above is written by Costas Constantinou, Managing Partner, Moore Stephens Chartered Accountants A.E. (Reproduced with permission). The original version can be viewed here.

Photo credit: EGCSA
Published: 3 August, 2018


Continue Reading

Bunker Fuel

Alkagesta highlights key insights on European choke point pressures in August

Update covers dual supply crisis currently shaping global bunker markets — a stalled Strait of Hormuz peace process and Rhine water levels at a 140-year record low — and the implications for Singapore.
Admin

Published

on

By

Alkagesta

Malta-based global commodity trading house Alkagesta recently shared latest market insight examining the dual supply crisis gripping global energy markets as diplomatic efforts to reopen the Strait of Hormuz stall and Rhine water levels fall to record lows, creating what the company describes as a “state of emergency” for European inland fuel distribution.

In an article published on Alkagesta Market Insights on 11 August, the company’s trading and market intelligence teams outlined how the convergence of two simultaneous logistical crises is tightening prompt fuel availability across Singapore, Northwest Europe, and the Mediterranean:

Strait of Hormuz transits fell to a near-one-month low of 13 ships on August 9 following an attack on an ADNOC-linked tanker, as both the US and Iran demand war reparations before any reopening agreement can be reached. Simultaneously, Rhine water levels at the Kaub chokepoint fell to 16 cm on August 10 — the lowest since records began in 1880 — with forecasts pointing to a further drop to just 4 cm by August 14, effectively halting barge traffic and trapping fuel oil stocks at the ARA hub.

The supply picture across both key hubs has deteriorated sharply. In Singapore, Middle Eastern fuel oil imports nearly tripled week-over-week to 328,878 mt by July 29 — the highest volume since March — providing some relief as onshore commercial heavy distillate stocks rose to a five-week high of 19.58 million barrels by August 5. However, July bunker fuel sales are estimated to have fallen 3.7% month-over-month to 4.44 million mt, with elevated premiums redirecting prompt demand toward alternative ports including Zhoushan and Port Klang.

In Europe, the VLSFO market remains acutely undersupplied as refiners continue to prioritize high-margin diesel over low-sulfur blending components, while the Rhine crisis has forced barges to operate at just 15–20% of normal capacity — with freight rates from Rotterdam to Karlsruhe rising more than 400% in two months.

Alkagesta’s strategic outlook points to a potential total breakdown in Rhine-linked inland distribution by mid-August, a VLSFO Hi-5 spread likely to remain above $200/mt through Q3, and a global crude market that analysts warn requires an additional 2.1 million b/d for 18 months to rebuild depleted inventories.

Note: The full article can be read here.


Photo credit: Alkagesta
Published: 17 August, 2026

Continue Reading

Bunker Fuel

Integr8 Fuels: Why bunker markets could be lower than we thought

Marine fuel prices could prove lower than previously anticipated as easing refinery margins and improving bunker market fundamentals outweigh a still-uncertain crude oil outlook, says Integr8 Fuels.
Admin

Published

on

By

6 5

By Steve Christy, Expert Contributor, Integr8 Fuels

29 July 2026

We have just seen one false dawn, is there another to come? 

Last month, we wrote about how close we were to the expected lows in Brent and Rotterdam bunker prices, but not yet Singapore. Given what has happened since, a month is not only a long time in politics, but also a very long time in the bunker market. 

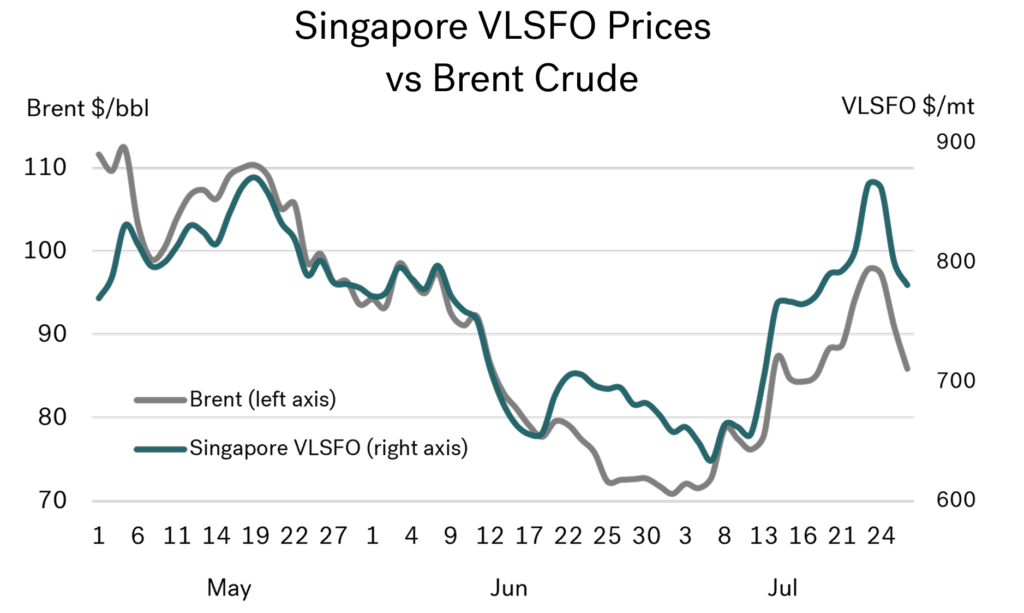
There was a resumption of attacks in the Arabian Gulf region on 13 July, followed by targeted Houthi attacks on Saudi Arabia’s Red Sea oil infrastructure and shipping in the Bab el-Mandeb region, the gateway between the Red Sea and the Gulf of Aden. As a result, Brent futures fell to lows of around $70/bbl in late June and early July before surging to a high of $100/bbl on 23 July. Over the same period, Singapore VLSFO fell to $635/mt before climbing to $865/mt, a swing of $230/mt in just 16 days. 
Jul 2026 Graph 01 1024x613 1

Prices at the start of this week fell sharply after a halt in Arabian Gulf attacks over the weekend, with front month Brent was down to intra-day lows of $84/bbl, and Singapore VLSFO $750/mt.  However, at the time of writing there has been a ‘surprise’ attack by Iran, and retaliatory action by the US, with prices rising again.  It looks like we could be at another false dawn. 

The obvious questions are: will there be a return to peace negotiations, and are we close to the end of the war and free-flowing traffic through the strait of Hormuz (and also the Bab el-Mandeb)? The obvious answer is, we don’t know; there are only a few people that are likely to know the answer to this. All we can do is plan for every eventuality. 

Low stocks, higher bunker prices, and a strong Singapore VLSFO premium: it’s a challenge 

For those of us in the bunker market, the point we made last month about Singapore VLSFO trading at a strong premium to crude still holds, albeit slightly less pronounced. The loss of supplies through the Strait of Hormuz, together with the added uncertainty surrounding Saudi product exports from the Jizan and Rabigh refineries on the Red Sea, has sustained this premium. 

These developments are likely to keep the Singapore VLSFO premium to crude at elevated levels until there is greater confidence that Middle East crude and product supplies are returning to more normal trading patterns. Amid all the price volatility, this Singapore VLSFO premium remains a key indicator to watch. 

Backwardation in Brent futures illustrates market psychology 

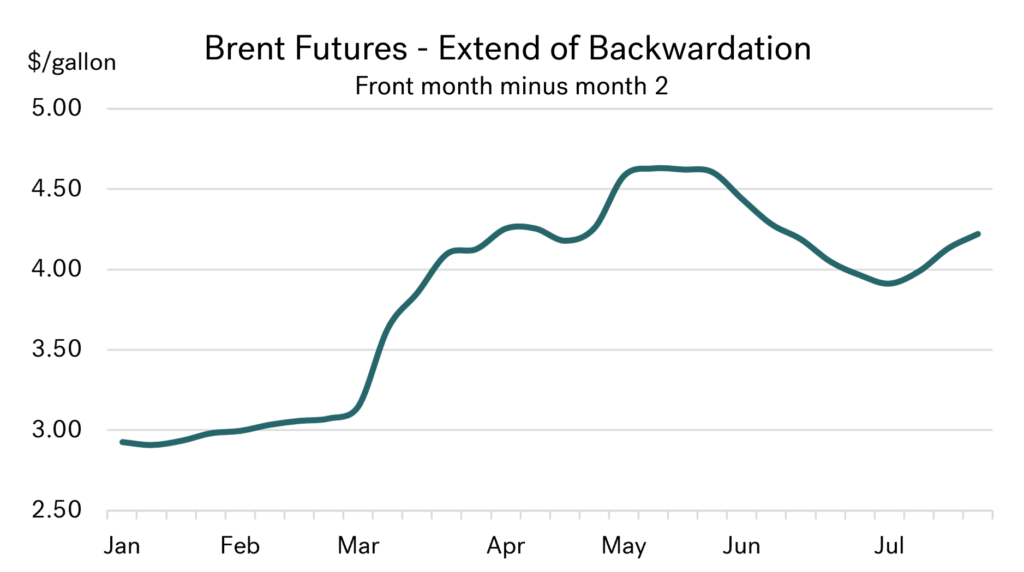
One month ago, backwardation in Brent futures (front month minus second month) had fallen from $7/bbl to virtually nothing, reflecting the market’s belief that an end to the war was little more than a negotiating step away. It wasn’t. The resumption of attacks, coupled with Houthi involvement in the Red Sea, sent prices sharply higher again, with backwardation in the Brent futures market returning to almost $6/bbl. 
Jul 2026 Graph 02 1024x572 1

The halt in attacks over the past weekend has taken steam out of the market, with prices and backwardation falling sharply. Where we go from here depends if there is again a belief peace is on the horizon, or if this is another false dawn. The past month highlights how impossible it is to predict an ending to the war, and how fragile any expectations of peace can be. 

We cannot ignore the price, but still must look to the future

It is impossible to write a report and not highlight the turmoil of the current market and what is happening. However, we still must look beyond this, to see where we could end up. 

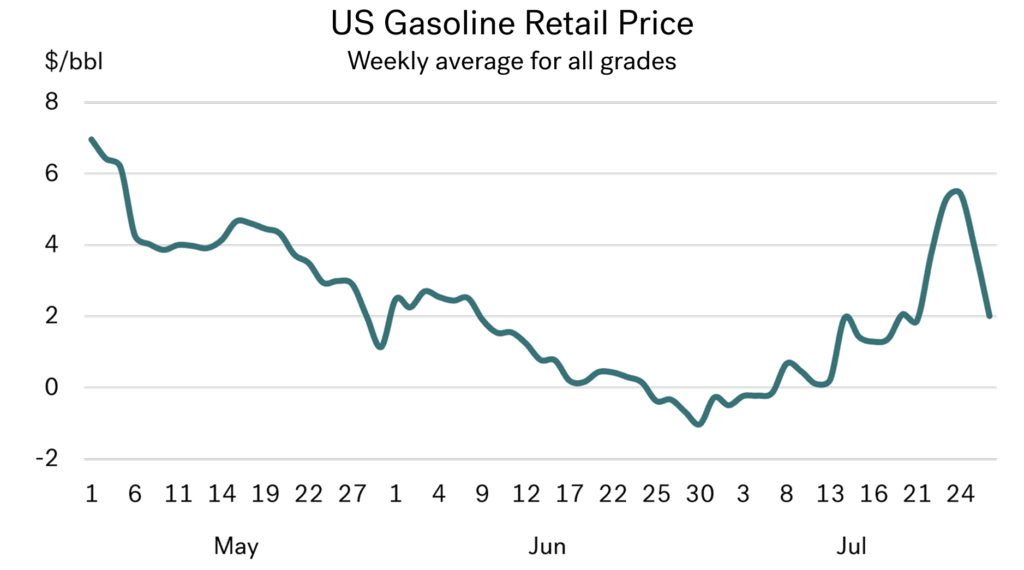
In an earlier report, we suggested the run-up to the US mid-term elections in November may be a backstop to the war. However, even this is not guaranteed. There are many dynamic elements to the economy and voter intentions, but one feature that will always crop up in the US is the gasoline price. This has risen from $3/gallon before the war to over $4/gallon for the past four months. 
Jul 2026 Graph 03 1024x570 1

If it comes to it, will Republican voters want to see a resolution to the war and a return to $3 gasoline prices ahead of the elections? 

We have a change of heart on how low bunker prices can go

We don’t know exact timings, but in any planning, we must look at what happens when the war does finally end and prices fall, whenever that may be. In past reports we have highlighted the view that Brent crude prices are unlikely to fall back to pre-war levels in the $60s, and Singapore VLSFO unlikely to go back in to the $400s. This may be the point at which these views change.

Previous thinking was based on a relatively short war, where there would be a large loss of oil supply and a massive stock-draw. In this case, tighter stock levels would be sufficient to keep prices higher than their pre-war levels once we returned to ‘normality’. This would mean Brent futures in the $70s (and not in the $60s), and Singapore VLSFO in the $500s, and not the $400s.

A number of mainstream analysts also held this view, although there were some that were lower and some higher.

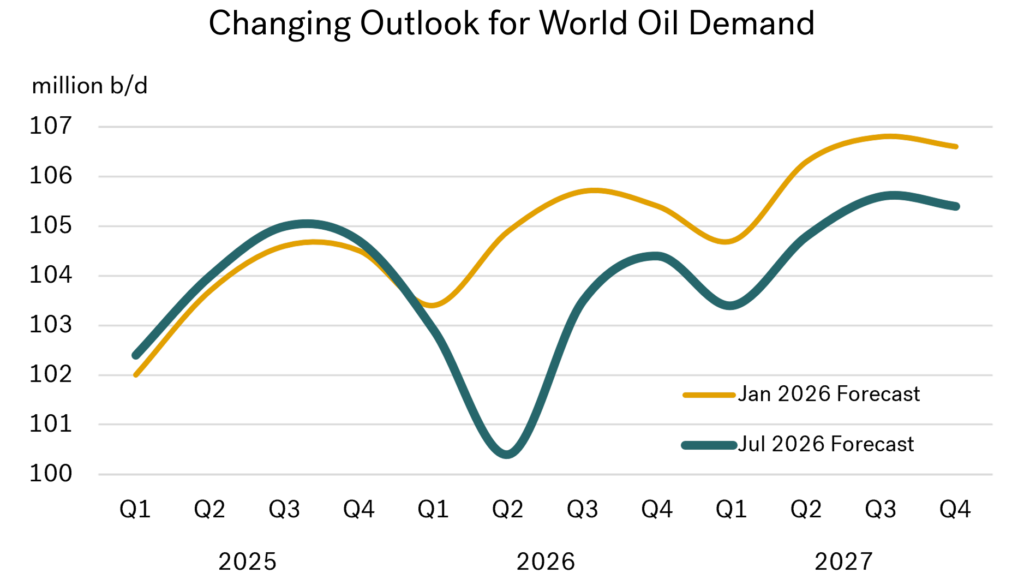
Given the war has already gone on for much longer than almost everyone expected, this thinking must change. Yes, global stocks have been drawn down at a rapid rate, but this is slowing. Higher pricing and inflationary blows have had a major impact on global oil demand, with current indications that total oil demand in the second quarter of this year was some 4 million b/d lower than year earlier levels.

The graph below shows this sharp drop in demand and even if the war comes to an end relatively soon, and demand gets back towards some normality, a structural loss of more than 1 million b/d in global oil demand is still expected to have taken place because of the extended period of conflict.

If the war goes on for even longer, structural losses in global oil demand are likely to be even greater.
Jul 2026 Graph 04 1024x579 1

Source: US EIA

It’s a hard road, but we can get there

This means that once the war does end, market psychology will be looking at a rapid increase in oil supplies going into a global market which is much lower in demand.  This opens the way for prices to easily return to their pre-war levels of Brent in the $60s and Singapore VLSFO in the $400s. 

Now we just need those at the centre of negotiations to get us there.


Photo credit and source: Integr8 Fuels
Published: 30 July, 2026

Continue Reading

Bunker Fuel Quality

FOBAS report warns of growing operational risks from ISO-compliant bunker fuels

LR’s latest FOBAS Fuel Quality Report reveals that the biggest fuel quality risks are no longer confined to off-specification fuels, with some compliant fuels creating operational challenges.
Admin

Published

on

By

New FOBAS report warns growing operational risks from ISO-compliant bunker fuels

Classification society Lloyd’s Register (LR) on Tuesday (14 July) warned that ship operators are facing a growing risk from fuels that appear compliant under routine ISO 8217 testing but still present operational risks once onboard.

According to LR’s latest Fuel Oil Bunker Analysis and Advisory Service (FOBAS) Fuel Quality Report, covering the first half of 2026, off-specification fuels remain a persistent challenge. 

However, some of the most disruptive cases now involve fuels that pass routine compliance testing but show poor stability or compatibility, or contain non-conventional blend components that are only identified through more detailed investigative analysis.

Several incidents investigated highlighted this trend. In March and April, a number of vessels reported operational difficulties after bunkering fuel in a major bunkering hub. Further forensic analysis found that many of the fuels contained elevated concentrations of Estonian shale oil, in some cases estimated to be around 10-15%.

While shale oil is recognised within ISO 8217 as an acceptable blend component, FOBAS investigations found that higher concentrations can be associated with fuel instability and operational issues affecting filters, separators and fuel pumps.

The report also shows that fuel quality variability remains stubbornly high. Off-specification cases remained elevated throughout the first six months of 2026, suggesting that quality issues are no longer isolated events but a more persistent feature of today’s marine fuel supply chain.

The most common recurring issues included sulphur exceedances, excessive water content, sediment and stability problems, elevated catalytic fines, sodium contamination and low flash point distillate fuels.

At the same time, biofuels (especially FAME blends) are continuing to grow without being a primary source of quality issues. Where issues occurred in blended fuels, they were generally associated with the conventional VLSFO component rather than the FAME fraction.

The report concluded that operators will need to adopt a more proactive approach to fuel management as marine fuels become more diverse and fuel quality risks become harder to identify through routine compliance testing alone.

Greater emphasis on fuel stability, compatibility and understanding fuel composition will be critical to reducing operational disruption and maintaining vessel performance.

Murray Kirkwood, Fuel Specialist Consultant, Lloyd’s Register, said: “The findings from our latest report show that fuel quality risk is evolving. The challenge is no longer simply identifying fuels that fail specification. Increasingly, operators are encountering fuels that meet the required limits but still create operational difficulties once they are stored, handled and used onboard.

“As fuel blending becomes more complex, the distinction that matters is increasingly not between on-spec and off-spec fuel, but between fuels that are operationally resilient and fuels that are operationally fragile. Understanding that difference is becoming essential for shipowners and operators.”

The latest findings reinforced FOBAS’ long-standing view that effective fuel management increasingly depends on understanding fuel behaviour rather than relying solely on pass-or-fail specification testing.

By combining routine fuel quality monitoring with forensic investigation of operational incidents, FOBAS provides shipowners with a clearer understanding of emerging fuel quality risks as the industry continues its transition to a more diverse and complex fuel landscape.

Note: The FOBAS Fuel Insight: Fuel Quality Report H1 2026 is available at FOBAS Fuel Insight: Fuel quality reports | LR


Photo credit: Lloyd’s Register
Published: 15 July, 2026

Continue Reading

Trending