Connect with us

Bunker Fuel

ENGINE: Global Bunker Fuel Availability Outlook (31 December 2025)

HSFO supply remains tight in Singapore; bunker availability tight in Gibraltar; VLSFO and LSMGO supply improves in Santos.

Admin

Published

on

RESIZED ENGINE GLOBAL

The following article regarding global bunker fuel availability has been provided by online marine fuel procurement platform ENGINE for post on Singapore bunkering publication Manifold Times:

  • HSFO supply remains tight in Singapore
  • Bunker availability tight in Gibraltar
  • VLSFO and LSMGO supply improves in Santos

East of Suez

Despite sluggish bunker demand, suppliers in Singapore are recommending lead times of about 4–6 days for VLSFO. LSMGO availability remains comfortable, with shorter lead times of around three days advised, while HSFO supply is tight and requires much longer advance notice of 9–10 days.

In Port Klang, VLSFO and LSMGO remain readily available, especially for smaller prompt stems, while HSFO availability continues to be limited.

In Zhoushan, suppliers are advising lead times of 4–7 days for small parcels across all grades. Larger stems above 1,500 mt need slightly longer windows of 6–10 days. By comparison, last week VLSFO and LSMGO required 4–6 days, while HSFO needed 5–7 days.

Across Taiwan, suppliers in Keelung and Hualien can typically deliver VLSFO and LSMGO within two days, unchanged from last week. Taichung and Kaohsiung require slightly longer lead times of around three days. Notably, 1 January 2026 is a holiday in Taiwan, meaning no bunker orders can be placed, though deliveries will proceed as usual, according to state-owned CPC Corporation.

Bunker availability is good across all grades in South Korea, where suppliers are recommending lead times of 4–6 days. However, winter weather could cause disruptions: Busan, Ulsan and Daesan may face disruptions from 31 December to 5 January, while bunker operations at Yeosu could be affected from 1–5 January.

In Japan, availability of all grades is extremely tight because of low inventories and widespread barge congestion. Affected ports include Tokyo, Chiba, Kawasaki, Yokohama, Osaka, Kobe, Nagoya, Yokkaichi, Mizushima and Tokuyama, a trader said.

For deliveries in early January, suppliers are expected to offer stems in Tokyo Bay around 9–10 January, while congestion at other ports is likely to persist until mid-January.

Rough weather is forecast in Colombo from 4–5 January, which could disrupt bunker deliveries.

In Fujairah, prompt bunker supply remains tight across all grades, with several suppliers facing constrained delivery schedules. Similar conditions persist in the nearby Khor Fakkan port. Adverse weather conditions could further impact operations at both ports.

Bunker supply in Oman’s ports – Sohar, Salalah, Muscat and Duqm – remains stable, with suppliers consistently offering prompt LSMGO deliveries. However, adverse weather is forecast in Sohar and Salalah on Wednesday, which could affect operations.

Europe and Africa

Fuel availability in the ARA hub remains tight for prompt deliveries, with buyers advised to enquire around 5-7 days in advance for all fuel grades to secure competitive offers from a wider range of suppliers, a trader told ENGINE.

From 1 January 2026, suppliers in Dutch ports will be covered under the country’s new domestic regulations that implement EU’s RED III rules. This is expected to increase bunker costs as suppliers pass on related compliance expenses.

Separately, the ports of Rotterdam and Antwerp will require all bunker deliveries to be made by certified mass flow meter (MFM)-equipped barges from 1 January 2026.

Prompt bunker deliveries are also tight in the Gibraltar Strait, where a minimum lead time of around one week is recommended, the trader added.

Congestion in Gibraltar has eased slightly, with around nine vessels waiting for bunkers at the port on Wednesday morning, down from 15 vessels on Tuesday. Suppliers are working to clear the backlog, but most are running 10-48 hours behind schedule, port agent MH Bland said.

Around 35 vessels are expected to call at Gibraltar for bunkers between 31 December- 5 January, according to shipping agent A Mateos & Sons.

Off Malta, some suppliers can deliver LSMGO at the earliest by 5–6 January, while VLSFO supply remains tight and only one supplier is currently offering HSFO, a trader told ENGINE. ULSFO supply remains normal, the trader added.

Suppliers in Durban are recommending lead times of seven days for HSFO deliveries, while VLSFO can be supplied with 2-4 days, a trader said. 

Americas

Bunker fuel demand in Houston remains steady even as adverse weather continues to impact operations in the US Gulf Coast. Lead times for all three grades are currently between 3–7 days.

With the region now in its fog season, delays and intermittent channel closures caused by reduced visibility are expected in the months ahead until March.

From 1 January, a safety guideline change will permit nighttime transits for containerships, LPG carriers and widebody tankers at the port, a ship agent said.

A gale warning is currently in effect in New York, with high wind gusts occasionally reaching up to 40 knots. Demand for HSFO and VLSFO is normal in the port, with recommended lead times between 5-7 days this week. For LSMGO deliveries, most suppliers are recommending lead times of roughly three days.

In Brazil, VLSFO and LSMGO availability remains normal in Santos, with lead times of around 5–8 days.

Across Rio de Janeiro both grades are tight and need over a week of lead time for delivery.

VLSFO and LSMGO grades are available in Rio Grande, Belém and Vila do Conde, with deliveries possible with recommended lead times of 4–5 days.

At OPL Sepetiba, VLSFO and LSMGO supplies have been replenished, and the earliest delivery date is 7 January, according to sources.

In Salvador, the earliest supply for both grades is between 2–4 January.

In Paranaguá, VLSFO can be supplied within 4–5 days, while LSMGO remains unavailable.

Meanwhile, Itaqui has good availability of both VLSFO and LSMGO, with deliveries possible from 6-7 January.

In Zona Común, weather conditions continue to support bunker operations. But over the weekend, deliveries could be suspended by high wind gusts at the anchorage.

VLSFO and LSMGO deliveries require lead times of around 5–8 days in Zona Común.

By Tuhin Roy, Nachiket Tekawade and Gautamee Hazarika


Photo credit and source: ENGINE
Published: 2 January, 2026

Continue Reading

Bunker Fuel

Seascale Energy names Gaetan Perret co-CEO as Olivier Josse prepares to retire

Gaetan Perret, Head of Marine Fuel Procurement, West, will succeed him as Vice President, Marine Fuels at Cargill and as co-CEO of Seascale Energy, alongside Peter Grünwaldt, effective on 14 December.
Admin

Published

on

By

Seascale Energy names Gaetan Perret co-CEO as Olivier Josse prepares to retire

Seascale Energy, the marine fuel procurement joint venture between Cargill’s Ocean Transportation business and Hafnia, on Monday (21 September) announced that co-CEO Olivier Josse (OJ) will retire from Cargill on 14 December 2026 after 36 years. 

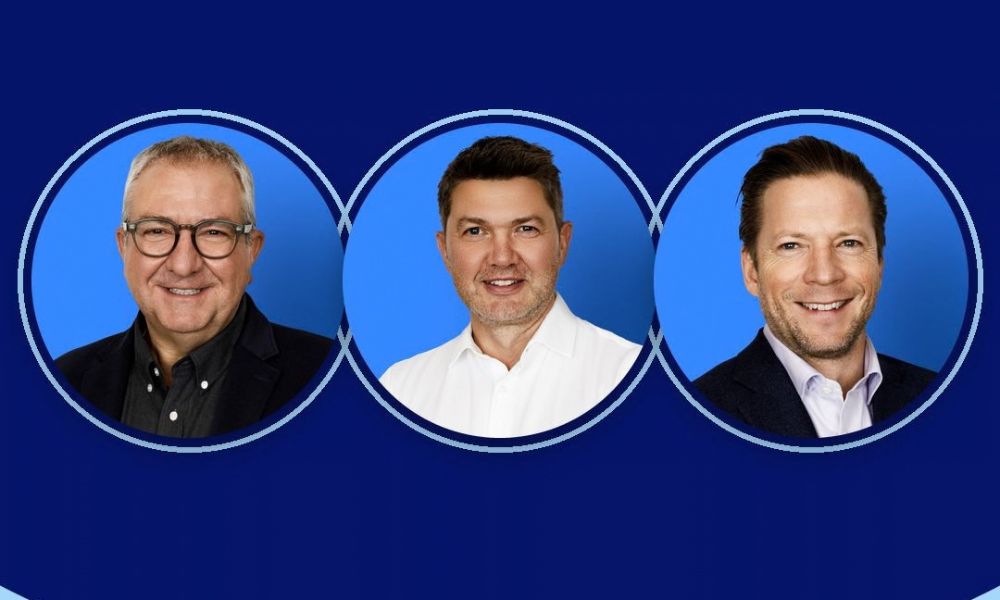
Gaetan Perret, Head of Marine Fuel Procurement, West, will succeed him as Vice President, Marine Fuels at Cargill and as co-CEO of Seascale Energy, alongside Peter Grünwaldt, effective the same date. 

Olivier Josse joined Cargill in 1990 and has held leadership roles across the company’s trading and chartering activities, joining Ocean Transportation in 2006 and serving on its leadership team since 2010. He led the establishment of Seascale Energy in 2025 and has served as co-CEO since the joint venture began operations. 

 “OJ has spent 36 years building businesses and developing people at Cargill, most recently through Seascale Energy,” said Jan Dieleman, President of Cargill’s Ocean Transportation business. “He leaves the platform in a strong position and with a successor who helped build it. Gaetan knows this market, knows our customers and knows what Seascale was set up to do.” 

“Seascale was built to give the market scale and transparency, and that remains the job,” said Olivier Josse.

“After 36 years, the timing is right for me personally. Deciding to retire says everything about the strength of the platform, the direction of the business, and the wonderful people in it. The volumes, the membership and the pipeline all point in the same positive direction – and as a co-founder, I would not be stepping back at this time if I thought otherwise. It is now time for my close colleague Gaetan Perret to take on the baton, and I congratulate him, and wish both him and Peter all the best in taking Seascale onto its next steps. It has been a fantastic experience working with both and the wider team.” 

“OJ and I started this venture together with an amazing team, and I am grateful for his partnership and friendship in the last years, where we have gone from peers to competitors to now colleagues and friends. On behalf of the full team at Seascale, we wish OJ all the best and will miss his contributions following his retirement,” said Peter Grünwaldt, co-CEO of Seascale Energy.

“Customers and suppliers will see continuity in the same team, same model, same commercial terms, with a handover that runs through to December. In this, I would also like to congratulate Gaetan on his upcoming appointment and look forward to working more closely with him as my counterpart.” 

Seascale Energy was launched in May 2025 by Cargill’s Pure Marine Fuels and the Hafnia Bunker Alliance. It procures approximately 8 million metric tonnes (mt) of marine fuel annually to more than 50 third-party members, operating from Singapore, Copenhagen, Geneva and Houston.  

The joint venture remains equally owned by Cargill and Hafnia, and its governance, dual-CEO structure and board composition are unchanged. 

On taking on the new role in December 2026, Gaetan Perret brings more than two decades of experience across shipping, trading and bunkering. He has been closely involved in building Cargill’s Pure Marine Fuels business and in the establishment of Seascale Energy and currently leads marine fuels purchasing in the West.


Photo credit: Seascale Energy
Published: 25 September, 2026

Continue Reading

Decarbonisation

DNV: New research shows how regulation could reshape shipping

DNV summarizes findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness.
Admin

Published

on

By

DNV flag

Classification society DNV on Thursday (24 September) released a new article summarizing findings of its latest Maritime Forecast to 2050, exploring how future scenarios could affect marine fuel demand, technology uptake, fleet investments, and competitiveness: 

Shipping’s energy transition has entered a new phase. The technology options are increasingly well understood. LNG, methanol, biofuels, wind-assisted propulsion, and emerging ammonia solutions are no longer concepts but commercial realities. Yet despite this progress, shipowners face a more difficult challenge than ever: making investment decisions amid unprecedented regulatory uncertainty.

The 2026 edition of DNV’s Maritime Forecast to 2050 argues that uncertainty itself is now becoming one of the most important drivers of fleet strategy. 

“Decisions taken today on vessel design, retrofits, and fuel capability will determine competitiveness for decades, while the outcome of ongoing regulatory negotiations could significantly reshape the economics of shipping’s energy transition,” says Øyvind Sekkesæter, Senior Consultant at DNV and lead author of this year’s report. “Maritime Forecast to 2050 aims to assist that decision-making with our latest core insights and case study examples.”

Four regulatory scenarios could shape shipping very differently

This year’s Maritime Forecast takes a scenario-based approach, presenting four possible regulatory futures for shipping. These range from the full adoption of IMO’s initially approved Net-Zero Framework (NZF) to its rejection and prolonged political gridlock, while also exploring several intermediate outcomes, including a delayed or revised NZF and scenarios where regional regulations play a more prominent role in driving decarbonization. Rather than predicting which outcome is most likely, the scenarios illustrate how different regulatory futures could affect fuel demand, energy-efficiency uptake, investment signals, and fleet competitiveness.
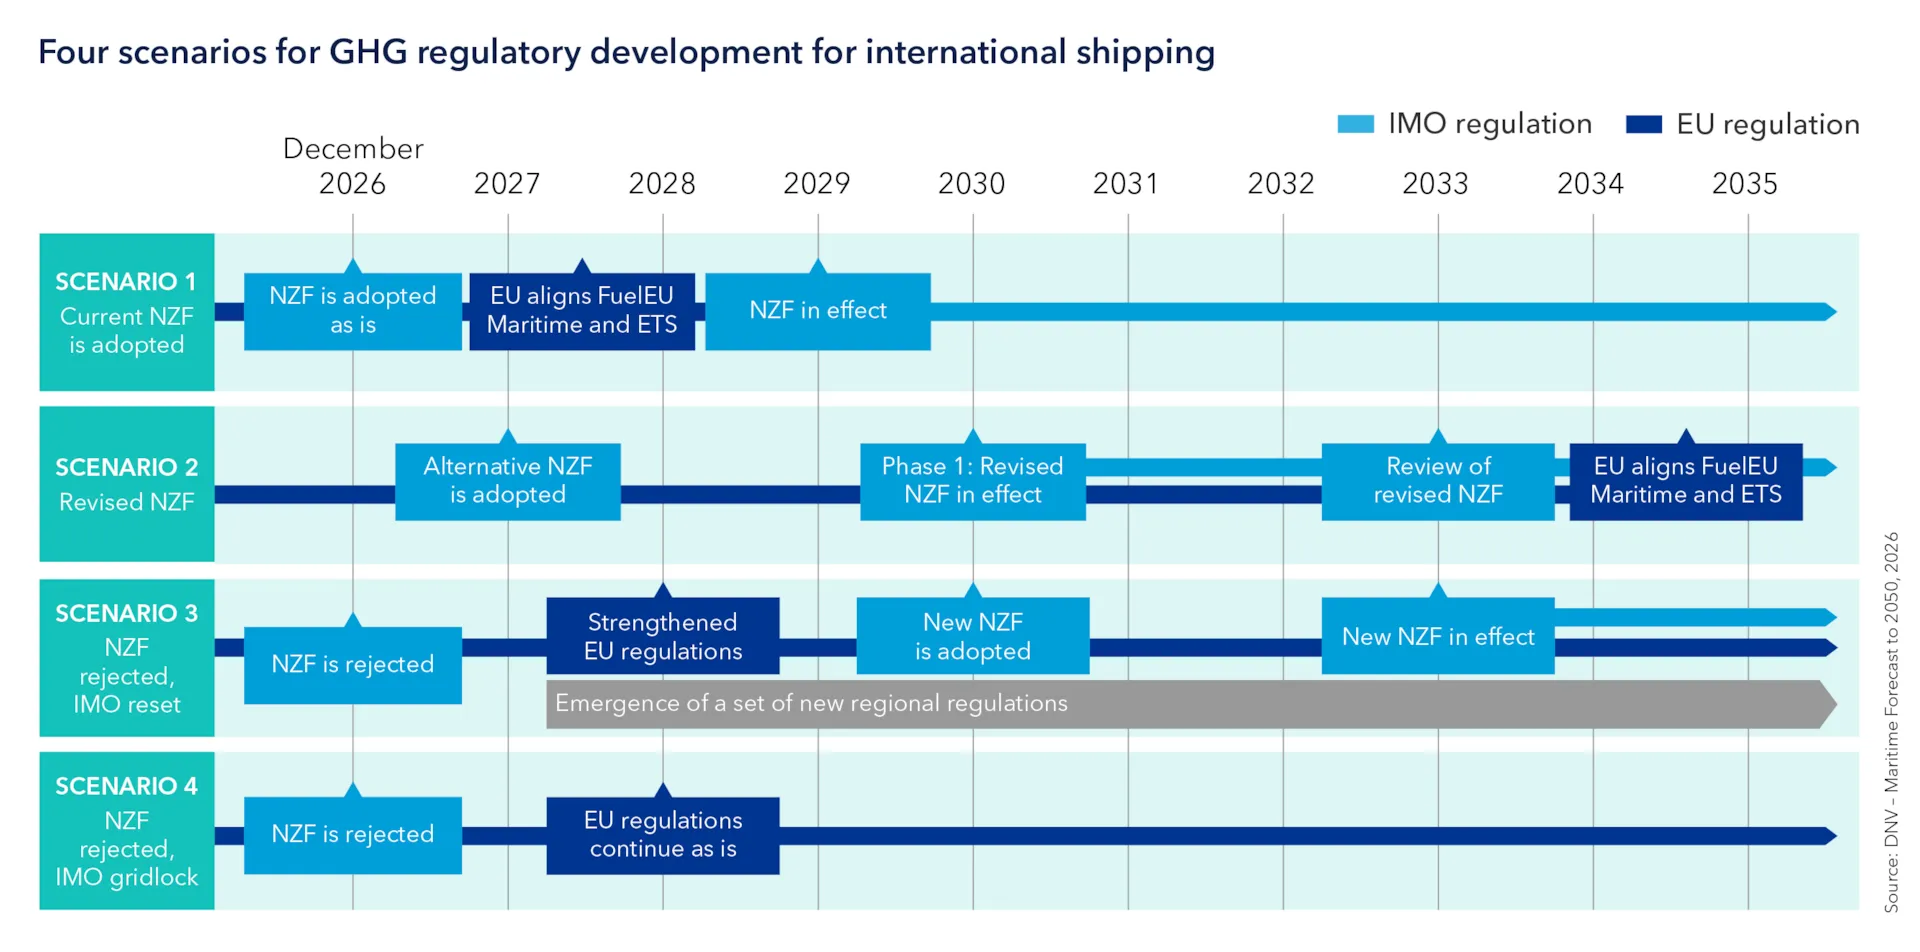
t1 ind 673 scenarios

Stronger global regulation accelerates demand for low-GHG fuels and increases the attractiveness of energy-efficiency measures, while the absence of such regulation slows market development. The result is a transition whose pace may vary significantly depending on future policy decisions.

“For shipowners, this means the challenge is no longer identifying a single fuel pathway that fits the operational profile of their fleet. Instead, it is preparing fleets that remain competitive across multiple possible futures,” Sekkesæter concludes.

Tapping the fleet’s efficiency potential

Fully realizing the fleet’s energy-saving potential requires improvements not only to newbuilds but also to existing ships through retrofits.

Installing energy-saving devices during scheduled dry-docking can be a highly cost-effective decarbonization strategy, as illustrated by the Maritime Forecast’s case study of a hypothetical 15-year-old 5,000 TEU containership (built in 2013).

This envisages USD 2.35 million being invested to retrofit the ship with hydrodynamic enhancements including a bow retrofit, propeller upgrade, and a propeller boss cap fin.

The vessel can achieve estimated fuel savings of around 16% under the modelling assumptions. Evaluating the investment under three price scenarios for low sulphur heavy fuel oil (LSHFO) results in payback periods from 1.4 years to 4.2 years.

Note: The full Maritime Impact article by DNV can be found here. 


Photo credit: DNV
Published: 25 September, 2026

Continue Reading

Newbuilding

Stena Line orders two new hybrid ferries for Sweden – Denmark route

Vessels will feature the latest hybrid propulsion technology, allowing them to operate on both conventional fuel and electricity and will be prepared for conversion to 100% electric operation.
Admin

Published

on

By

Stena Line orders two new hybrid ferries for Sweden – Denmark route

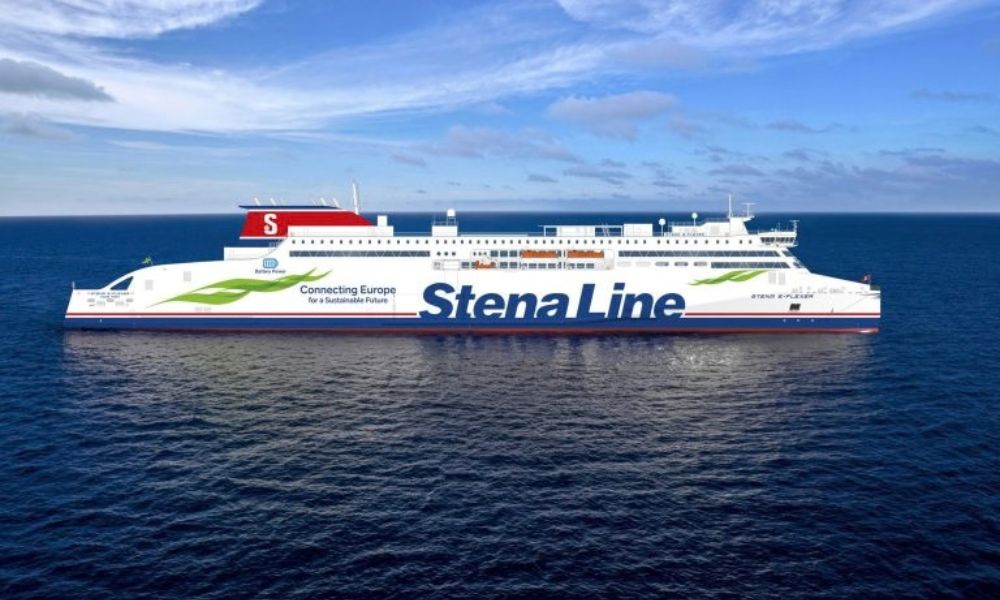
Stena Line on Wednesday (23 September) said it is renewing its fleet and has placed an order for two new hybrid E-Flexer ferries, scheduled to enter service in 2030.

Both vessels will be built at the China Merchants Industry Weihai Shipyard in China, which has so far built 15 E-Flexers.

The vessels will feature the latest hybrid propulsion technology, allowing them to operate on both conventional fuel and electricity. 

They will also be prepared for conversion to 100% electric operation once the necessary charging infrastructure is in place.

The two RoPax ferries will have capacity for 1,500 passengers and 2,750 lane metres of freight. Designed as day ferries, they are intended to operate on the Gothenburg–Frederikshavn route.

The two new vessels will become the sixth and seventh E-Flexers in Stena Line’s fleet. The first entered service in 2019, and today three E-Flexers operate on the Irish Sea and two between Sweden and Poland.

“This is a historic investment for Stena Line, giving us the opportunity to take further steps towards the sustainable modernisation of our fleet,” said Niclas Mårtensson, CEO of Stena Line.

“The two new ferries will strengthen our customer offering by taking the travel experience to a new level. At the same time, we are future-proofing our own CO₂ reduction targets while preparing for the stricter environmental requirements ahead.”

The vessels currently operating on Stena Line’s Gothenburg–Frederikshavn route, Stena Danica and Stena Jutlandica, have served the route for many years. Stena Danica entered service on the route as early as 1984, while Stena Jutlandica followed in 1996.


Photo credit: Stena Line
Published: 25 September, 2026

Continue Reading

Trending