Connect with us

Bunker Fuel Availability

ENGINE: East of Suez Fuel Availability Outlook (28 July 2026)

VLSFO availability tight in Zhoushan; availability tight across all grades in Fujairah; bunker demand picks up in Jeddah.

Admin

Published

on

RESIZED ENGINE East of Suez

The following article regarding regional bunker fuel availability outlook for the East of Suez region has been provided by online marine fuels procurement platform ENGINE for publication on Singapore bunkering publication Manifold Times:

  • VLSFO availability tight in Zhoushan
  • Availability tight across all grades in Fujairah
  • Bunker demand picks up in Jeddah

Singapore and Malaysia

VLSFO availability in Singapore has tightened further, with suppliers now recommending lead times of 16-20 days, compared with 14-19 days last week. Supply remains under pressure as the port’s fuel oil inventories have yet to recover to pre-conflict levels, while cargo inflows continue to be affected by renewed US-Iran hostilities that have disrupted traffic through the Strait of Hormuz.

HSFO supply has also tightened, with recommended lead times extending to 12-15 days from 9-13 days a week earlier. Meanwhile, LSMGO availability has improved, with lead times easing to 5-8 days from 9-11 days last week.

Fuel oil inventories fell below 18 million bbls in June, down from more than 23 million bbls in March. Stocks have also remained below the 20 million-bbl mark so far this month, latest data from Enterprise Singapore shows.

In Malaysia’s Port Klang, bunker fuel supply remains constrained. Prompt VLSFO availability is tight, LSMGO supply is limited, and HSFO continues to face supply pressure.

East Asia

VLSFO availability in Zhoushan remains tight despite muted demand, with suppliers recommending lead times of about nine days, down from roughly 12 days previously. A local source attributed the extended lead times to reduced refinery output.

Recommended lead times for both LSMGO and HSFO have remained largely unchanged at around seven days.

Bunker fuel availability across northern China continues to vary by port. Suppliers in Dalian and Qingdao have sufficient VLSFO and LSMGO stocks, although HSFO remains tight in Qingdao. In Tianjin, availability of all three major bunker grades is constrained, while Shanghai continues to face tight VLSFO and HSFO supply. LSMGO availability in Shanghai remains comparatively stable.

Supply conditions also remain tight across several southern Chinese ports. VLSFO and LSMGO are both under pressure in Fuzhou. Xiamen has adequate VLSFO availability, but prompt LSMGO supply is more limited. In Yangpu and Guangzhou, both grades continue to face supply constraints.

Hong Kong’s bunker market remains stable, with suppliers continuing to recommend lead times of around seven days for all major fuel grades, largely unchanged from recent weeks.

In Taiwan, VLSFO and LSMGO deliveries can be arranged within about two days in Hualien and Taichung, while Kaohsiung requires lead times of around three days. In Keelung, however, lead times for both grades have extended to 4-5 days from about three days previously due to ongoing barge constraints.

Bunker fuel availability has improved across South Korea’s southern ports, including Busan, Ulsan, Masan, Onsan, Yeosu and Kwangyang. Recommended lead times for VLSFO, LSMGO and HSFO have all shortened to 6-8 days, compared with 9-16 days last week, reflecting an easing in supply conditions.

A similar trend is evident across South Korea’s western ports—including Incheon, Daesan, Dangjin, Pyeongtaek and Taean—where lead times for all three fuel grades have also narrowed to 6-8 days, from 9-16 days a week earlier.

Meanwhile, supply remains tight at Japan’s major ports, including Tokyo, Chiba, Kawasaki, Kashima, Nagoya, Yokkaichi, Osaka, Kobe, Mizushima and Oita. VLSFO and LSMGO continue to be available through only a limited number of suppliers, while HSFO is comparatively easier to source, with recommended lead times of around 7-10 days.

In contrast, Indonesia continues to enjoy healthy bunker fuel availability. Suppliers in Jakarta, Surabaya, Balikpapan and Cigading are generally recommending lead times of just 2-3 days for VLSFO, indicating ample supply.

Oceania

VLSFO availability remains steady across Western Australia, with suppliers in Kwinana and Fremantle continuing to recommend lead times of about seven days. Both ports rely on a single supplier, with all bunker deliveries conducted by barge.

Supply conditions are more varied along Australia’s east coast. In Port Kembla, VLSFO can be delivered by truck or pipeline, while suppliers in Sydney have sufficient stocks of both VLSFO and LSMGO. HSFO availability is comparatively tighter in Sydney, where suppliers generally advise booking around seven days in advance.

In Queensland, VLSFO and LSMGO remain readily available in Brisbane and Gladstone, with lead times holding at approximately seven days.

Further south, Melbourne and Geelong continue to have healthy VLSFO inventories. However, both ports depend on a single bunker barge for deliveries, keeping recommended lead times at around one week. HSFO availability has tightened further in both Melbourne and Brisbane.

Separately, one supplier is offering all major bunker grades in Brisbane, Sydney and Melbourne with lead times of roughly five days. In Western Australia, pipeline-based bunker deliveries to Dampier Cargo Wharf (DCW) have been suspended until around the end of September due to repair works. Limited truck deliveries remain available, depending on vessel size. During the outage, a supplier has designated the Toll Supply Base (TSB) in Dampier as the preferred alternative for bunker operations, a source said.

Across the Tasman, bunker fuel availability in New Zealand remains largely unchanged. VLSFO supply is readily available in Tauranga and Auckland, where suppliers continue to recommend lead times of around four days. At Marsden Point, both VLSFO and LSMGO can be supplied directly to vessels via pipeline.

Weather remains the primary operational challenge in New Zealand. Bunker deliveries are especially vulnerable to disruption in Wellington and ports across the South Island, where adverse weather conditions can periodically delay supply operations.

South Asia

Some suppliers in Mumbai continue to recommend lead times of 4–5 days for both VLSFO and LSMGO, although deliveries remain subject to weather conditions. In contrast, VLSFO availability is extremely tight at Haldia, Visakhapatnam, Kakinada, Gangavaram and Krishnapatnam, a source said.

Monsoon conditions are expected to disrupt bunker operations at several Indian ports over the coming days, with weather-related delays likely to affect bunker deliveries. Operations at Kandla and Sikka are forecast to face disruptions between 28 July and 1 August, while rough seas could hinder bunkering in Mumbai, Cochin and Visakhapatnam over the same period.

In Sri Lanka, adverse weather is also expected to intermittently disrupt bunker operations in Colombo and Trincomalee between 28 July and 1 August, with potential delays to bunker deliveries.

Middle East

Renewed hostilities between the US and Iran in the Strait of Hormuz have tightened bunker fuel availability in Fujairah. Supplies of VLSFO and LSMGO have become more constrained compared to last week, when prompt deliveries were still possible. Only a handful of suppliers are currently able to offer LSMGO, while HSFO remains scarce and is largely available only on a firm enquiry basis.

Conditions are more favourable at the neighbouring UAE bunker hub of Khor Fakkan, where VLSFO and HSFO availability remains good. However, bunker demand has eased in both Fujairah and Khor Fakkan amid the renewed regional conflict, according to a Middle East-based source.

In Saudi Arabia’s Jeddah, VLSFO and LSMGO availability continues to hold steady, despite an uptick in demand.

Supply constraints persist in Qatar’s Ras Laffan, where both VLSFO and LSMGO remain in limited supply.

At Egypt’s Port Suez, inventories of all three conventional bunker grades remain critically tight.

Further south, availability of all major bunker fuel grades also continues to be limited in Djibouti.

By Tuhin Roy


Photo credit and source: ENGINE
Published: 29 July, 2026

Continue Reading

Bunker Fuel

Baltic Exchange: Bunker Report (17 September 2026)

Bunker report panellists include Island Oil Limited, Cockett Marine Oil Pte, Monjasa A/S, KPI OceanConnect, NSI Marine and Transparensea Fuels.
Admin

Published

on

By

Baltic Exchange logo

The following bunker report has been provided by freight market information provider Baltic Exchange for post on Singapore bunkering publication Manifold Times:
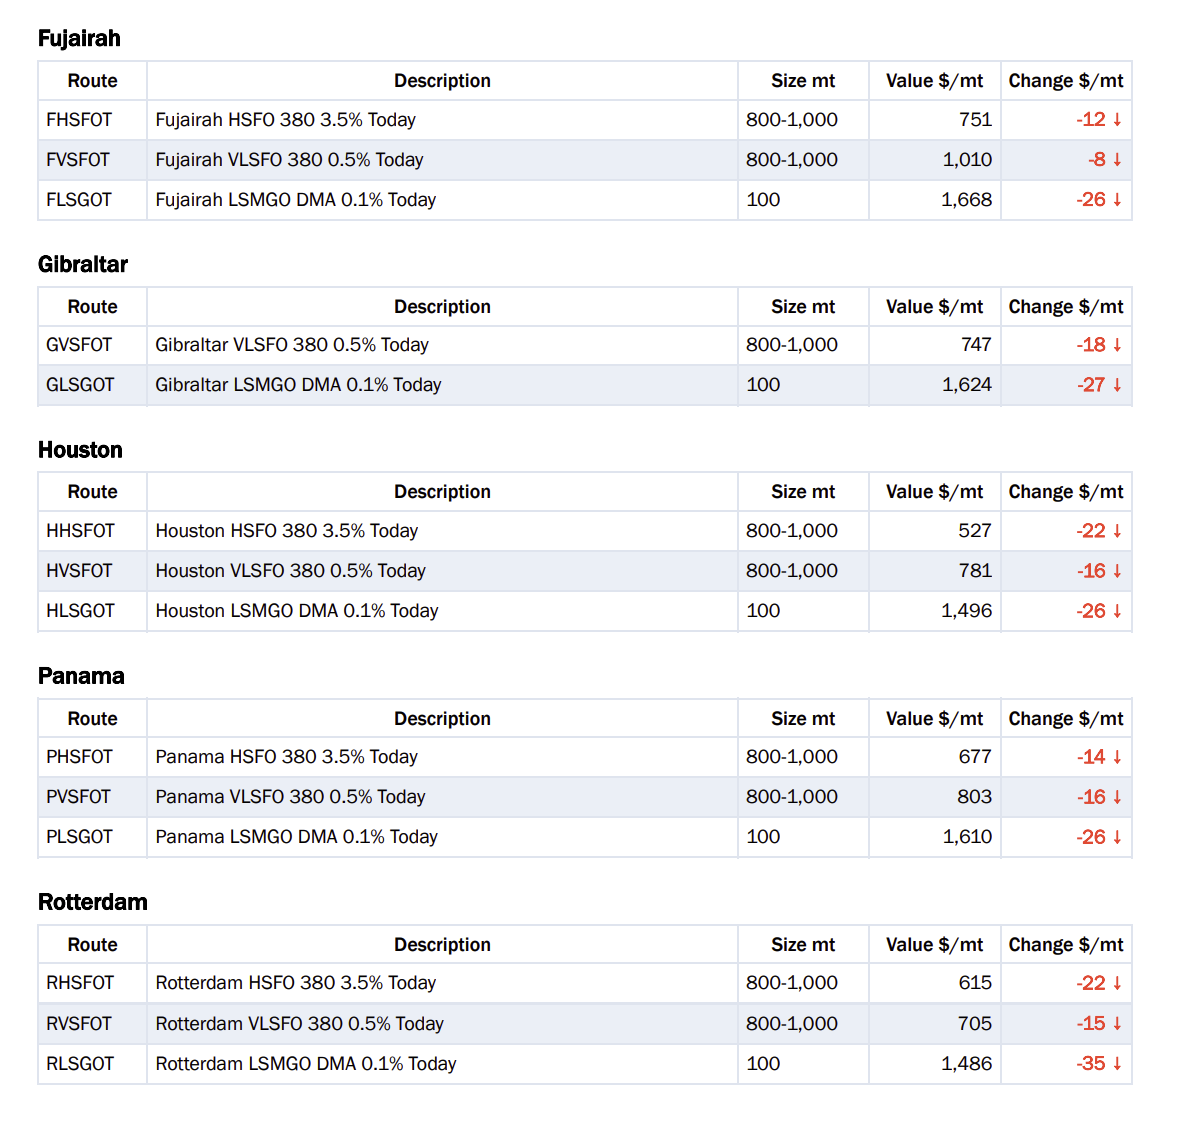
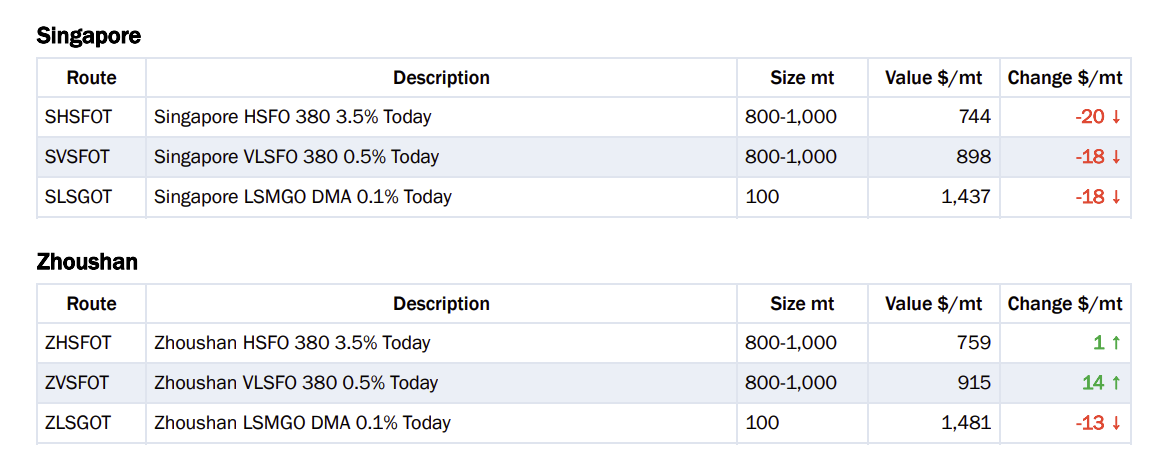
Screenshot 2026 09 18 at 1.22.26 PM

Screenshot 2026 09 18 at 1.22.41 PM

All values are in US$/metric ton, all-in (invoice price), delivered on board
Delivery in 7-10 days
ISO 8217:2010
IFO 380 3.5% Sulphur
IFO 380 0.5% Sulphur
DMA 0.1% Sulphur

Fujairah – Offshore Anchorage Area
Gibraltar – Anchorage area
Houston – Houston Harbor
Panama – (Pacific) dangerous cargo area, Balboa
Rotterdam – Waalhaven Maasvlakte range
Singapore – Anchorage, under SBA Scheme
Zhoushan – Southern anchorage area

Submitted weekly at Close of Business UK time Daily

Panellists:
Cockett Marine Oil Pte, Island Oil Limited, KPI OceanConnect, Monjasa A/S, NSI Marine and Transparensea Fuels 


Photo credit and source: Baltic Exchange
Published: 18 September, 2026

Continue Reading

Bunker Fuel

ENGINE: Americas Bunker Fuel Availability Outlook (17 Sep 2026)

New York HSFO availability to tighten; Panama Canal transits face delays; supply tight in Rio de Janeiro and Rio Grande.
Admin

Published

on

By

RESIZED ENGINE Americas

The following article regarding bunker fuel availability in the Americas region has been provided by online marine fuel procurement platform ENGINE for post on Singapore bunkering publication Manifold Times:

  • New York HSFO availability to tighten
  • Panama Canal transits face delays
  • Supply tight in Rio de Janeiro and Rio Grande

North America

Bunker demand has been good in the US Gulf Coast port of Houston over the past week and prompt fuel availability is a bit tight across most suppliers, a trader tells ENGINE.

Lead times for HSFO and LSMGO are currently estimated to be between 5-7 days, while VLSFO requires between 5-6 days.

At the Galveston Offshore Lightering Area (GOLA), high winds gusts up to 24 knots are forecast in intervals between 17-19 September and could disrupt bunker operations, a source said.

Deliveries are done on a first-come, first-served basis, subject to weather conditions. Lead times for HSFO and VLSFO are between 3-7 days at the anchorage. LSMGO has been delivered by suppliers within 2-3 days over the past week.

On the East Coast, bunker demand at the port of New York has recorded neither highs nor lows this week.

Lead times for all three conventional fuel grades are between 5-8 days. HSFO availability at New York is expected to tighten over the week, a trader tells ENGINE.

Weather conditions have been calm in New York, with winds mostly below 10 knots and gusts peaking at around 18 knots on Sunday. No backlog or bunker barge readiness issues have been reported.

Bunker demand has picked up on the US West Coast compared with previous weeks, a trader said.

Availability is normal at the ports of Los Angeles and Long Beach, where all three conventional grades require lead times of 4-7 days.

In Canada’s Vancouver the market has seen healthy demand and availability is normal. HSFO and LSMGO require lead times between 4-6 days. VLSFO requires at least five days of lead time this week, a source said.

Latin America and the Caribbean

Transits through the Panama Canal are currently subject to waiting times of 3-4 days, a source said. Lower water levels at the canal have reduced the number of transit slots available in recent weeks.

Availability is normal at Balboa and Cristobal, where HSFO, VLSFO and LSMGO can all be delivered within 3-4 days by most suppliers.

Deliveries at Balboa are done on a first-come, first-served basis, with priority given to vessels holding confirmed transit schedules, a source said.

In Colombia, prompt fuel availability is good at Cartagena, Santa Marta and Barranquilla. VLSFO and LSMGO can all be delivered within 3-4 days, a trader said.

HSFO is also available at these Colombian ports, but supply is not regular, the trader added.

HSFO supply is tight in Callao and is offered with prior consultation. VLSFO and LSMGO are more readily available and 3-7 days of lead time is recommended, a trader said.

In Brazil, availability of VLSFO and LSMGO is decent at Santos, with both grades deliverable in 6-7 days, and the port remains congested. The earliest delivery date for both the grades is 23 September, a trader said.

Supply of both grades is very tight in Rio de Janeiro, Paranagua and Rio Grande, where they are offered with prior consultation and require 7-10 days of lead time.

Belem and Vila do Conde have good availability of VLSFO and LSMGO, with lead times of 3-7 days.

At Zona Comun, VLSFO and LSMGO availability has improved, with suppliers now able to deliver within 3-6 days, down from 5-7 days previously, a source said.

Wind gusts of up to 19 knots are forecast at the Argentinian anchorage on Thursday, before conditions are set to improve after that. Deliveries are done on a first-come, first-served basis.

By Gautamee Hazarika


Photo credit and source: ENGINE
Published: 18 September, 2026

Continue Reading

Bunker Fuel

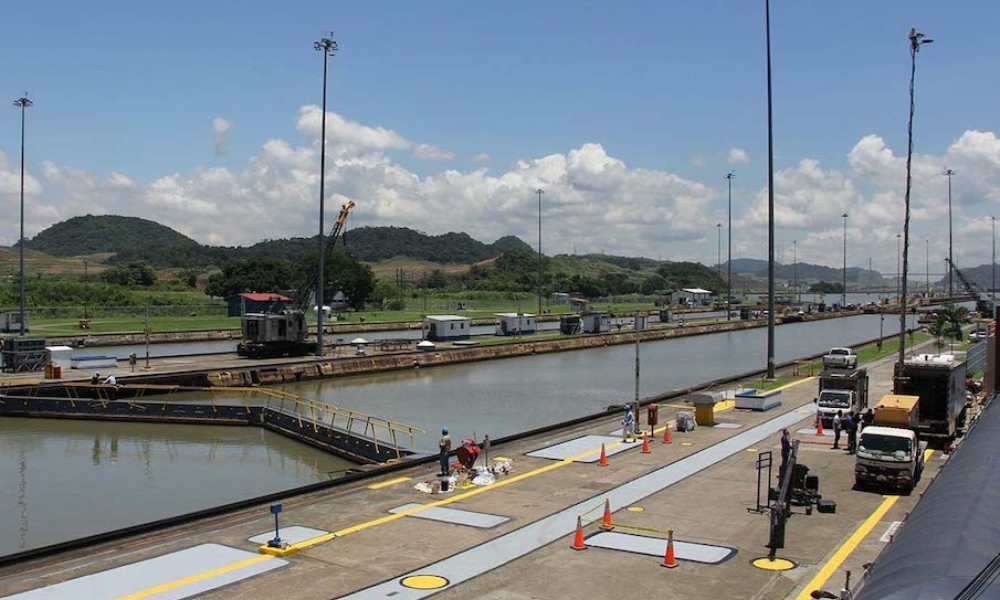
Panama bunker fuel sales down 1.8% on year in August 2026

Total bunker sales at Panama was 411,383 mt in August 2026, compared to sales of 419,056 mt during the similar period in 2025, according to PMA data.
Admin

Published

on

By

RESIZED jhernandezb05 from Pixabay

Bunker fuel sales at Panama dropped 1.8% year-on-year in August 2026, according to the latest data from La Autoridad Maritima de Panama, also known as the Panama Maritime Authority (PMA).

Total bunker sales at Panama was 411,383 metric tonnes (mt) in August 2026, compared to sales of 419,056 mt during the similar period in 2025.

In August 2026, the Pacific side of Panama posted bunker sales of 334,990 mt; 185,636 mt of VLSFO, 117,840 mt of RMG 380, 4,214 mt for marine gas oil (MGO), and 27,300 mt of low sulphur marine gas oil (LSMGO) were delivered.

The similar region saw total marine sales of 351,419 mt a year before in August; with VLSFO sales at 227,644 mt, RMG 380 sales at 84,932 mt, MGO sales at 356 mt, and 38,487 mt of LSMGO being sold.

Panama’s Atlantic side, meanwhile, recorded total bunker fuel sales of 76,393 during August 2026; the figure comprised 61,272 mt of VLSFO, 3,521 mt of RMG 380, 3,097 mt of MGO, and 8,503 mt of LSMGO.

It saw total sales of 67,637 mt in August a year before; with VLSFO sales of 53,514 mt, RMG 380 sales of 3,305 mt, 3,168 mt of MGO, and LSMGO sales of 7,650 mt.


Photo credit: jhernandezb05 from Pixabay
Published: 17 September, 2026

Continue Reading

Trending