Connect with us

Biofuel

ENGINE on Biofuel Bunker Snapshot: B30-VLSFO prices drop across global hubs

B100 price surges in Rotterdam this week; Gibraltar’s B30-VLSFO price drops sharply; Singapore’s bio-blended bunker volumes rose sharply.

Admin

Published

on

ENGINE on Biofuel Bunker Snapshot: B30-VLSFO prices drop across global hubs

Once a week, bunker intelligence platform ENGINE will publish a snapshot of biofuel bunker prices in Europe, Fujairah and Singapore. The following is the latest snapshot:

  • B100 price surges in Rotterdam this week
  • Gibraltar’s B30-VLSFO price drops sharply
  • Singapore’s bio-blended bunker volumes rose sharply

Europe

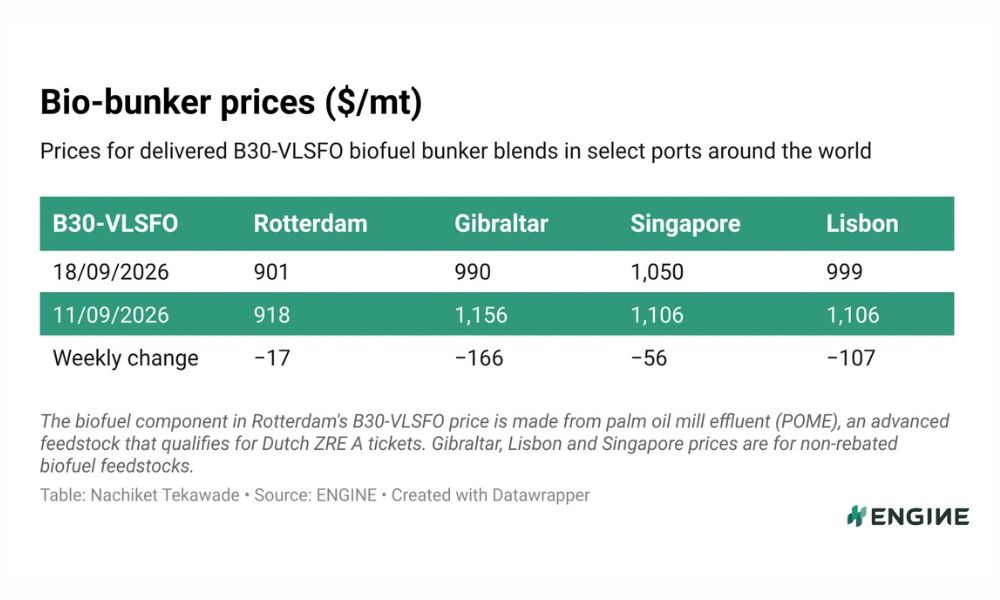
Rotterdam’s B30-VLSFO (POMEME) price has dropped $17/mt in the past week, most probably pressured by a $24/mt drop in the Dutch port’s conventional VLSFO price during the same period.

Rotterdam’s B30-LSMGO (POMEME) price has gained by $17/mt to $1,476/mt, which has been similar to a $19/mt gain in the port’s conventional LSMGO price.

B100 has been priced at $1,418/mt in Rotterdam today, a sharp $209/mt increase compared to last week.

Prima Markets’ POMEME barge price, which is an indicator of feedstock sourcing costs, has gone up by $35/mt to $2,059/mt.

Dutch suppliers can generate ZRE A tickets for selling low carbon fuels, which can be traded with other suppliers. The price of these tickets has dropped from €200/mtCO2e ($230/mtCO2e) last Friday to €190/mtCO2e ($218/mtCO2e) on Thursday this week.

Gibraltar’s B30-VLSFO (UCOME) price has slumped $166/mt lower in the past week. The port’s conventional VLSFO price has remained largely unchanged during this period.

This has cut the port’s B30-VLSFO price premium over conventional VLSFO by $172/mt in a single week to $250/mt.

Lisbon’s B30-VLSFO price has dropped $107/mt during the week. It has flipped to a modest $9/mt premium over Gibraltar’s B30-VLSFO price, coming from a $50/mt discount last Friday.

Lisbon’s B30-LSMGO price has slumped $115/mt to $1,600/mt, while the B100 price in the Portuguese port has plunged $215/mt lower to $1,665/mt.

Asia

Singapore’s B30-VLSFO (UCOME) price has dropped $56/mt since last Friday, while the port’s conventional VLSFO price has gained only $5/mt over the same period.

This has narrowed the port’s B30-VLSFO price premium by $61/mt in a single week.

Data this week showed Singapore’s bio-blended bunker sales rose by 48% in August to 57,000 mt, which was the highest monthly volume since April.

B30-VLSFO is priced at $1,015/mt in Hong Kong, which is a $35/mt price discount to Singapore.

Hong Kong’s B30-VLSFO price is at a $109/mt premium over its conventional VLSFO price.

By Nachiket Tekawade


Photo credit and source: ENGINE
Published: 22 September, 2026

Continue Reading

Alternative Fuels

GCMD, Equinor to combine expertise on alternative bunker fuels, decarbonisation solutions

Equinor brings extensive experience to partnership as a vessel charterer and marine fuel supplier, including chartering dual-fuel LNG and methanol tankers, testing biofuels and supplying methanol.
Admin

Published

on

By

GCMD, Equinor to combine expertise on alternative bunker fuels, decarbonisation solutions

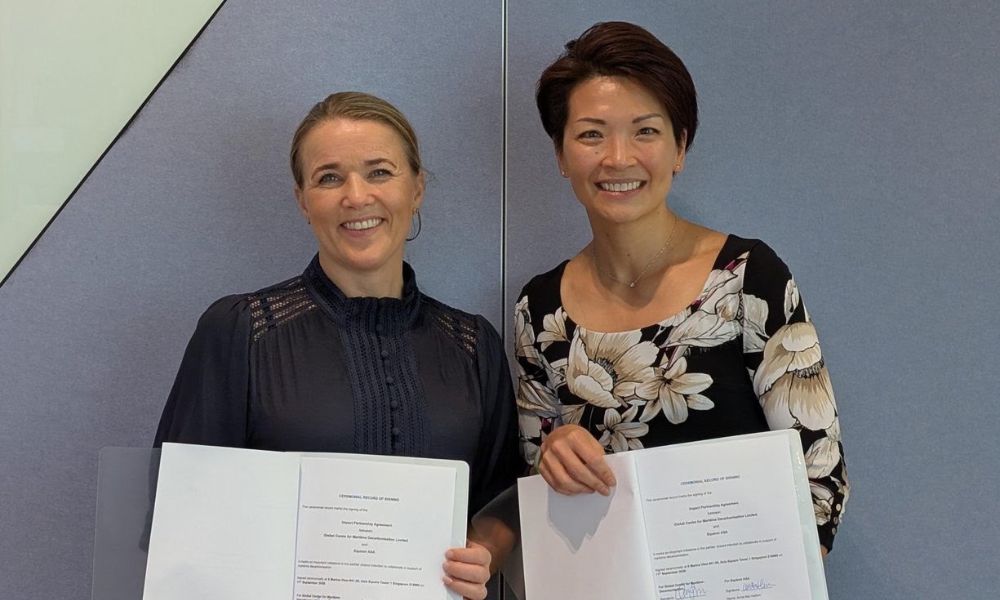
The Global Centre for Maritime Decarbonisation (GCMD) and Equinor on Tuesday (22 September) announced a five-year Impact partnership.

The partnership brings together GCMD’s capabilities in conducting real-world maritime pilots with Equinor’s experience as a charterer, energy provider and developer of low-carbon solutions.

Together, the organisations will leverage their complementary expertise to help address technical and operational gaps in scaling alternative marine fuels and supporting the development and uptake of other maritime decarbonisation solutions.

GCMD’s work on alternative fuels, including biofuels, ammonia and methanol, focuses on two critical aspects of deployment: operational safety and robust monitoring, reporting and verification (MRV). Its pilots and studies are generating operational data to support safe bunkering and handling of these fuels. 

At the same time, its assurance work seeks to strengthen confidence in quantity, quality and GHG emissions abatement.

“Equinor brings extensive experience as a vessel charterer and marine fuel supplier. This includes chartering dual-fuel LNG, LPG and methanol tankers, testing and using biofuels and supplying methanol to the maritime sector,” GCMD said.

Equinor is also piloting the use and supply of ammonia as a marine fuel, contributing to the development of associated safety, regulatory and bunkering arrangements.

Combining these perspectives can help address practical barriers to alternative fuels deployment while strengthening assurance across emerging marine fuel value chains.

Beyond alternative fuels, GCMD is working to accelerate the adoption of solutions that can reduce emissions from the existing fleet, including energy efficiency technologies (EETs) and onboard carbon capture and storage (OCCS).

GCMD’s work on EETs includes quantifying real-world fuel savings from technologies such as wind-assisted propulsion systems and developing financing mechanisms to scale their adoption. In OCCS, Project CAPTURED demonstrated an end-to-end value chain for onboard captured and liquefied CO₂, generating evidence that contributed to the recognition of captured CO2 under the EU ETS and in-principle support at the IMO for recognising carbon mineralisation as permanent storage.

Equinor brings decades of experience in offshore CO₂ storage, including its role in the development and operation of Northern Lights, the world’s first cross-border CO2 transport and storage facility, where liquefied CO₂ is transported by ship to an onshore receiving terminal before it is sent by pipeline for permanent geological storage beneath the North Sea.

Through the partnership, GCMD and Equinor will explore opportunities to combine their respective capabilities and experience to support the deployment and scaling of maritime decarbonisation solutions.


Photo credit: Global Centre for Maritime Decarbonisation
Published: 23 September, 2026

Continue Reading

Alternative Fuels

Singapore-based Golden Island, Qingdao Port team up on alternative bunker fuels

Agreement covers green methanol, green ammonia and bio-LNG, with cooperation spanning fuel production and transportation through to storage, sales and bunkering.
Admin

Published

on

By

Golden Island, Qingdao Port team up on green methanol, ammonia and bio-LNG

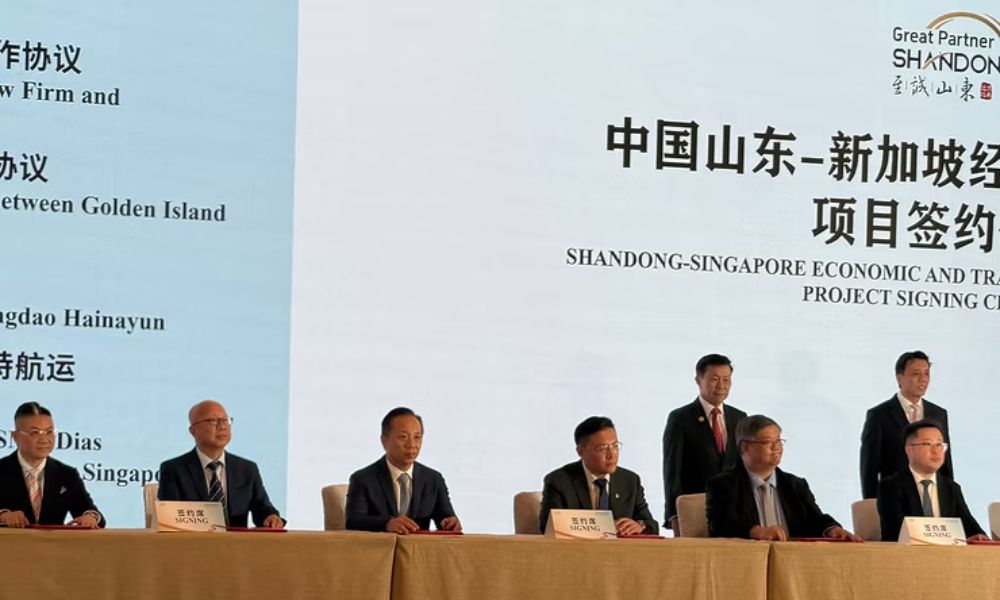
Singapore bunker supplier Golden Island Pte Ltd on Monday (21 September) said it has signed a strategic framework agreement with Qingdao Port International Co Ltd to collaborate on the supply of alternative marine fuels.

The agreement covers green methanol, green ammonia and bio-LNG, with cooperation spanning fuel production and transportation through to storage, sales and bunkering.

“By combining our MPA-licensed bunkering capabilities with Qingdao Port’s incredible logistics and strategic hub position, we are building something truly robust for the global shipping industry’s low-carbon future,” the company said in a statement. 

Qingdao Port International, which operates five major port areas in China, will bring its logistics network, storage facilities and customs clearance capabilities to the partnership.

Golden Island is licensed by the Maritime and Port Authority of Singapore (MPA) to conduct methanol bunkering and is ISCC EU-certified.

The companies are also engaging with container liners, bulk carriers, oil tankers and cruise ships regarding the adoption of alternative marine fuels.


Photo credit: Golden Island Pte Ltd
Published: 22 September, 2026

Continue Reading

Alternative Fuels

DNV on IMO CCC 12: Revised guidelines for methanol as marine fuel

CCC 12 finalized the revision of the interim guidelines for use of methyl/ethyl alcohol as fuel while work continued on guidelines for low-flashpoint oil fuels and onboard carbon capture and storage systems.
Admin

Published

on

By

RESIZED Chris Pagan

Classification society DNV on Monday (21 September) highlighted progress made on several regulatory and technical matters at the 12th session of the IMO Sub-Committee on Carriage of Cargoes and Containers (CCC 12), held from 14 to 18 September. 

This includes alternative fuels, cargo securing, onboard carbon capture systems, and battery carriage: 

Amendments to the IGF Code and development of guidelines for alternative fuels and related technologies

Methyl/ethyl alcohols

CCC 12 finalized the revision of the Interim Guidelines for the Safety of Ships Using Methyl/Ethyl Alcohol as Fuel (MSC.1/Circ.1621). The amendments revise all sections of the existing guidelines, taking into account experience gained to date.

The revised guidelines:

  • provide more flexibility in fuel tank placement and leakage-handling arrangements;
  • introduce a new concept for ventilation of fuel spaces;
  • expand guidance on the design of bunkering stations and fire extinguishing; and
  • add new guidance on bunkering operations and personal protective equipment.

Low-flashpoint oil fuels

CCC 12 continued work on the interim guidelines for ships using low-flashpoint oil fuels (fuel with a flashpoint between 52°C and 60°C). It was agreed not to develop detailed provisions for the “temperature-controlled engine room concept” but focus on a safety concept more aligned with the existing guidelines under the IGF code, however with major simplifications of the safety barriers. Work on the interim guidelines will continue in a Correspondence Group aiming for finalization at CCC 13 in 2027.  

Fuel cell power installations and IGF Code amendments

The revision of the Interim Guidelines for the Safety of Ships Using Fuel Cell Power Installations (MSC.1/Circ.1647), and other proposals for amendments to the IGF Code were not discussed in detail, but work will continue in a Correspondence Group reporting to CCC 13 in 2027.  

Development of a safety regulatory framework to support the reduction of GHG emissions from ships using new technologies and alternative fuels

Onboard carbon capture and storage (OCCS)

CCC 12 started the discussion to develop guidelines for the safety of ships fitted with OCCS. The guidelines should contain a technology-neutral main body for common ship-level requirements, while technology-specific safety requirements will be placed in individual annexes. Work on the guidelines will continue in a Correspondence Group reporting to CCC 13 in 2027. The guidelines are expected to be finalized in 2028.

Note: The full technical and regulatory news by DNV can be found here


Photo credit: Chris Pagan on Unsplash
Published: 22 September, 2026

Continue Reading
Advertisement

OUR INDUSTRY PARTNERS


Trending