Methanol
China’s first domestically developed Ultramax methanol dual-fuel bulker pair named
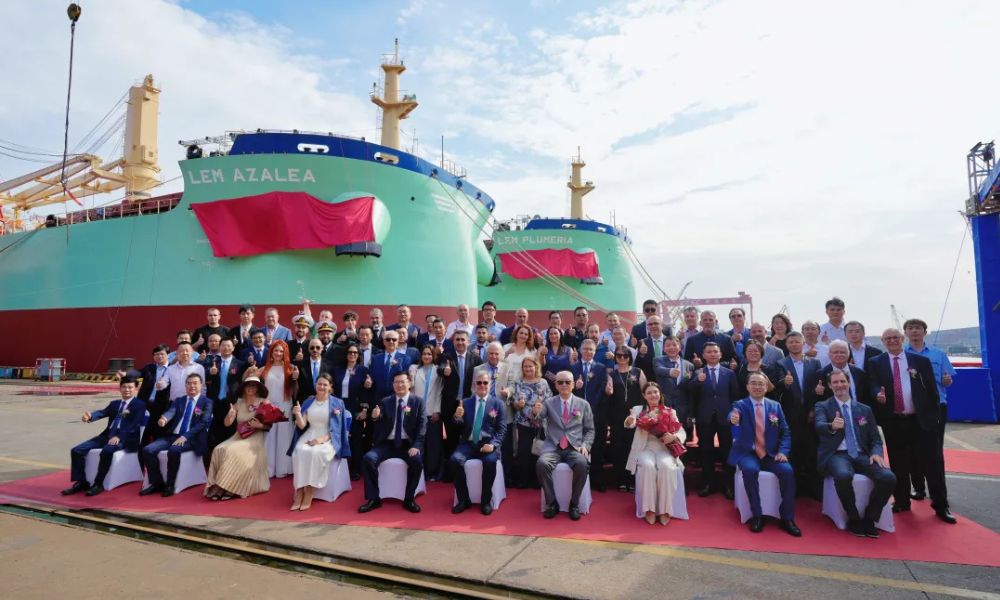
SDARI says two 65,000 dwt methanol dual-fuel bulk carriers, “LEM AZALEA” and “LEM PLUMERIA”, were named on 27 July at Guangzhou’s Nansha district.

Alternative Fuels
GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050
New fuels could reach around 60% of fleet energy consumption under a sufficiently strong carbon price signal, modelled at USD 700/tCO2e by 2050.
With vessels operating for 25 to 30 years and only around 4% of the fleet renewed annually, newbuild decisions made over the coming decade will establish much of the engine capacity available in 2050, Global Centre for Maritime Decarbonisation said on Thursday (17 September).
Yet having the capacity to consume a new fuel does not guarantee its uptake. Dual-fuel engines allow shipowners to switch between conventional fuels and the selected new fuel as economics and regulations evolve; continued fuel competitiveness is therefore critical to what vessels ultimately consume.
These are among the findings of Navigating the maritime fuel transition: How fuel economics, regulations, and fleet decisions shape the future bunkering landscape, based on a model jointly developed by the GCMD and Boston Consulting Group (BCG).
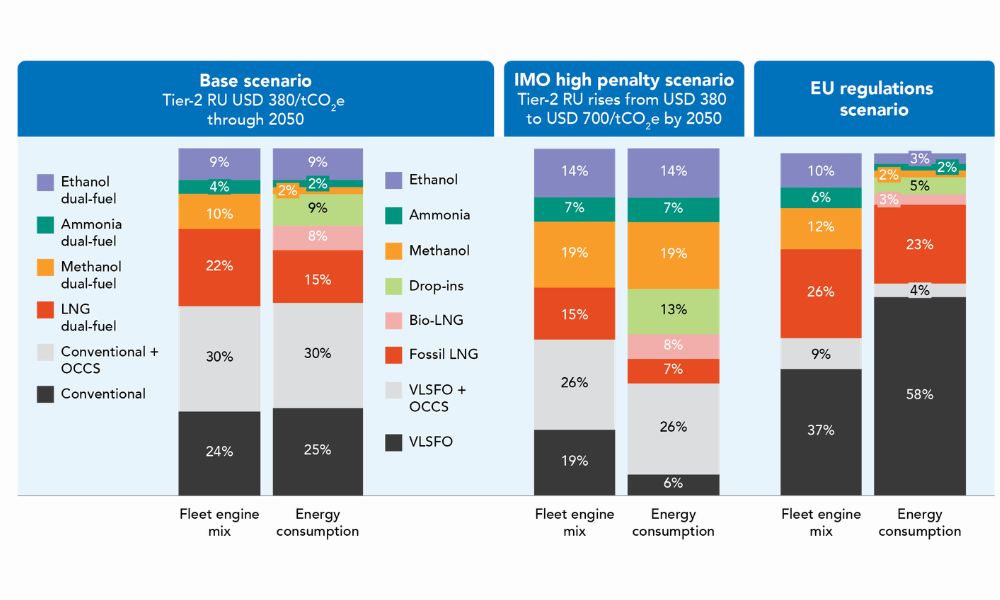
The model illustrates this dynamic in its base scenario. With the Tier-2 penalty under the IMO Net-Zero Framework held at USD 380/tCO2e through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity in 2050, but methanol represents just 2% of fleet energy consumption. With conventional fuels remaining more economical under this regulatory regime, methanol dual-fuel vessels continue to operate on fuels cheaper than methanol (Figure 1).
A global carbon price of USD 700/tCO2e materially changes the transition
The base scenario demonstrates how fuel economics can limit uptake even when vessels have the capacity to use new fuels. This picture changes if the IMO Tier-2 penalty rises to USD 700/tCO2e by 2050, at which point new fuels, including dropins, reach approximately 61% of fleet energy consumption (Figure 1).
By contrast, EU regulations alone will not drive a marked global shift, as they cover only around 20% of international shipping’s energy demand.
Overall cost of using e-methanol and e-ammonia is near parity
While a stronger global carbon price can accelerate the shift towards new fuels, the model does not point to a clear cost winner between e-methanol and e-ammonia.
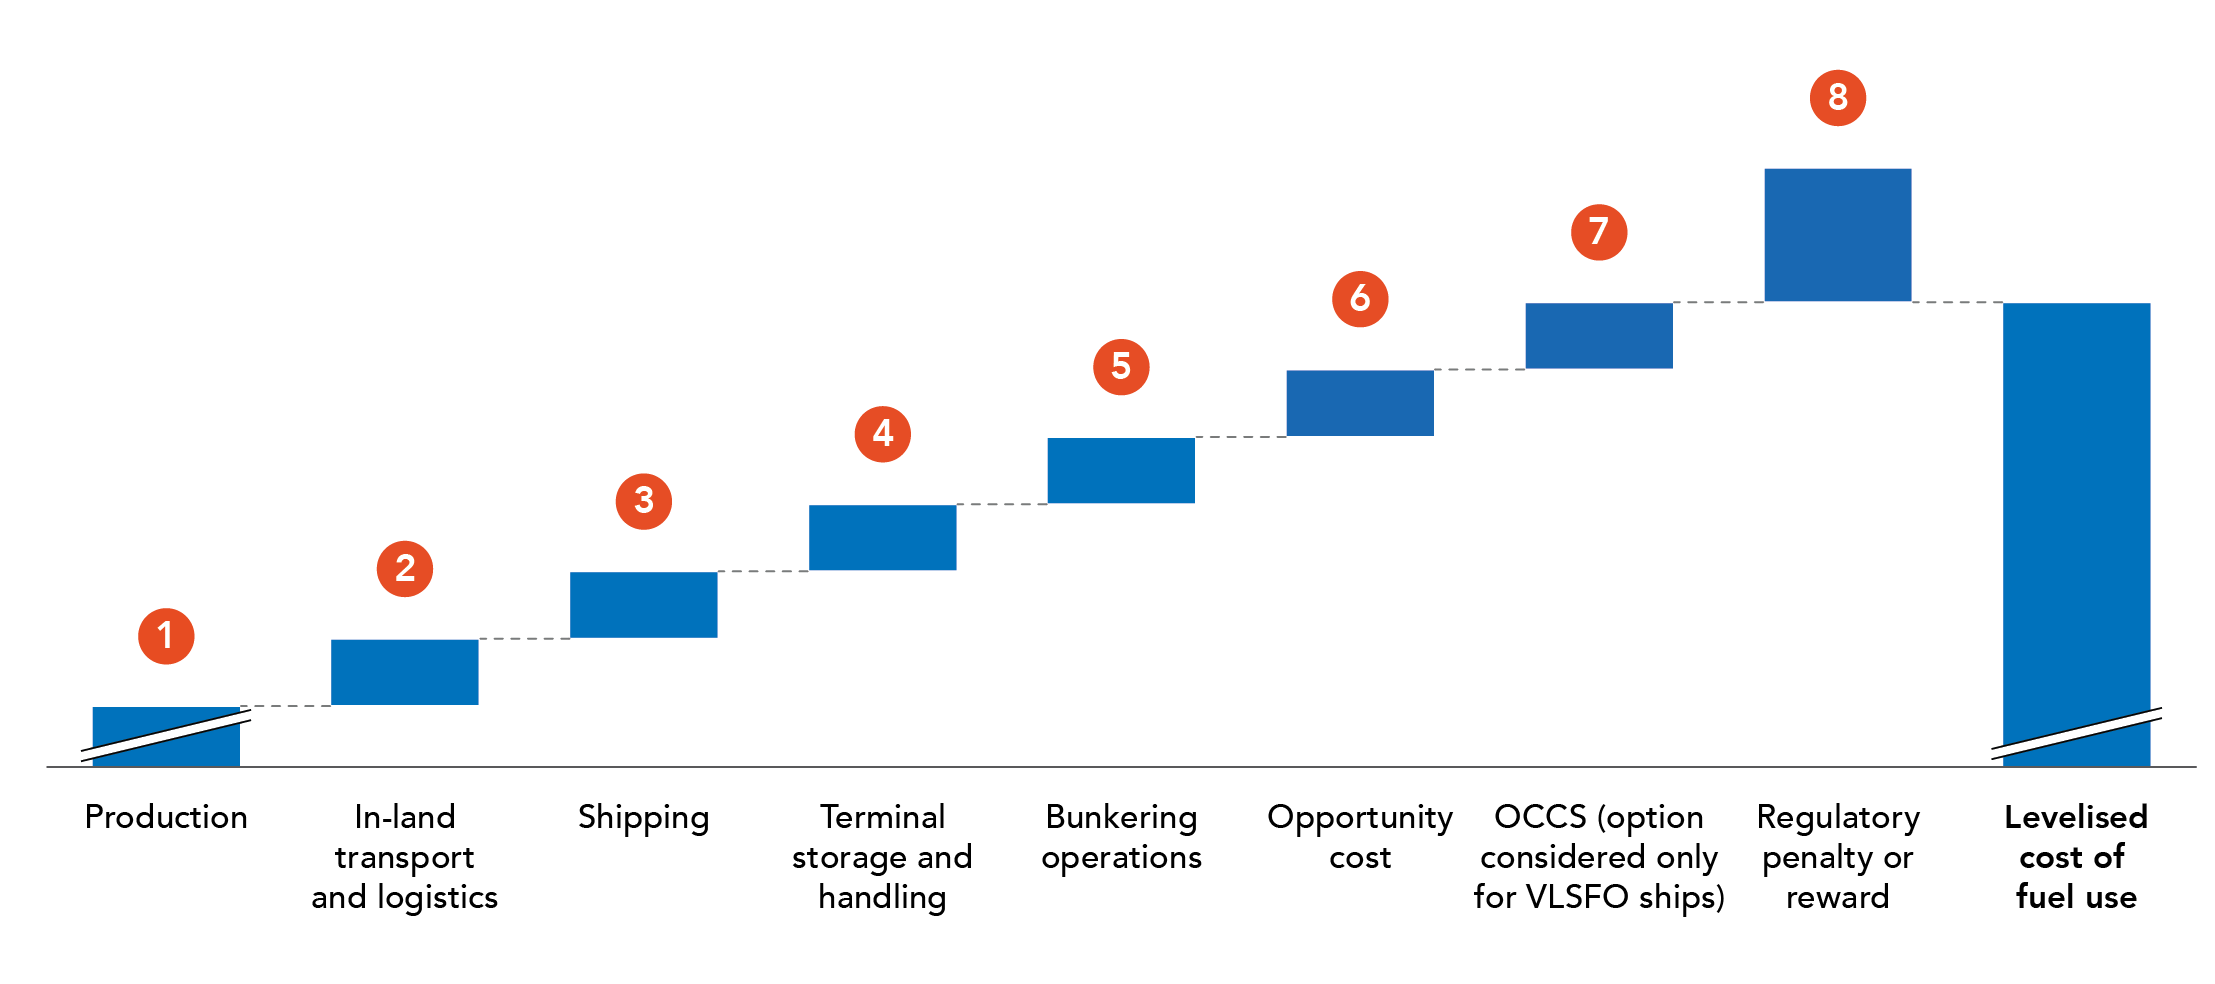
E-ammonia’s production cost advantage is largely offset by higher logistics costs arising from its toxicity, including specialised crew training, larger exclusion zones, and more complex bunkering. As a result, the overall cost (Figure 2) of using e-ammonia and e-methanol is near parity through to 2050.
Professor Lynn Loo, CEO of GCMD, said: “Many vessels ordered over the coming decade will still be operating in 2050. Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear.
“Our modelling puts into perspective just how difficult closing the cost gap between new and conventional fuels will be. The carbon price required to close this gap is substantial. And achieving it will be particularly challenging in today’s geopolitical environment. Understanding the signposts that could change these economics will be critical to the decisions the industry makes today.”
Anand Veeraraghavan, Managing Director & Senior Partner at BCG, said: “The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness.
“Rather than offer a single prediction, our approach with GCMD maps how sensitive each fuel pathway’s competitive position is to a handful of critical variables — policy scenarios, key cost drivers, and potential restrictions. Our hope is that this gives shipowners, fuel suppliers, port operators, and infrastructure investors a practical tool to stress-test their own fuel strategies as conditions change.”
Photo credit: Global Centre for Maritime Decarbonisation
Published: 18 September, 2026
Methanol
SGMF releases first ISO-compliant Life Cycle Assessment of methanol as a marine fuel
Study evaluates 15 methanol production pathways and finds that methanol produced using renewable energy sources can deliver substantial emissions reductions.
Alternative Fuels
Singapore: Bunker fuel sales down by 4% on year in August 2026
4.77 million metric tonnes of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt recorded during the similar month in 2025, according to MPA.
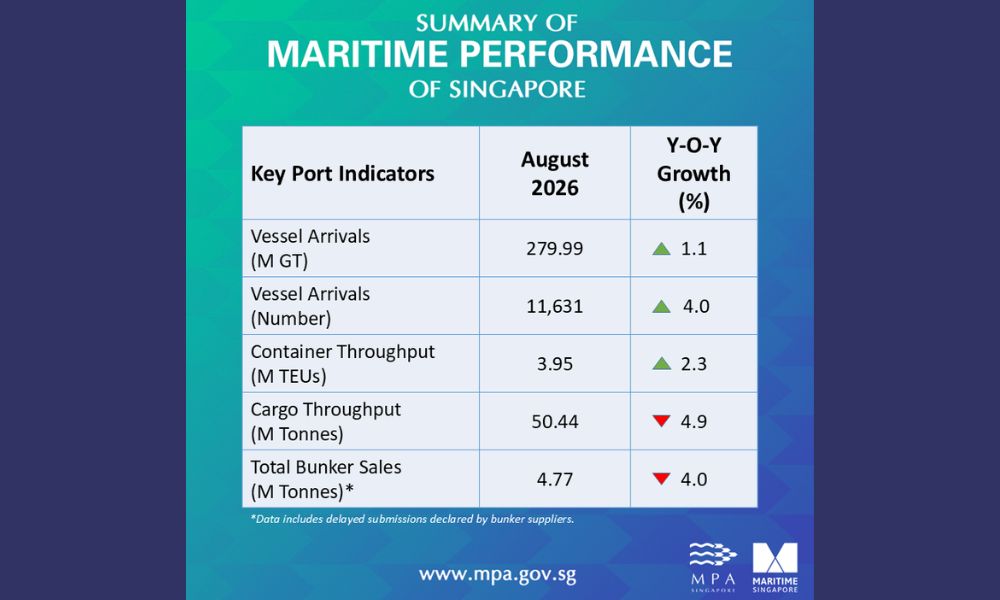
Sales of marine fuel at Singapore port fell by 4% on year in August 2026, according to data from the Maritime and Port Authority of Singapore (MPA).
In total, 4.77 million metric tonnes (mt) (exact 4,772,700 mt) of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt (4,965,300 mt) recorded during the similar month in 2025.
Deliveries of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August (against on year) recorded respectively 2.1 million mt (11.1% from 1.89 million mt), 2.19 million mt (-12.4% from 2.50 million mt), zero (from zero), zero (-100% from 1,800 mt) and zero (from zero).
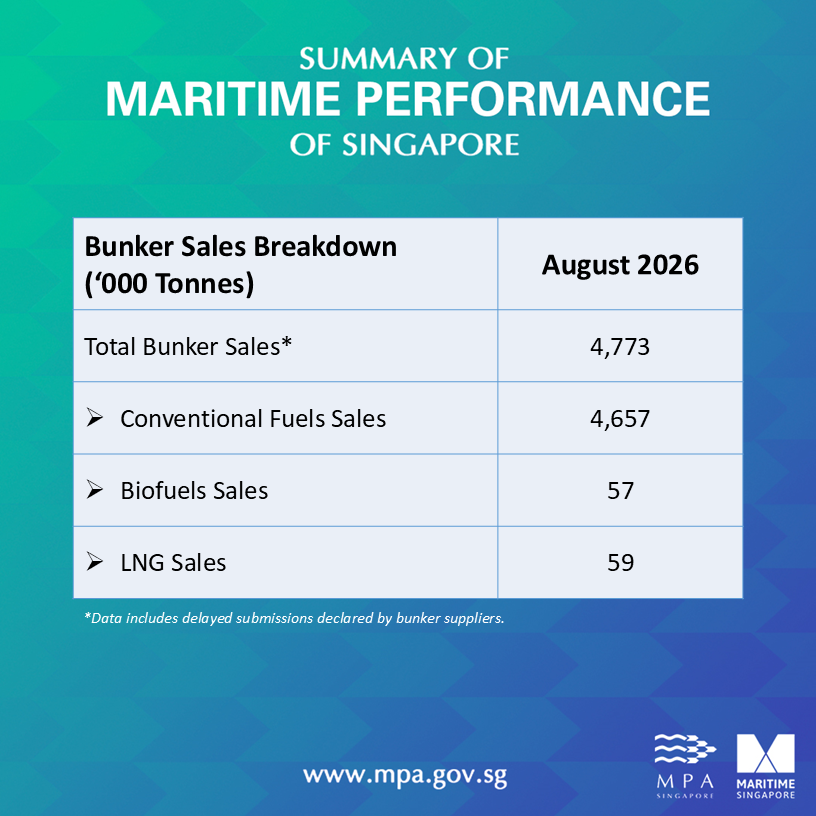
Bio-blended variants of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August, (against on year) recorded respectively 8,700 mt (-74.9% from 34,700 mt), 47,900 mt (-48.9% from 93,800 mt), zero (from zero), zero (from zero) and zero (from zero). B100 biofuel bunkers, introduced in February last year, recorded 800 mt (-83.3% from 4,800 mt).
LNG and methanol sales were 58,600 mt (-12.5% from 67,000 mt) and zero (from zero) respectively. There were no recorded sales of ammonia for the month and so far since 2025.
Photo credit: Maritime and Port Authority of Singapore
Published: 15 September, 2026

OUR INDUSTRY PARTNERS

Singapore: Liquidator of Da Xin Tankers, Nan Chiau Maritime issues notices of dividend

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

Peninsula: Missing “Hercules Star” crew member found dead after Dubai incident

DNV: Existing ammonia shipping and safety expertise key to scaling new supply chains

Baltic Exchange: Bunker Report (17 September 2026)

ENGINE: Americas Bunker Fuel Availability Outlook (17 Sep 2026)
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
Singapore: Liquidators of Nan Ho Maritime, Nan Xin Maritime issue notices of dividend

Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE

Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea

Kongsberg Maritime to buy Finnish marine propulsion designer Steerprop
-
 Incident1 week ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Winding up5 days ago
Singapore: Marine fuel testing firm CCIC Singapore faces winding up application
-
 Alternative Fuels2 weeks ago
Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
-
 Winding up2 weeks ago
Singapore: Liquidators of Nan Ho Maritime, Nan Xin Maritime issue notices of dividend
-
 Technology1 week ago
Singapore: MPA working with industry on next phase of digital bunkering, says Deputy CE
-
 Ammonia1 week ago
Amogy and LOTTE Fine Chemical to explore ammonia bunkering in South Korea
-
 Business2 weeks ago
Kongsberg Maritime to buy Finnish marine propulsion designer Steerprop
-
 Winding up6 days ago
High Court of Singapore issues winding up order against Hengli Petrochemical International