By Steve Christy, Expert Contributor, Integr8 Fuels
16 September 2026
Another surge in bunker prices
Bunker prices have surged four times since the start of the US-Iran war, but this time we are at the highest levels since mid-March, just after the war started. At the time of writing, Brent futures were trading in the $107-108/bbl range, with indications that prices could rise further. Prices in our markets can only follow what is happening to Brent. Even though the Singapore VLSFO premium to crude has diminished, we are still paying $100/mt more than we were three weeks ago.
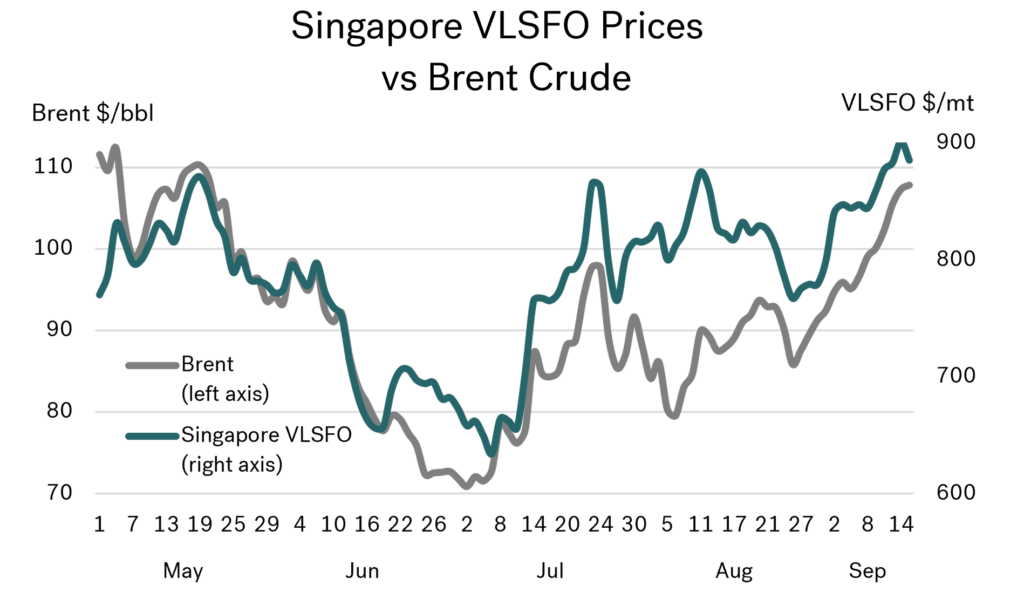
This latest price hike comes amid massively increased tensions in the Red Sea region, following drone attacks on the 7 million b/d Saudi East-West crude pipeline and Houthi military advances in the Bab al-Mandab Strait. With the Strait of Hormuz effectively closed, the East-West pipeline had been the major alternative outlet for getting Saudi crude into the international market via the Red Sea. It is now closed.
In addition, some Saudi refining assets in the east are operating at low, or even zero, throughputs. It’s all a recipe for sending shock waves through the market and pushing oil prices and bunker prices even higher.
Uncertainty continues to drive the price outlook
We know price movements are directly linked to the events and psychology surrounding the US-Iran war, and that these are impossible to predict. For a number of months, we have discussed the US midterm elections in early November as a potential backstop to the war, with a peace agreement bringing US gasoline prices down by at least 25% and potentially becoming a vote-winner for the Republicans. However, it looks like President Trump is taking a different approach to attract voters, and an end to the war before November now seems unlikely.
President Trump has acknowledged that oil prices are unlikely to fall before the midterms. Just last week, on his way to Dallas for the Republican Midterm Convention, he was quoted as saying, “Right after the election, oil prices are going to be tumbling downward” and “I think it’s going to take a little bit longer than the midterm”.
At this stage, there is no sign of prices falling anytime soon, either before or after the midterms. However, all it takes is a peace agreement that is either agreed or remarkably close to being signed, and it could come out of the blue. All we can do in the bunker market is keep watching and working within this framework.
Bunker quality deserves a closer look
In last month’s report, we highlighted that the 8-14 million b/d reduction in global oil supply was entirely concentrated in medium and heavy crude grades (below 34° API), while supplies of lighter crude remained broadly unchanged. This clearly poses a challenge to refiners and blenders and is something we as bunker buyers must be aware of.
The US Gulf is an interesting area to look at
In the analysis here, we take a dive into the US Gulf market, looking at how changes in the crude slate can take place. In the first instance, the US is likely to be least affected by the loss of Middle East supplies. In terms of regional impacts, Asia-Pacific, followed by Europe and then the US, have been hardest hit. But no area is immune from what is happening elsewhere in the world, and there have been significant changes in the crudes going into US Gulf refineries.
Firstly, refinery margins are high, so there are strong incentives to run, if you can! In the US, refinery utilisation rates are incredibly high, averaging close to 97% over the past three months. This is the highest three-month average since 1998!
However, it is not simply a case of processing more US crude in US refineries and exporting less. There are a lot of economic forces at work to ‘complicate’ things. The strong international demand for crude to replace lost Middle East volumes has ‘pulled’ more US volumes towards Europe and Asia. The economic balance has been for US Gulf refiners to import more crude themselves, while also running down domestic crude oil stocks. So, we have high US refinery runs, high US crude exports and high US crude imports all at the same time.
The door to Middle East crude has closed, but one to Venezuela has opened
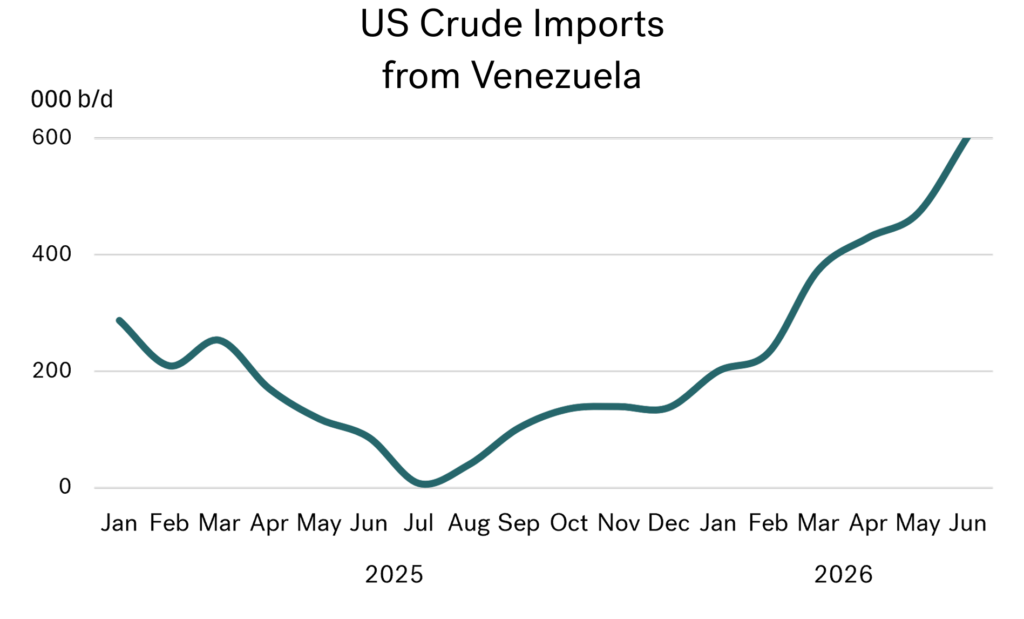
Apart from pure economics, we know there can be a huge political influence on our markets. The obvious examples are the Middle East and the Russia-Ukraine war, but there is also Venezuela. After the US captured and removed President Maduro in January this year, the US-Venezuelan relationship has reopened. As part of this, the US is now importing significantly more Venezuelan crude.
For more than seven years, the US had imported between zero and 0.2 million b/d of Venezuelan crude each month. Since Maduro was removed, monthly imports have increased, reaching 0.6 million b/d in June, the latest available data, with several US Gulf refiners taking these grades.
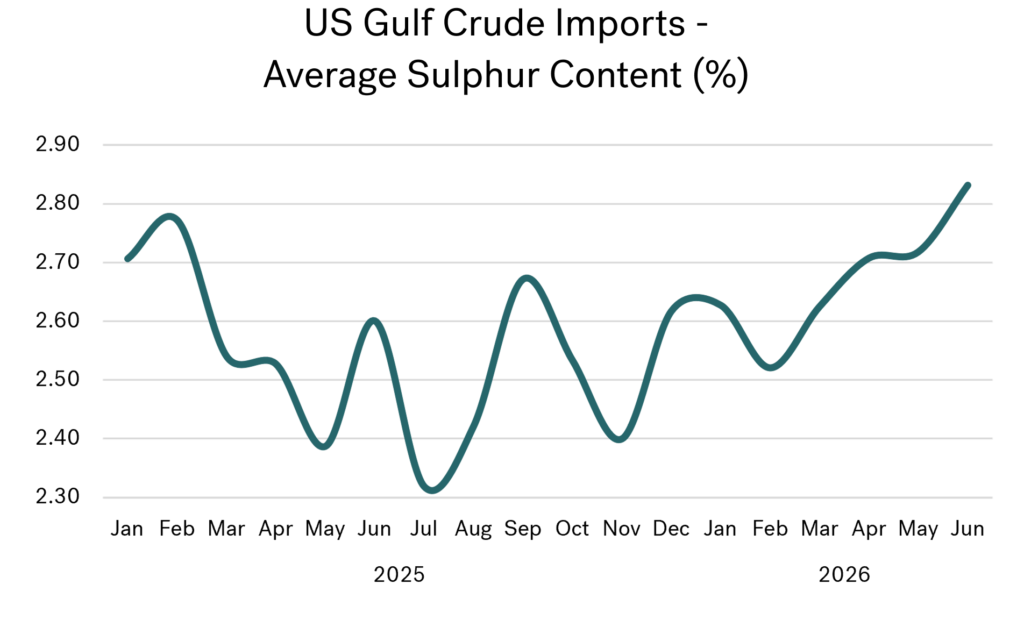
The significance for us is that Venezuelan crudes are very heavy and have a very high sulphur content. In June, the average sulphur content of these Venezuelan crudes was 3.25%, ranging as high as 5.8%. In terms of density, the average API gravity for these crudes was only 15° to 22.3° API, with some grades as low as 10° API.
Venezuela has shifted the US Gulf crude slate
The increase in Venezuelan crude imports into the US, driven by renewed political ties and market dynamics surrounding the US-Iran war, has resulted in a much higher average sulphur content of overall US Gulf crude imports, rising from 2.5-2.6% in the first quarter of this year to 2.8% in June.
Similarly, the average API gravity of US Gulf crude imports has fallen from around 23° API to below 20° APImore recently.
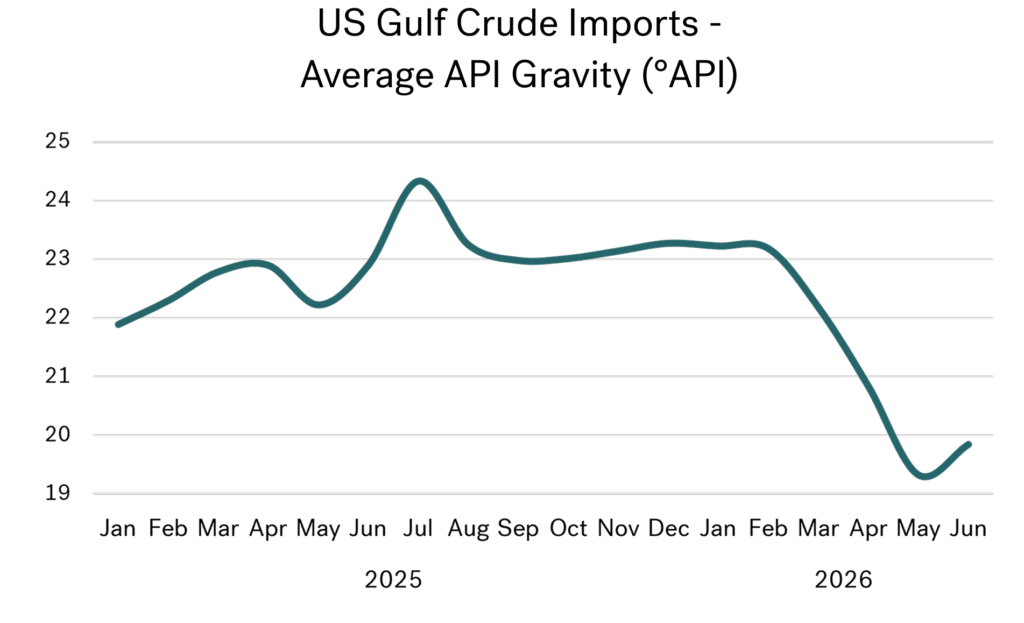
Processing these crudes also brings other considerations, including potentially higher levels of vanadium, nickel and acidity. For us in bunkers, these are all factors worth watching as the US Gulf crude slate continues to change.
Assuming the political relationship between the US and Venezuela continues to develop, we can expect increases in Venezuelan crude production and growing volumes of these heavy, high-sulphur crudes being processed in the US refining system.
Price is not the only concern
As with these US Gulf refiners, many other refineries are now processing different crudes from earlier this year. All these changes reinforce the point: bunker quality needs to be monitored just as closely as price.
Photo credit and source: Integr8 Fuels
Published: 28 September, 2026