Bunker Fuel Availability
ENGINE: Americas Fuel Availability Outlook (30 July 2026)
Bunker demand is strong in Houston; fuel availability is good in Panama; tight avails in Paranagua, Rio Grande.

Alternative Fuels
Singapore: Bunker fuel sales down by 4% on year in August 2026
4.77 million metric tonnes of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt recorded during the similar month in 2025, according to MPA.
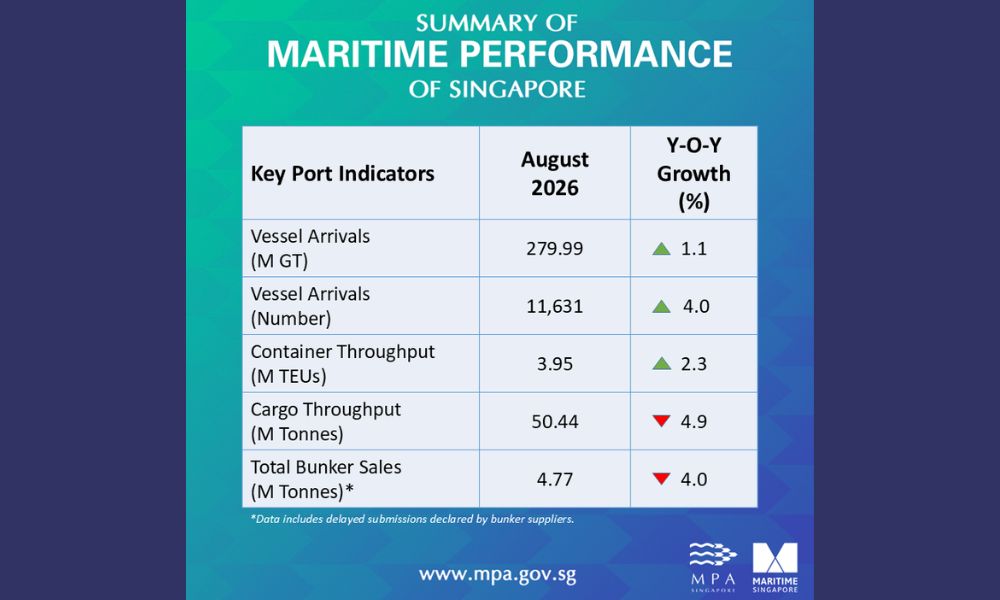
Sales of marine fuel at Singapore port fell by 4% on year in August 2026, according to data from the Maritime and Port Authority of Singapore (MPA).
In total, 4.77 million metric tonnes (mt) (exact 4,772,700 mt) of various marine fuel grades were delivered at the world’s largest bunkering port in August, up from 4.97 million mt (4,965,300 mt) recorded during the similar month in 2025.
Deliveries of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August (against on year) recorded respectively 2.1 million mt (11.1% from 1.89 million mt), 2.19 million mt (-12.4% from 2.50 million mt), zero (from zero), zero (-100% from 1,800 mt) and zero (from zero).
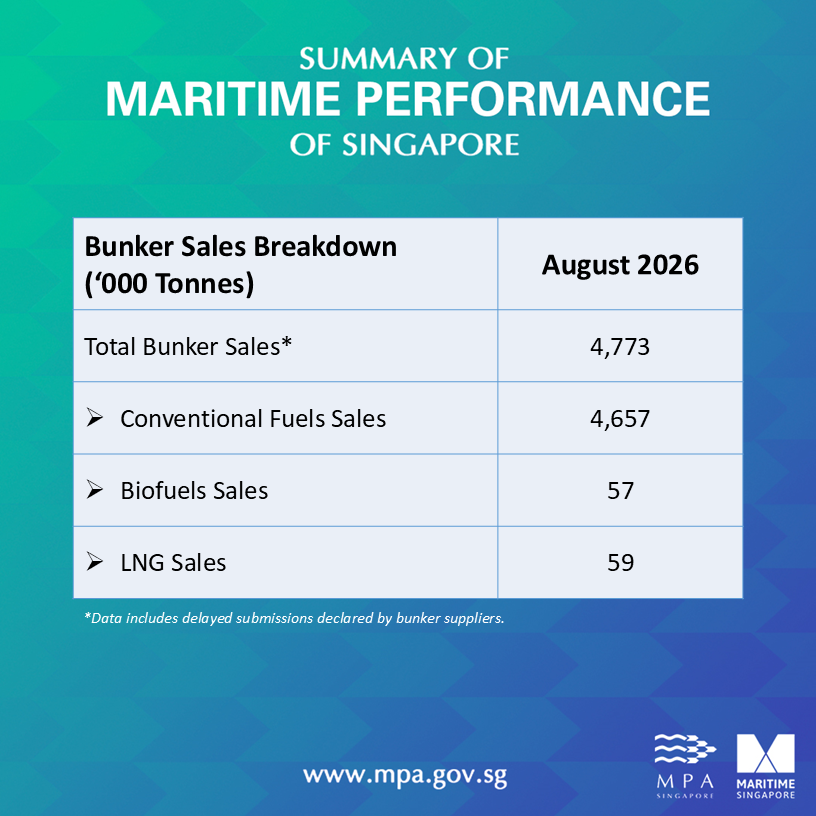
Bio-blended variants of marine fuel oil, low sulphur fuel oil, ultra low sulphur fuel oil, marine gas oil and marine diesel oil in August, (against on year) recorded respectively 8,700 mt (-74.9% from 34,700 mt), 47,900 mt (-48.9% from 93,800 mt), zero (from zero), zero (from zero) and zero (from zero). B100 biofuel bunkers, introduced in February last year, recorded 800 mt (-83.3% from 4,800 mt).
LNG and methanol sales were 58,600 mt (-12.5% from 67,000 mt) and zero (from zero) respectively. There were no recorded sales of ammonia for the month and so far since 2025.
Photo credit: Maritime and Port Authority of Singapore
Published: 15 September, 2026
Alternative Fuels
ENGINE on Fuel Switch Snapshot: Gas supply risks lift Rotterdam’s LNG and LBM
B30-LSMGO swings to $37/mt discount to LNG (Otto MS); Singapore LNG (diesel SS) discount to LSMGO widens; ZRE A tickets surge on aggressive compliance buying.
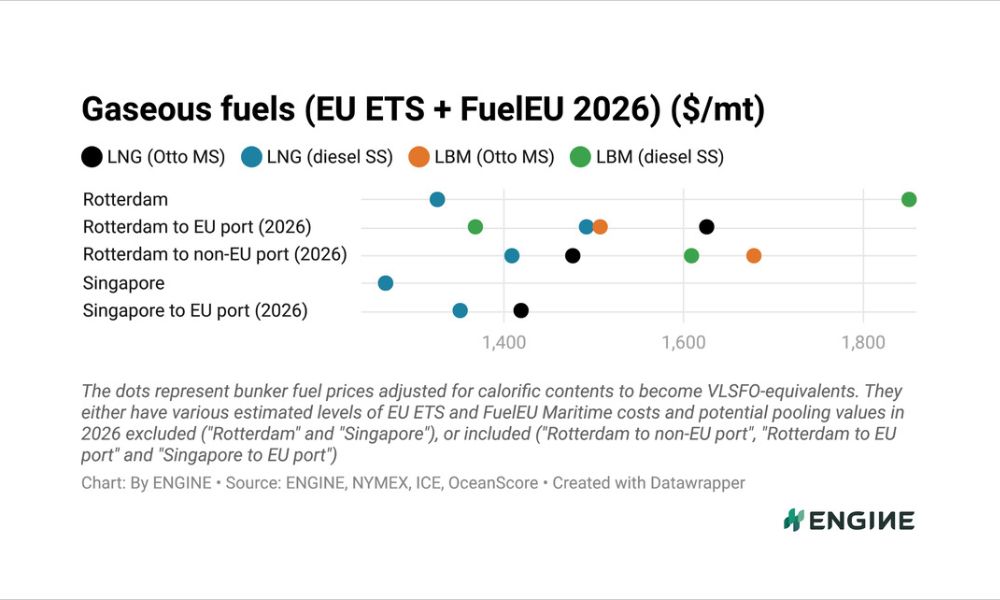
Once a week, bunker intelligence platform ENGINE will publish a snapshot of alternative and conventional bunker fuel prices in the world’s two biggest bunkering hubs. The following is the latest snapshot:
14 September 2026
- B30-LSMGO swings to $37/mt discount to LNG (Otto MS)
- Singapore LNG (diesel SS) discount to LSMGO widens
- ZRE A tickets surge on aggressive compliance buying
Rotterdam’s B30-LSMGO has swung from a $90/mt premium over LNG burnt in Otto medium speed (Otto MS) engines to a $37/mt discount, as LNG has gained $150/mt over the past week against the blend’s $24/mt.
Liquefied biomethane’s (LBM) premiums over HSFO in Rotterdam have widened by $105-107/mt to $348-487/mt depending on engine type, and over VLSFO by $90-92/mt to $233-372/mt.
LBM’s discounts to LSMGO have narrowed by $6-8/mt to $261-400/mt. Its premiums over B100 have widened by $84-86/mt to $271-411/mt.
Rotterdam’s LNG premiums over VLSFO have widened by $95-97/mt to $356-492/mt depending on engine type, and LNG’s discounts to LSMGO have narrowed by $11-13/mt to $141-277/mt.
In Singapore, LNG’s premiums over VLSFO have narrowed by $1-2/mt to $255-323/mt, and its discounts to LSMGO have widened by $85-86/mt to $88-155/mt. The wider discount is for vessels with diesel slow speed (diesel SS) engines.
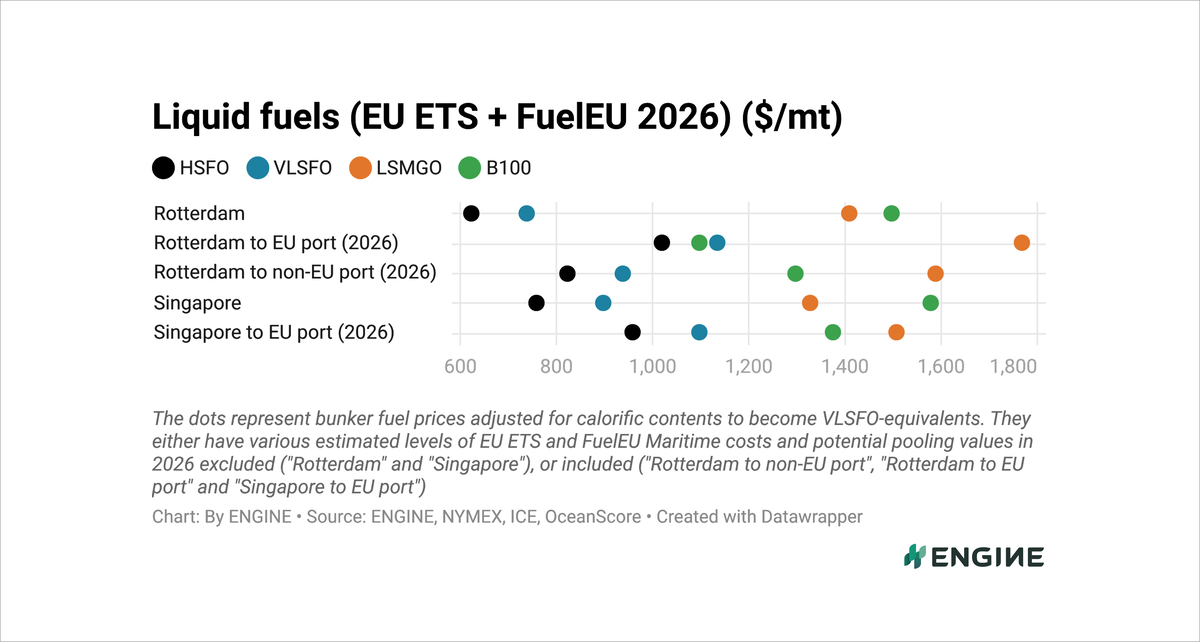
B100’s premium over HSFO in Rotterdam has widened by $21/mt to $76/mt while its discount to VLSFO has narrowed by $6/mt to $39/mt. Its discount to LSMGO has widened by $78/mt to $672/mt.
Singapore’s B100 has widened its premium over VLSFO by $14/mt to $280/mt and its discount to LSMGO by $70/mt to $130/mt.
ENGINE-assessed FuelEU Maritime pooling values have eased by $1/mt for both B100 and LBM, the smaller credits adding to each fuel’s gains, while the OceanScore FuelEU pooling index has held at €118.90/mtCO2e ($138/mtCO2e).
Liquid fuels
Rotterdam’s conventional fuel prices have gained $38-137/mt over the past week, with LSMGO up the most and its benchmark at the highest level in at least four years.
B100 has gained $59/mt and B30-VLSFO $64/mt.
Dutch ZRE A tickets have moved up by €21/mtCO2e ($24/mtCO2e) to €200/mtCO2e ($232/mtCO2e) over the past week. Compliance buyers rather than speculators have driven the increase, Prima Markets analyst Ulrich Arnheiter said.
Conventional bunker fuel availability in the ARA is tight for prompt deliveries, with lead times of 5-7 days advised for most grades, a trader said.
Singapore’s conventional fuel prices have gained $49-133/mt, again with LSMGO up the most, and B100 has gained $63/mt.
Supply in Singapore has remained constrained despite subdued demand, with VLSFO lead times of 12-15 days against 9-16 days a week earlier.
Front-month ICE Brent futures have rallied $10.53/bbl ($77/mt) higher to $108.72/bbl ($797/mt), lifted by vessel attacks near the Strait of Hormuz and Saudi Arabia halting flows through its East-West Pipeline. Dec26 EUA prices have risen by $2.99/mtCO2e to $102.47/mtCO2e.
Liquid gases
Rotterdam’s LNG prices have gained $148-150/mt depending on engine type over the past week, and the port’s LBM prices $143-145/mt, tracking a sharp rise in the front-month Dutch TTF gas contract.
How long the Strait of Hormuz stays closed remains the single most important supply-side uncertainty, IEA gas analyst Greg Molnár said.
Rotterdam’s LBM discounts to LNG have widened by $5/mt to $119-124/mt depending on engine type.
Singapore’s LNG prices have gained $46-47/mt depending on engine type, tracking the front-month NYMEX Japan/Korea Marker.
LNG importers continue to seek cargoes with no resolution of the Middle East conflict in sight, ANZ Bank senior commodity strategist Daniel Hynes said.
By Erik Hoffmann
Photo credit and source: ENGINE
Published: 15 September, 2026
Bunker Fuel
JLC China Bunker Fuel Market Monthly Report (August 2026)
China sold 1.61 million mt of bonded bunker fuel in August, with the daily sales at 51,974 mt, down by 9.62% month on month, JLC’s data shows.

Beijing-based commodity market information provider JLC Network Technology Co. recently shared its JLC China Bunker monthly report for August 2026 with Manifold Times through an exclusive arrangement:
Bunker Fuel Demand
China’s bonded bunker fuel sales decline in August
China sold 1.61 million mt of bonded bunker fuel in August, with the daily sales at 51,974 mt, down by 9.62% month on month, JLC’s data shows.
Typhoons continued in many regions in August, and some ports in East China even suspended bunkering temporarily.
Meanwhile, bonded bunker fuel supply at some domestic ports remained tight, which also dragged down the sales.
Shipowners were still cautious about bunkering as bonded bunker fuel prices remained on the rise.
Regarding the sales by supplier, the sales by Chimbusco, Sinopec (Zhoushan), SinoBunker, and China Changjiang Bunker (Sinopec) respectively settled at 315,000 mt, 620,000 mt, 57,000 mt, and 5,000 mt in the month, while those by suppliers with regional bunkering licenses settled at 614,200 mt.
China’s LSFO output drops in August
Chinese refiners produced about 1.12 million mt of low-sulfur fuel oil (LSFO) in August, with the daily output at 36,258 mt, a cut of 12.87% month on month, JLC’s data shows.
Specifically, Sinopec’s LSFO output slipped in the month, as refineries were more inclined to produce gasoline and diesel when cracking spreads of these two products increased.
Meanwhile, certain refineries were still under maintenance, which also capped the overall output.
PetroChina lowered its refineries’ LSFO production plans due to tightening export quotas.
By contrast, CNOOC recorded an increase in its output, with T aizhou Petrochemical resuming production.
Zhoushan Petrochemical did not produce any LSFO in the month.
ZPC and Sinochem did not produce any LSFO in the month, but the latter produced and exported 10,000 mt of marine gas oil (MGO).


Domestic-trade bunker fuel demand weakens in August
Domestic-trade bunker fuel demand continued to weaken in August, as inland and coastal shipping remained seasonally tepid and port operations in East China were hindered by severe weather.
Domestic-trade heavy bunker fuel demand settled at 270,000 mt in the month, with the daily demand at 8,710 mt, down by 10.00% month on month, JLC’s data shows.
In the meantime, domestic-trade light bunker fuel demand fell to 120,000 mt, with the daily volume at 3,871 mt, down by 14.29% from the prior month, the data shows. Downstream buying interest was depressed by high MGO prices.
Bunker Fuel Supply
China’s bonded bunker fuel imports increase in July
China’s bonded bunker fuel imports increased in July, as some bonded distributors resumed imports of LSFO after a three-month suspension.
The country imported 530,400 mt of bonded bunker fuel in the month, a modest boost of 2.93% month on month, calculations show, based on the GACC data.
Bonded bunker suppliers imported some LSFO to meet demand when domestic production retreated.
In addition, they increased purchases of imported high-sulfur fuel oil (HSFO) in June when the conflict between the U.S. and Iran eased, leading to a rise in the arrivals for July.
The arrivals of imported MGO also grew in July.
On a year-on-year comparison, however, China’s bonded bunker fuel imports plunged by 17.54% in July.
Regarding the imports by source, Russia remained the largest supplier by exporting 234,600 mt of bonded bunker fuel to China, accounting for 44.23% of the latter’s total imports. Singapore became the second largest supplier with 153,800 mt, accounting for 29.00%, while South Korea slipped to the third place with 81,100 mt, accounting for 15.30%. Japan ranked fourth with 60,800 mt, accounting for 11.47%.
China’s bonded bunker fuel imports totaled 3.91 million mt in the first seven months of this year, an increase of 1.68% from the same period of time in 2025, calculations also indicate.

Domestic-trade bunker fuel supply tightens in August
Chinese blenders supplied 250,000 mt of domestic-trade heavy bunker fuel in August, with the daily supply at 8,065 mt, down by 7.41% month on month, JLC’s data shows.
Despite some unit restarts, blendstock supply was still relatively tight, especially low-sulfur residual oil supply .
Meanwhile, blenders in North China showed lower blending interest amid stricter tax inspections, and they maintained low inventories of consumption-tax-included bunker fuel.
Domestic-trade MGO supply settled at 150,000 mt in August, with the daily supply at 4,839 mt, down by 11.76% month on month, the data shows. Refineries’ production enthusiasm was dampened by high feedstock costs and tight feedstock supply.

Bunker Prices, Profits

Editor
Yvette Luo
+86-020-38834382
[email protected]
Sales (Beijing)
Tony Tang
+86-10-84428863
[email protected]
Sales (Singapore)
Ginny Teo
+65-31571254
[email protected]
[email protected]
JLC Network Technology Co., Ltd is recognised as the leading information provider in China. We specialise in providing the transparent, high-value, authoritative market intelligence and professional analysis in commodity market. Our expertise covers oil, gas, coal, chemical, plastic, rubber, fertilizer and metal industry, etc.
JLC China Bunker Fuel Market Monthly Report is published by JLC Network Technology Co., Ltd every month on China bunker market, demand, supply, margin, freight index, forecast and so on. The report provides full-scale & concise insight into China bunker oil market.
All rights reserved. No portion of this publication may be photocopied, reproduced, retransmitted, put into a computer system or otherwise redistributed without prior authorization from JLC.
Related: JLC China Bunker Fuel Market Monthly Report (July 2026)
Related: JLC China Bunker Fuel Market Monthly Report (June 2026)
Related: JLC China Bunker Fuel Market Monthly Report (May 2026)
Related: JLC China Bunker Market Monthly Report (April 2026)
Related: JLC China Bunker Market Monthly Report (March 2026)
Related: JLC China Bunker Fuel Market Monthly Report (February 2026)
Related: JLC China Bunker Market Monthly Report (December 2025)
Related: JLC China Bunker Market Monthly Report (November 2025)
Related: JLC China Bunker Fuel Market Monthly Report (October 2025)
Related: JLC China Bunker Fuel Market Monthly Report (September 2025)
Related: JLC China Bunker Fuel Market Monthly Report (July 2025)
Related: JLC China Bunker Fuel Market Monthly Report (June 2025)
Related: JLC China Bunker Fuel Market Monthly Report (May 2025)
Related: [Updated 15 May] JLC China Bunker Market Monthly Report (April 2025)
Related: JLC China Bunker Market Monthly Report (February 2025)
Related: JLC China Bunker Fuel Market Monthly Report (January 2025)
Related: JLC China Bunker Fuel Market Monthly Report (December 2024)
Related: JLC China Bunker Fuel Market Monthly Report (November 2024)
Related: JLC China Bunker Fuel Market Monthly Report (October 2024)
Related: JLC China Bunker Fuel Market Monthly Report (September 2024)
Related: JLC China Bunker Fuel Market Monthly Report (August 2024)
Related: JLC China Bunker Fuel Market Monthly Report (July 2024)
Related: JLC China Bunker Fuel Market Monthly Report (June 2024)
Related: JLC China Bunker Fuel Market Monthly Report (May 2024)
Related: JLC China Bunker Market Monthly Report (April 2024)
Related: JLC China Bunker Market Monthly Report (March 2024)
Related: JLC China Bunker Fuel Market Monthly Report (February 2024)
Related: JLC China Bunker MaAmogy, LOTTE Fine Chemical to explore ammonia bunkering in South Korearket Monthly Report (January 2024)
Note: China-based commodity market information provider JLC Technology has been providing Singapore bunkering publication Manifold Times China bunker volume data since 2020. Data from earlier periods are available here.
Photo credit: JLC Network Technology
Published: 11 September, 2026

OUR INDUSTRY PARTNERS

Singapore: Marine fuel testing firm CCIC Singapore faces winding up application

Singapore: Bunker fuel sales down by 4% on year in August 2026

ABS joins Korean initiative to develop standards for hydrogen-fuelled ships

World’s first operational ammonia bunker vessel enters service following conversion

IBIA Africa update: Algoa Bay remains a missed bunkering opportunity

ENGINE on Fuel Switch Snapshot: Gas supply risks lift Rotterdam’s LNG and LBM

APPEC 2026: Digitalisation in bunkering not merely a ‘paper-to-screen’ swap, states panellists

Rajah & Tann: Bunker disputes are won in the first 48 hours

Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor

Singapore strengthens LNG bunkering framework with new SS 727 standard

Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean

Auramarine: Marine fuel flexibility will be key to shipping’s energy transition

TFG Marine advances global MFM rollout with two US Gulf bunker barges

Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Bunker Claim2 weeks ago
Rajah & Tann: Bunker disputes are won in the first 48 hours
-
 Vessel Arrest2 weeks ago
Malaysia: MMEA detains two vessels over suspected illegal ship-to-ship transfer off Johor
-
 LNG Bunkering2 weeks ago
Singapore strengthens LNG bunkering framework with new SS 727 standard
-
 Alternative Fuels2 weeks ago
Yang Ming orders six LNG dual-fuel, ammonia-ready containerships from Hanwha Ocean
-
 Alternative Fuels1 week ago
Auramarine: Marine fuel flexibility will be key to shipping’s energy transition
-
 Mass Flowmeter2 weeks ago
TFG Marine advances global MFM rollout with two US Gulf bunker barges
-
 Incident5 days ago
Peninsula confirms one fatality, crew member missing from bunker tanker “Hercules Star”
-
 Winding up1 week ago
Singapore: Liquidators of Nan Ho Maritime, Nan Xin Maritime issue notices of dividend